


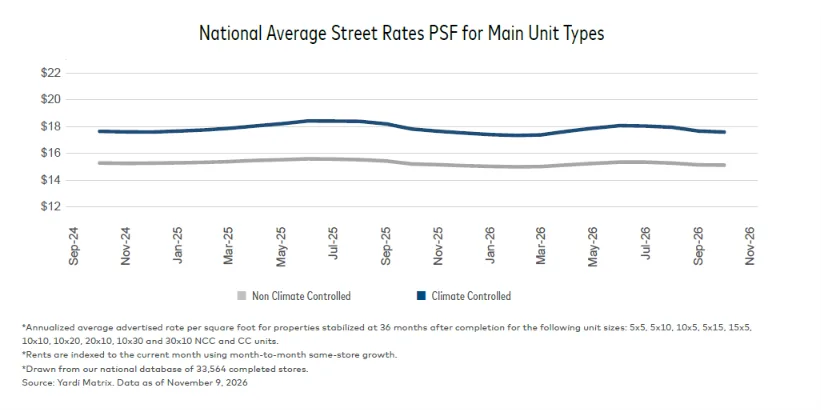
- Yardi Matrix reports national advertised self storage rates fell 0.6% year over year in October, versus 1.8% in September, to $16.16 per square foot, with all 30 top metros improving.
- All four public self storage REITs posted same-store revenue and NOI growth in Q3, but Matrix cautions that fewer move-ins and weak demand indicators point to retention, not rebounding demand.
- Under-construction supply fell to 2.0% of existing stock, which should ease pressure, though recent deliveries in Florida markets like Sarasota-Cape Coral may weigh on rates near term.
Storage rents are still sliding, just slower. Yardi Matrix’s November self storage report has national street rates 0.6% lower than a year earlier in October. That’s an improvement on the 1.8% slide in September and 1.9% in August.
Average advertised rent now stands at $16.16 per square foot across all unit types.
Get Smarter about what matters in CRE
Stay ahead of trends in commercial real estate with CRE Daily – the free newsletter delivering everything you need to start your day in just 5-minutes
Broad Improvement
Each of the 30 top metros did better on an annual basis than it did in September. Year-over-year gains showed up in 11 metros for non-climate-controlled units and nine for climate-controlled.
On a monthly basis, rates slipped 0.3%, compared with a 1.7% plunge in October 2025. Eight metros grew, against none a year ago, and Detroit’s 1.2% gain was the best.
Recovery, With Caveats
For the first time since Q2 2023, all four listed storage REITs grew both same-store revenue and income in Q3, and each lifted its annual outlook. Matrix puts blended revenue growth at 1.5% and NOI growth at 2.3%.
Those gains came as move-ins weakened. Tenants are staying longer and leaving less often, which helped occupancy rise year over year for a third quarter, but Matrix doesn’t read that as demand coming back.
October also benefited from a soft comparison. Rates dropped more in October 2025 than in any month Matrix has tracked.
Supply Eases
Deliveries over the trailing year equal 2.1% of starting stock, versus 2.9% a year earlier. Projects under construction total about 42.4 million rentable square feet, or 2.0% of inventory, 40 basis points lower than last October.
Still, the last three years added 8.6% to inventory. Facilities opened within two years list rents 10% to 15% beneath stabilized peers.
Zoom Out
TractIQ’s tally, which we covered, also found all four storage REITs growing NOI in Q3. Supply conditions vary by market: GlobeSt reported that New York City builders face cost and zoning barriers, while Matrix counts the New York suburbs among markets with rising rates.
Why It Matters
San Francisco has the strongest backdrop, with AI-driven hiring and tight housing. Matrix notes that a thin pipeline isn’t sufficient: Portland and Denver still saw rates fall.
In Sarasota-Cape Coral, a year of deliveries equal to about 10% of starting inventory is likely to pressure rates before the market recovers, Matrix says.
What’s Next
Matrix expects the annual decline to shrink further in Q4, as the comparison period shifts to late 2025’s deeper drops. After that, new demand has to carry pricing.