- Independent operators manage 65.7% of tracked self storage facilities, but only 46.2% of SF because their properties are far smaller than REIT-run stores.
- Independent street rates rose 6.5% year over year versus 4.7% for REITs, while the occupancy rebound was concentrated in non-REIT properties.
- TractIQ tracks 1,508 self storage loans totaling $28.48B maturing through 2028, including 731 independent-operator loans averaging just $2.6M.
TractIQ’s August market briefing argues that most US self storage facilities operate outside the public REIT universe. Its database tracks 68,019 operating facilities and 2.77B SF. Independent operators manage 43,939 properties, or 65.7% of the total, while REITs manage 16.3%. Because independent facilities are smaller, those operators control 46.2% of tracked SF compared with 29.4% for REITs.
Get Smarter about what matters in CRE
Stay ahead of trends in commercial real estate with CRE Daily – the free newsletter delivering everything you need to start your day in just 5-minutes
The Industry Changes Outside Major Markets
The size gap is substantial. The median independently managed facility is 17,150 SF, compared with 64,905 SF for a REIT-run store. REIT brands manage 50.7% of self storage SF in the top 25 metropolitan areas. Their share falls to 9.7% outside the top 100 markets.
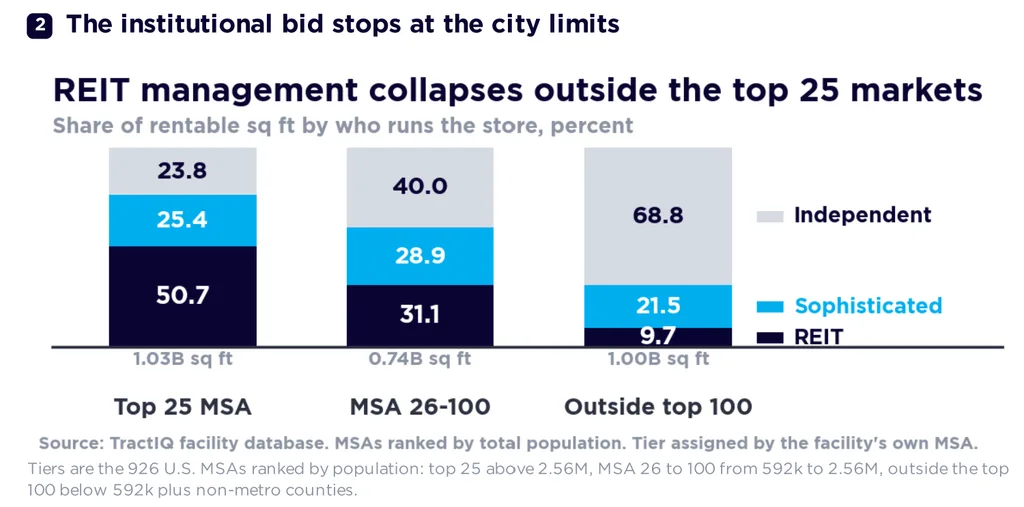
Outside those top 100 metros, 536 of 826 markets have no REIT-managed SF at all. Those smaller markets still contain about 1.00B SF of inventory. That is nearly equal to the 1.03B SF inside the top 25 metros. TractIQ’s data therefore describes a large operating universe that public-company reporting captures only partially.
The Details
Independent operators posted the strongest year-over-year street-rate growth in July. Rates rose 6.5% to $1.078 PSF per month, versus a 4.7% increase for REITs and 1.6% for sophisticated non-REIT operators. REIT street rates remained 41% above independent rates in August, but the premium narrowed to 12% on web pricing.
Online discounting explains much of that difference. TractIQ found 98.8% of REIT-run stores offered web rates at least 2% below street pricing, compared with 18% of independents. REIT web pricing of $1.130 PSF was almost identical to the $1.133 PSF level among sophisticated operators.
Occupancy showed a similar split. In a same-store CMBS pool, REIT occupancy slipped 10 basis points to 89.4% between March 2025 and March 2026. Sophisticated operators gained 810 basis points to 83.2%, while independents improved 130 basis points to 86.5%.
Supply Pressure Is Concentrated
The active construction pipeline includes 632 projects totaling 47.1M SF, equal to 1.70% of existing stock. Another 29.5M SF is permitted and ready to start, while 144.3M SF remains in planning. TractIQ said construction pressure is highest in the top 25 metros, where projects equal 2.69% of inventory, compared with 0.94% outside the top 100.
However, small markets can face sharper local shocks. Only 98 of 826 markets outside the top 100 have any construction underway. Among those, 19 markets have pipelines exceeding 10% of current inventory, and the highest reaches 73.6%. A single project can therefore have a much larger pricing impact in a small market than in a major metro.
Debt Maturities Could Feed Small Deals
TractIQ tracks 1,508 first-mortgage loans totaling $28.48B that mature between August 26, 2026, and year-end 2028. Independent operators account for 731 loans, or 48% of the count, but only $1.88B of balance. Their average loan is $2.6M, compared with $38.6M for REIT-managed facilities and $33.3M for sophisticated operators.
That concentration of smaller loans could create transaction opportunities for private buyers. Independent loans also carry the highest average coupon in the group at 6.04%. The data add a financing angle to self storage operating trends. Refinancing pressure sits heavily with small owners even though institutions hold most of the dollar balance.
A Possible Floor Is Forming
Several indicators have stopped deteriorating. The national 10-by-10 street rate bottomed at $1.173 PSF in December 2025. It reached $1.357 in August after rising in eight of the next nine months. Non-core cap rates held in a 7% to 8.5% range, while construction remained at 1.70% of stock.
TractIQ also noted that non-core cap rates expanded roughly 250 basis points from 2021, compared with only 25 to 50 basis points for core assets. At a 7.75% cap rate, $100,000 of NOI implies about $1.29M of value. At a 5.25% cap rate in 2021, the same NOI implied $1.90M, a 32% difference.
What’s Next
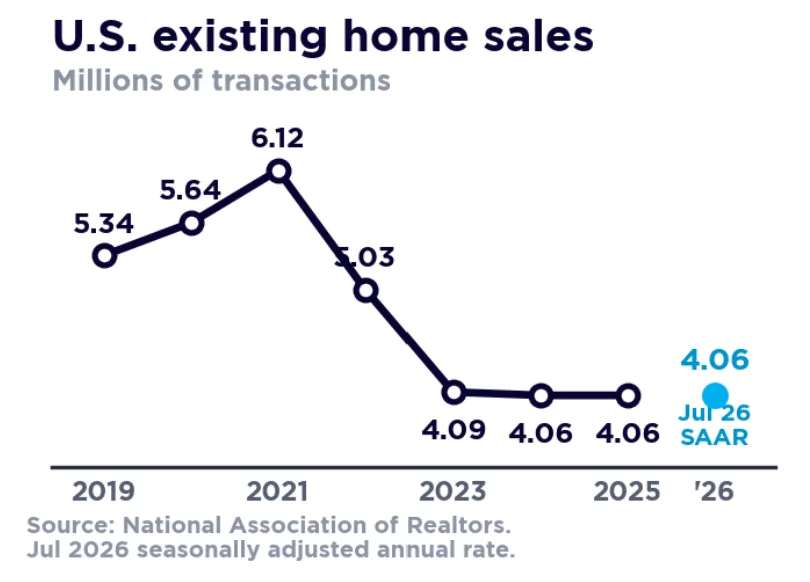
The report identifies several variables for 2027. They include whether winter street-rate gains hold, how much planned supply converts when construction debt loosens, and how Public Storage reprices the newly acquired NSA tertiary portfolio. Housing turnover also matters because longer tenant stays have supported storage demand during a weak home-sales period.
The largest near-term catalyst may be loan maturities. TractIQ expects the 2027 and 2028 maturities to clear through some mix of refinancing, recapitalization, and sales. For investors, the key distinction is that the industry’s largest dollar balances are institutional, while much of the potential transaction count sits with smaller independent operators.