

- Brookfield is giving up the $600 million, 785-unit Beaudry tower in downtown Los Angeles, under four years after it opened, rather than refinance a loan of about $360 million.
- The lender, Apollo-owned Bridge Investment Group, is working to sell the loan. The tower is about 95% occupied at asking rents near $4,200, per CoStar, well below what Brookfield targeted.
- Landlords face about $1.8 trillion in debt over the next decade, nearly half due by 2028, and multifamily CMBS delinquencies have jumped to 7.1% from 1% in October 2023.
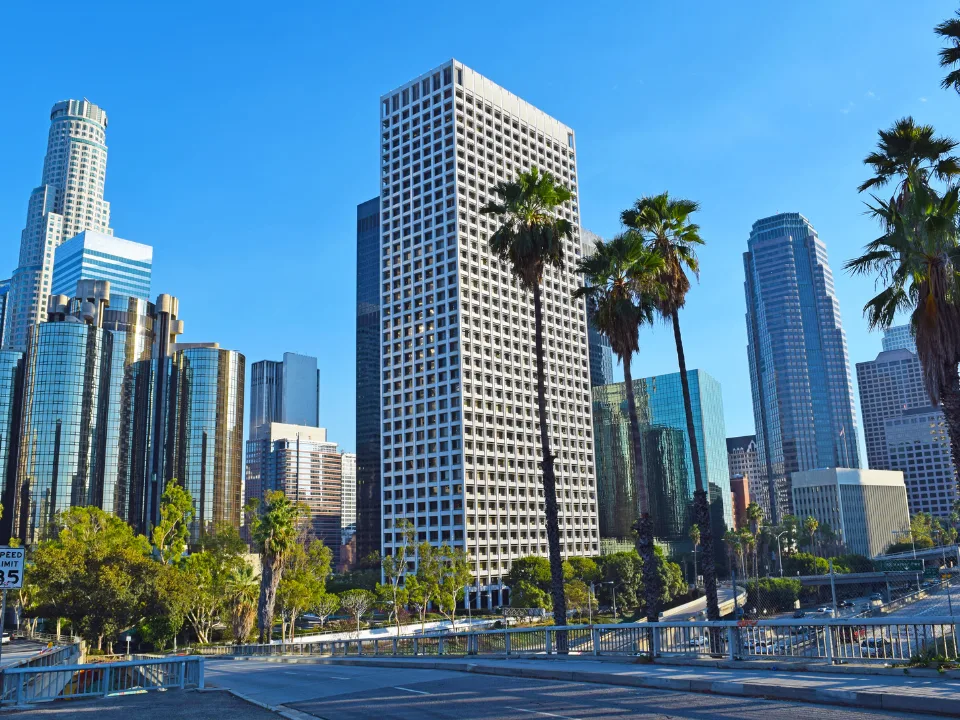
Brookfield is giving up the $600 million Beaudry tower in downtown Los Angeles, The Wall Street Journal reports, choosing to hand it back instead of refinancing the building’s debt.
The 695-foot, 785-unit tower opened in April 2023. Sources told the Journal that refinancing its roughly $360 million loan at current rates would have meant tens of millions in extra costs.
Get Smarter about what matters in CRE
Stay ahead of trends in commercial real estate with CRE Daily – the free newsletter delivering everything you need to start your day in just 5-minutes
Debt Ate the Equity
Brokers told the Journal that debt costs have erased Brookfield’s equity. Lender Bridge Investment Group, which Apollo owns, is now trying to sell the loan.
Newmark vice chairman Dean Zander told the Journal the tower was meant to be a hit, but that the debt market “got away.”
A Downtown Still Healing
A Brookfield spokeswoman said the move reflects entrenched challenges downtown, where office vacancy is still about double 2019 levels and apartment rents have only just returned to pre-pandemic levels.
The Beaudry is about 95% occupied at asking rents around $4,200, per CoStar, and, like many downtown landlords, Brookfield has offered weeks of free rent.
Brookfield has also defaulted on loans on commercial properties nearby, in the same fund, which is near the end of its holding period.
Zoom Out
Multifamily debt stress isn’t limited to L.A. Our brief on Blackstone’s $1.3B loan covered an apartment CMBS loan that moved to special servicing after maturing in October, with $517.7 million still owed and six of the original 21 properties left to sell.
The Journal cites a Morgan Stanley report showing multifamily CMBS delinquencies at 7.1% this year, the sharpest climb of any major property type.
Why It Matters
Roughly $1.8 trillion of landlord debt matures over the coming decade, with close to half due by 2028, and many owners are refinancing at more than double their original borrowing costs.
Downtown L.A. also has a long recovery ahead. From 2017 to 2021 it built more than 10,000 apartments, the most of any U.S. downtown, per RentCafe. Our brief on Graffiti Towers covered Oceanwide Plaza’s court-approved sale for about $517 million, plus roughly $800 million to finish it.
What’s Next
Brookfield says it is still buying, having picked up a 2,149-unit San Francisco apartment loan portfolio at a deep discount in 2024. It expects to add more as rivals give up troubled properties.