




- At least 18 data center financings in high-yield bond and leveraged loan markets carry double-digit yields, and a $5B loan for neocloud Volta priced above 11% after banks sweetened terms.
- Investors fear contract off-ramps, banks are nearing lending limits and insurers are close to their data center caps, so passing risk to other investors can take around five months.
- Data center ABS and CMBS issuance is only about $22B this year, barely above 2025, as top-rated bond yields rose from under 5% to near 7%.
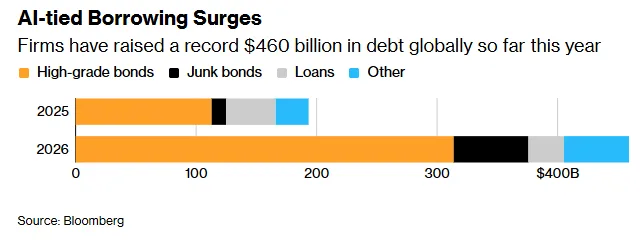
Wall Street’s appetite for AI infrastructure debt is starting to fade, Bloomberg reported in an exclusive, as yields on data center bonds and loans climb into double digits.
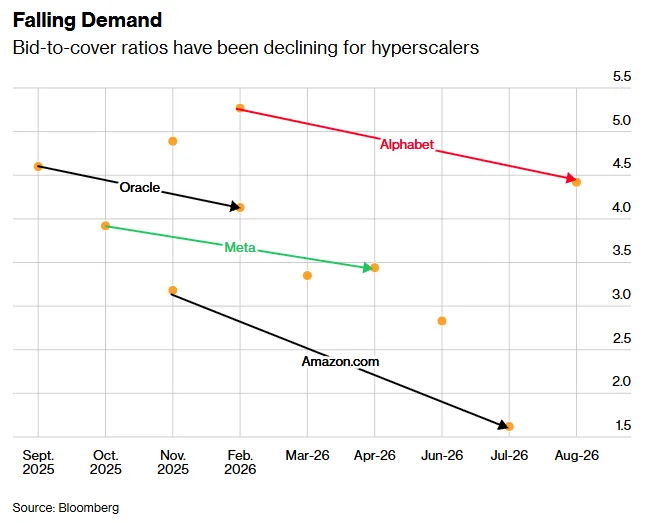
Bloomberg counts at least 18 data center deals in high-yield debt, both bonds and leveraged loans, priced at double-digit yields. Bankers say insurers and other buyers are less willing to take risk off their books.
Get Smarter about what matters in CRE
Stay ahead of trends in commercial real estate with CRE Daily – the free newsletter delivering everything you need to start your day in just 5-minutes
Pricing Is Slipping
To fill Volta Infrastructure’s $5 billion syndicated loan, JPMorgan and Goldman Sachs sweetened the discount and interest rate, lifting the yield above 11%. Volta is a neocloud, a newer type of AI computing provider.
Carolyn Campbell, an ABS strategist at Morgan Stanley, noted on a podcast this month that the best-rated data center bonds started 2026 yielding under 5% and now yield near 7%. Issuing becomes much tougher as yields approach 8%, she said.
Combined ABS and CMBS data center issuance is about $22 billion this year, little changed from 2025.
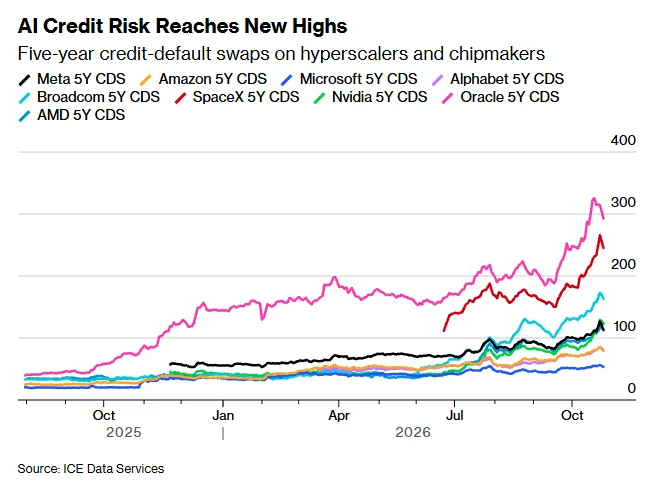
Credit default swaps are flashing warnings too. Insurance on Oracle debt reached a record last week, along with SpaceX, Nvidia and Meta. Bloomberg’s investment-grade tech bond index yields around 6%, 1.4 points more than a year ago.
Contract Off-Ramps Worry Lenders
Bloomberg interviewed over 30 people across banking, asset management and private equity. Each said raising capital has become far harder in recent months.
Exit rights are the sticking point. One hedge fund walked away from a deal when it learned the tenant could cancel after a delay of more than three months, and lawyers at a leading firm have seen agreements allowing customers to leave after delays of 180 days or longer.
Anxiety rose after Oracle invoked force majeure last month to seek deferred payments if a big New Mexico data center runs late.
Lenders Near Their Limits
A senior technology, media and telecom lender at a large European bank told Bloomberg the firm is close to maxing out its exposure, and that offloading the risk takes about five months, which slows new loans.
Insurers flagged similar limits months ago, based on a Willis Towers Watson survey. KKR is steering clear of remote sites that could be hard to re-lease, Bloomberg reported, citing a person familiar, and Carlyle has passed on several transactions.
The squeeze matters to developers hunting for money. CRE Daily reported that Soar AI lined up a facility to sell up to $1 billion of stock to fund converting existing industrial buildings into AI infrastructure and data center campuses.
Citadel’s Warning
Citadel Securities is warning clients that even the largest tech companies could be pulled in as they guarantee or backstop many projects. It isn’t forecasting a credit crunch, and big tech still raised tens of billions this week.
The worry is a mismatch among what executives expect to raise, what banks can underwrite and what investors will hold. Citadel’s Tucker Roberts said the hard part may soon be finding buyers for the risk, not an investment-grade guarantor.
Diameter Capital Partners told investors that tech may be ‘too complacent’ about debt supply for a $5.5 trillion buildout, and Oaktree co-CEO Armen Panossian said the firm is ‘very, very cautious’ about deal structure and asset quality.
Why It Matters
Data center debt is a fast-growing corner of CRE credit, and its pricing is moving quickly. Costlier capital and fewer buyers raise hurdles for developers, who will face tougher questions on site and lease terms.
The caution extends to service providers. CRE Daily reported that CBRE’s Onnec deal, valued at up to $1 billion, takes the largest CRE services firm deeper into data center equipment as the industry bets on AI spending.
What’s Next
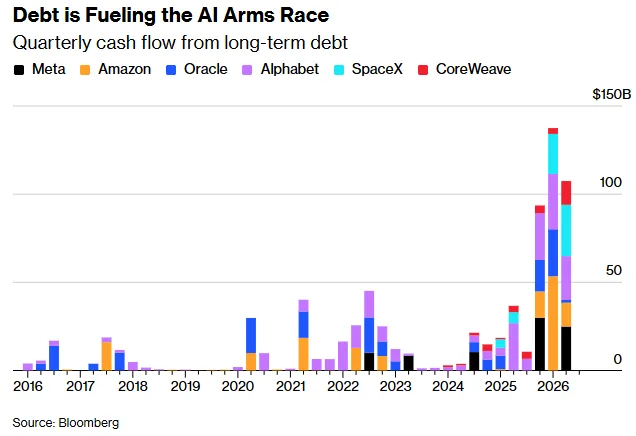
Credit could reopen even for speculative projects if hyperscaler earnings keep pace with their heavy up-front spending, Bloomberg noted. Until then, lenders are picking spots more carefully and charging more.
Weak demand for recent offerings from AI infrastructure firms Elice, Firmus Grid and Nscale points the same way.