



- AAA bonds in 19 data center SASB deals widened 21 bps (fixed) and 24 bps (floating) in the week ending Oct. 23, as other SASB and conduit bonds held flat.
- Since year-end, fixed-rate data center AAAs are 60 bps wider and floaters 32 bps wider, against 1 and 7 bps for other SASB deals and none for conduit.
- The move reflects investors repricing sector exposure, not property distress: every loan behind these deals is current and none sits with a special servicer.
Senior tranches of data center CMBS widened by 21 to 24 basis points in the week ended Oct. 23 while comparable bonds in other deals barely moved, Trepp reports.
A stock sell-off tied to AI worries didn’t start the repricing, but it pushed it into a higher gear.
Get Smarter about what matters in CRE
Stay ahead of trends in commercial real estate with CRE Daily – the free newsletter delivering everything you need to start your day in just 5-minutes
What Set It Off
Oct. 22 was a hard day for AI-linked assets. Chip stocks dropped, with the PHLX Semiconductor Index down 6.7%, and CoreWeave fell after a Bernstein downgrade and doubts over how it will fund growth.
Money rushed into Treasuries. The 10-year yield dropped to 4.96%, down 17 basis points, the sharpest one-day decline since March 2023. A few CoreWeave bonds have changed hands at yields of 15% or more.
Morgan Stanley strategists expect data center ABS spreads to widen further, and Trepp’s CMBS pricing is moving the same way.
By the Numbers
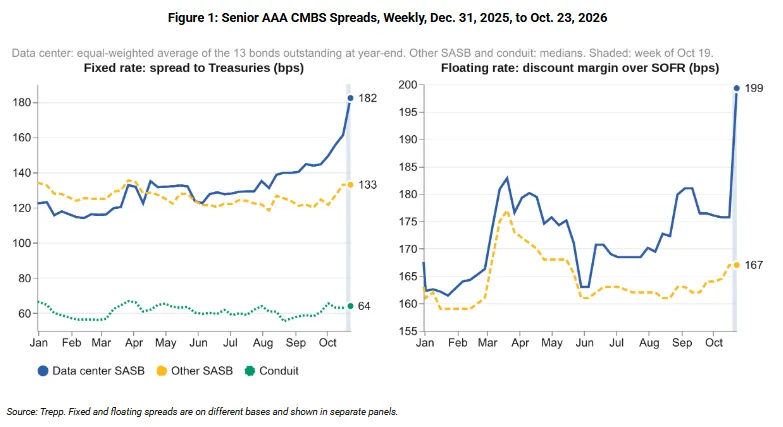
Trepp looked at 19 single-asset, single-borrower deals backed by data centers. Fixed-rate AAA bonds moved out 21 basis points that week to trade 182 over Treasuries, while floating-rate AAAs gained 24 basis points to sit 199 over SOFR.
Median bonds in other SASB and conduit deals held steady. Measured from year-end, data center fixed-rate AAAs have widened 60 basis points and floaters 32, versus 1 and 7 for other SASB and nothing for conduit.
The slide predates the sell-off. Fixed-rate data center spreads sat at 128 basis points in late June and reached 161 by Oct. 16, while the typical other-SASB bond went from 122 to 133.
Oct. 21 alone saw 39 of 88 rated data center bonds marked wider.
The Widest Names
VDCM 2025-AZ leads the fixed-rate group: its class A spread has grown by 85 basis points, to 205, and the bond is priced at 94.6. The biggest floater move is CONE 2024-DFW1, out 71 basis points. SWCH 2025-DATA, whose class A totals $1.16 billion, moved the same 71 in just the last week, to 243.
Newer deals are also wider. BODI 2026-DC1 is out 47 basis points, and CONE 2026-DFW3, which priced in May, has widened 61 since its first mark. Blackstone’s floaters are the outliers, with BX 2025-VLT7 only 2 basis points wider and BX 2025-VLT6 15.
The Top of the Stack Tells the Story
Pressure reaches higher-rated bonds too. Data center AA bonds have moved 76 basis points and single-As 105, compared with moves under three basis points for matching ratings elsewhere in SASB. Of 64 data center bonds rated at the start of the year, 60 are wider now.
Trepp reads this as a repricing of sector exposure, not a call on any specific property: all loans are current, and none has gone to special servicing. That contrasts with CMBS overall, where CRE Daily reported the special servicing rate reached 11.49%, the highest since 2013.
Why It Matters
Investors want more yield for data center risk even with every loan performing, which raises pricing on new deals in the sector.
The bonds also trade on AI sentiment. The sell-off that hit chip stocks and CoreWeave showed up in CMBS pricing within days.
What’s Next
The question is whether these marks stick or ease as equities calm, as happened after March. Floating-rate spreads peaked at 183 basis points then and had returned to 176 by mid-October.