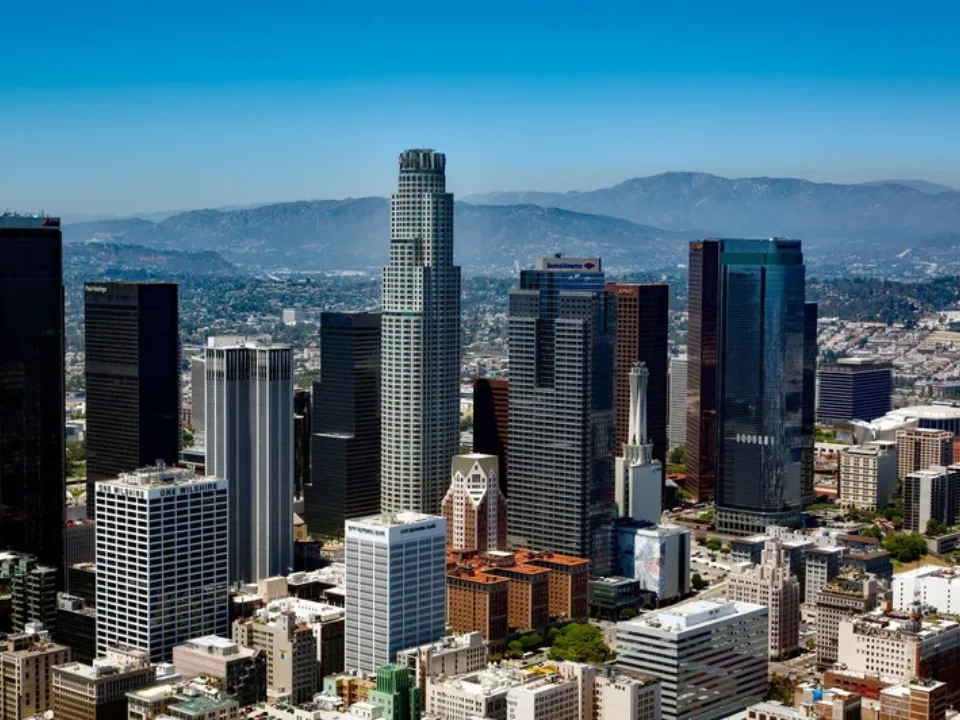



- Colliers data show Los Angeles County apartment sales of 50-plus-unit properties reached $3.3B through Q3, up 44% year over year, with the average price falling to $357,085 per unit.
- Occupancy held at 94.1% and average effective rent rose just $6 to $2,428, matching its level a year earlier, as developers added 4,277 units in the quarter.
- The pipeline fell to 23,426 units from 25,421 a year ago, and submarkets diverge sharply, from 96.6% occupancy in South L.A. to 91.7% downtown.
Investors are buying more Los Angeles apartments, but renters are not paying more, Commercial Observer reports from Colliers’ latest market data.
Deals for buildings of 50-plus units totaled $3.3 billion so far this year, up 44% on the same period of 2025. The average price slipped to $357,085 per unit.
Get Smarter about what matters in CRE
Stay ahead of trends in commercial real estate with CRE Daily – the free newsletter delivering everything you need to start your day in just 5-minutes
Flat Rent, Flat Occupancy
Third-quarter occupancy was 94.1%, flat on the prior quarter and a touch below last year’s 94.4%. Monthly effective rent edged up $6 to $2,428 a unit, which simply matches where it stood twelve months ago.
Colliers ties both numbers partly to new supply.
Supply Is Easing
Developers delivered an estimated 4,277 units in the third quarter, about 72% more than in the second. Tenants absorbed 3,809 units, a big step up from 2,429 in Q2, and a year ago the figure was 2,360.
The pipeline is thinning, though: 23,426 units were under construction at quarter-end, versus 24,877 three months earlier and 25,421 twelve months ago. Since mid-2021, the county has added over 58,800 apartments.
Submarkets Split
The Westside remains the priciest area at $3,336 a month in effective rent, yet occupancy is only 92.9%. It also carries the biggest pipeline, 5,894 units in progress.
Hollywood and Mid-Wilshire averaged $2,355 with 92% occupancy and led deliveries at 1,869 units, with another 5,113 underway. Downtown and Central L.A. had the lowest occupancy at 91.7%, though that is up 1.1 points from a year ago.
South L.A. had the tightest market at 96.6% occupancy and $1,996 rents, followed by the South Bay at 95.8% and $2,436.
Why It Matters
Buyers are returning at lower per-unit prices while landlords still lack pricing power. That fits the national picture, where multifamily starts fell 25.9% year over year in September, a sign fewer new apartments are on the way.
Local supply will decide who benefits. Submarkets with big pipelines, like the Westside and Hollywood, still have space to absorb.
What’s Next
A shrinking pipeline should help occupancy over time, but financing could limit the pace. CRED iQ recently estimated that a $6.8B refinance gap exists across maturing apartment debt after September’s rate hike.