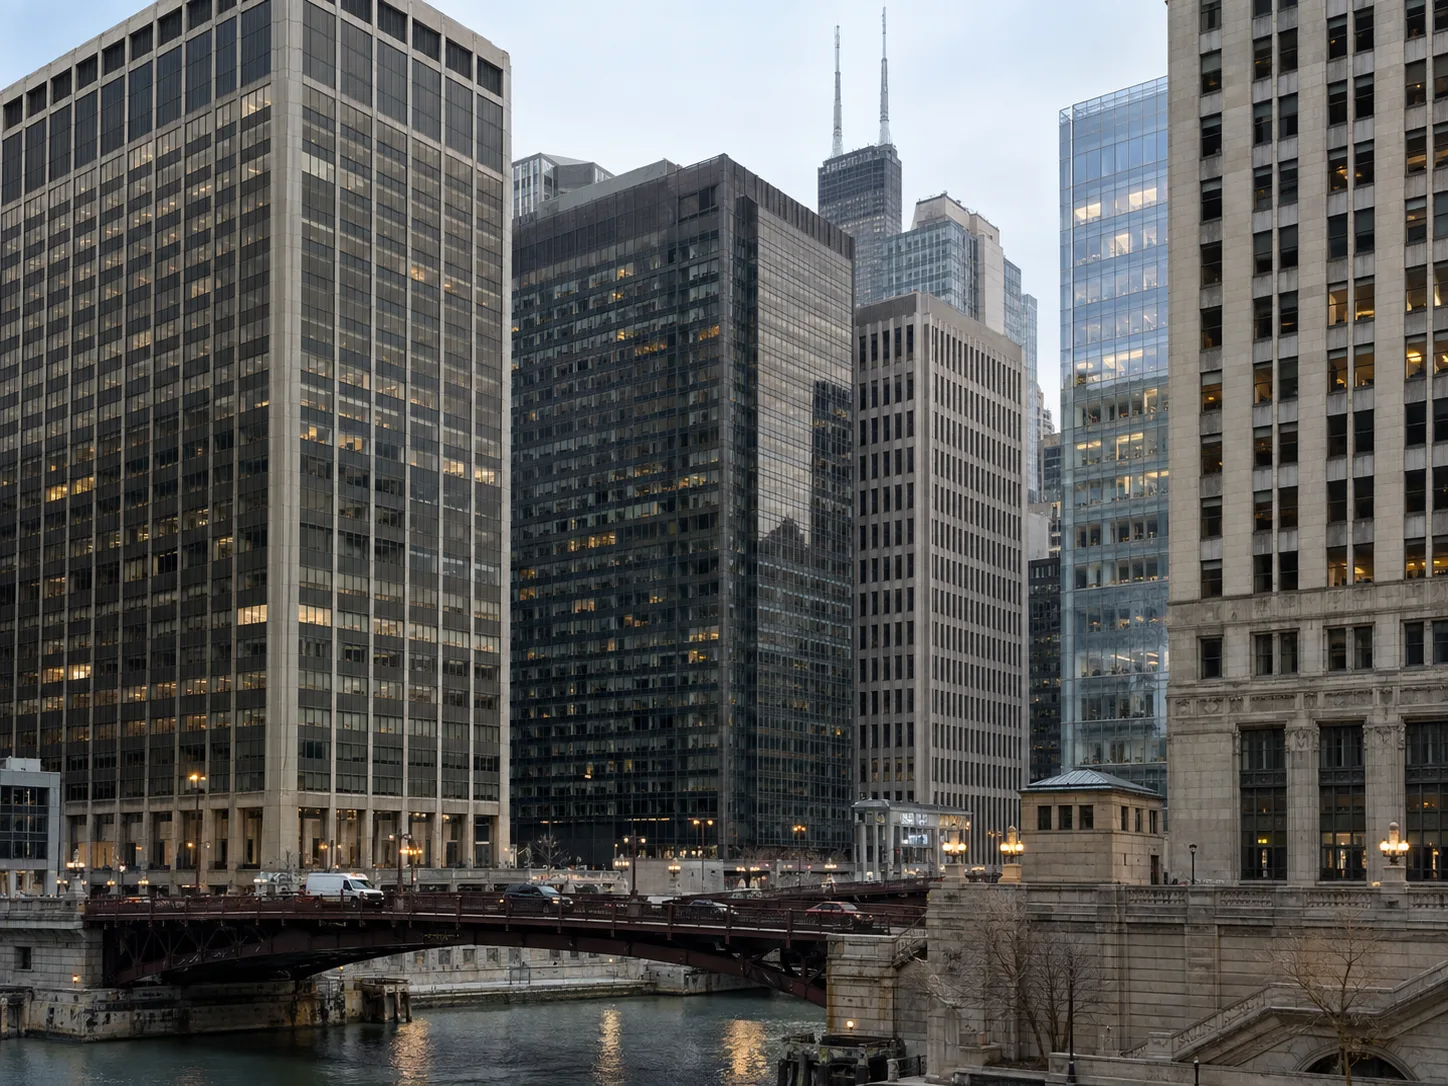




- Office-backed CMBS saw signs of recovery in early 2025, with office properties accounting for over one-third of new issuance in Q1.
- Despite improving credit quality, office loans remain the most distressed property type, and refinancing risk looms as loans from the low-rate era mature.rn
- The shift toward recapitalizations and newer buildings marks an evolution in office CMBS as lenders adapt to a changed market environment.rn
Office Loans Dominate Distress Metrics
Even as broader CMBS markets show signs of stabilization, office-backed loans continue to struggle, reports GlobeSt. A March 2025 CRED iQ report highlighted that distress remains highest in the office sector, a trend that has persisted into the second quarter despite a decline in distress across multifamily, lodging, and retail-backed securities.
A Complex Backdrop
Office assets were historically a mainstay in CMBS, accounting for about 25% of issuance between 2012 and 2019. That share grew to 33% during the pandemic, as lenders pivoted away from retail and hotels. However, the maturity of short-term, low-interest loans issued during the 2021-2022 window now threatens asset performance as refinancing becomes more expensive due to rising rates and economic uncertainty.
Get Smarter about what matters in CRE
Stay ahead of trends in commercial real estate with CRE Daily – the free newsletter delivering everything you need to start your day in just 5-minutes
Signs Of Life, But Caution Persists
In Q1 2025, 36.4% of newly originated CMBS deals were backed by office properties—offering a tentative sign of renewed lender interest. However, that momentum has not held, with remote and hybrid work continuing to impact demand and valuation fundamentals. Still, office-backed conduit cmbs issuance ticked up slightly to 16.3% in Q1, a modest increase from previous periods.
Geography And Quality Take Center Stage
Office CMBS exposure has become more concentrated in Tier 1 markets, with New York and Los Angeles leading issuance in 2025. San Francisco, long a tech and office stronghold, has seen its share fall due to ongoing remote work adoption. Meanwhile, properties built after 2000 now represent nearly 50% of new office CMBS assets—double the historical average—highlighting a growing preference for modern buildings.
Shift In Deal Structure
Acquisitions, once a staple of office CMBS transactions, now represent a much smaller portion of the market. Recapitalizations have surged in their place as property owners seek to refinance amid a high-rate environment and lenders attempt to reposition troubled assets.
Outlook
While structural adjustments and improving credit metrics provide a degree of optimism, uncertainty remains high. Rising interest rates, refinancing risks, and changes in office utilization patterns will continue to shape the outlook for office-backed CMBS through the remainder of 2025.