


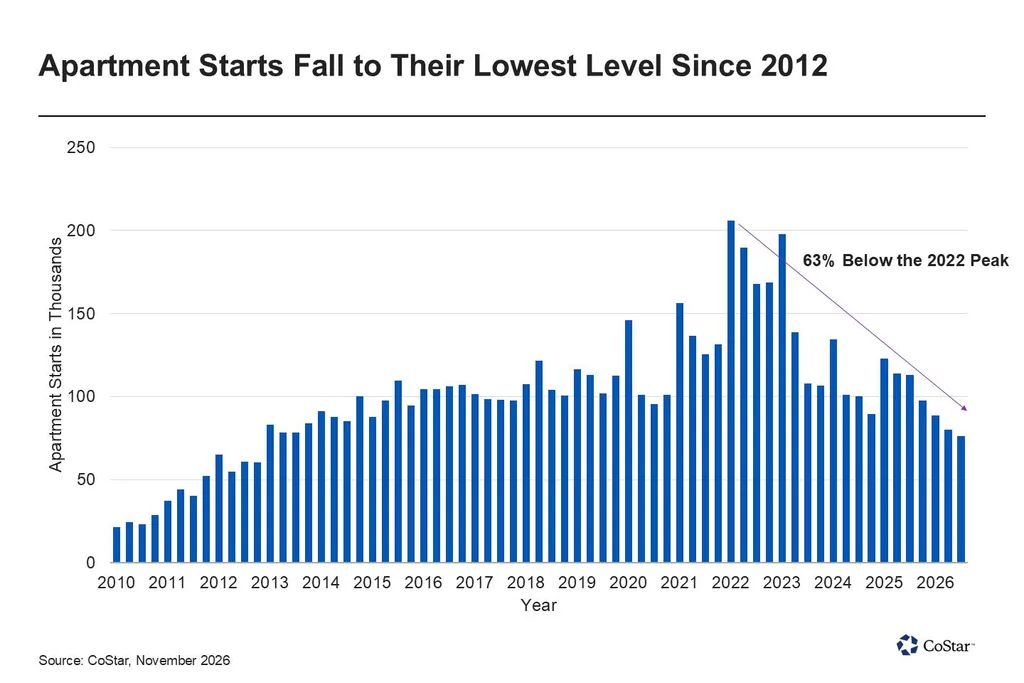
- About 76,000 apartment units started construction in Q3 2026, down 63% from the Q1 2022 peak of nearly 206,000 and the lowest quarterly total since 2012.
- About 593,000 units are under construction, half the early 2023 peak and the 14th straight quarterly decline, while deliveries over four quarters totaled 446,000, down 22% from a year earlier.
- Starts across Dallas-Fort Worth, Houston, Austin and San Antonio are down about 42% year over year, pointing to a much thinner supply wave after the building boom.
U.S. apartment starts dropped to roughly 76K units in Q3 2026, the weakest quarter since 2012, Apartments.com reports.
That is 63% under the Q1 2022 high of nearly 206K.
Get Smarter about what matters in CRE
Stay ahead of trends in commercial real estate with CRE Daily – the free newsletter delivering everything you need to start your day in just 5-minutes
The Pullback in Numbers
Builders began about 342K units over the last 12 months, the slowest yearly clip since 2014 and only about three-quarters of what finished construction.
Completions are cooling as well. About 446K units opened across the trailing four quarters, a 22% drop from the prior year and 36% under the 2024 high.
The Pipeline Keeps Shrinking
Roughly 593K units are under construction, about half the early-2023 high of nearly 1.2M. This is the 14th consecutive quarterly decline, and the total is back where it stood in mid-2016.
CoStar’s Grant Montgomery, who directs U.S. multifamily analytics, said developers are starting far fewer projects than they complete, and that gap is reshaping supply market by market. He said the wave of deliveries is fading into a thinner pipeline wherever starts fell furthest.
Where Construction Is Concentrated
New York leads in pipeline size with about 46K units, ahead of Dallas-Fort Worth’s 32K or so.
Against current inventory, Miami has the most in the works, near 9% of its stock. Charlotte and Fort Lauderdale both exceed 6%.
Texas Pulls Back Hardest
Three of the six busiest start markets at the boom’s height were in Texas, and the state is now pulling back hardest. Over the last 12 months, starts in Dallas-Fort Worth, Houston, Austin and San Antonio together dropped around 42% against the prior year.
Why It Matters
Less new supply gives existing owners room to fill buildings. Colliers data we covered put Q3 occupancy at 95.7%, with units under construction down 6% in one quarter to about 504,000. That is a different count from CoStar’s 593,000, so the levels differ even though both show a retreat.
Not every signal points down. CoStar’s October starts figure jumped 25.5% to a 433,000 annual rate, though the analysts we cited warned against reading much into it, since permits for buildings with five or more units slid 5.2%.
What’s Next
Watch whether the thinner pipeline firms up rents in the markets where starts have fallen furthest, especially across Texas. Lender caution and high construction costs would keep developers cautious into 2027.