


- Altus Group’s Adam Mauro argues U-Haul migration is a supply signal: heavy in-migration draws developers, whose new facilities depress rate growth for years in the same markets.
- From 2021 to 2024, the strongest in-migration states captured roughly 38% of U.S. self-storage acquisitions, concentrating capital where oversupply followed.
- Owners in high-migration markets should push rates now before deliveries arrive, while buyers should wait, since new supply is forecast down 19% in 2026.
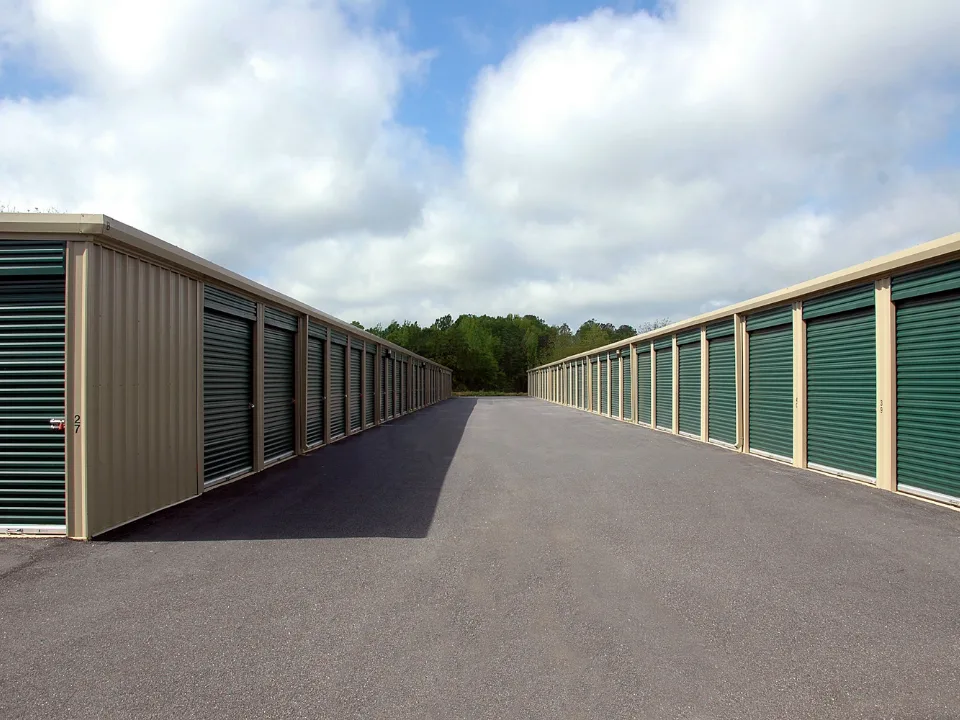
U-Haul migration data is usually read as a demand signal for self-storage, but it is better understood as a supply signal, according to Adam Mauro of Altus Group.
The markets absorbing the most migration end up with the weakest rental rate growth for years, he writes, while markets people are leaving have delivered the best storage returns since late 2024.
Get Smarter about what matters in CRE
Stay ahead of trends in commercial real estate with CRE Daily – the free newsletter delivering everything you need to start your day in just 5-minutes
Where Migration Meets Overbuilding
Migration lifts demand within a year, but it also draws developers. High-migration states such as Texas and Florida lead in residential building permits, and storage follows housing.
Between 2021 and 2024, the strongest in-migration states captured about 38% of U.S. self-storage acquisition activity. Capital landed where oversupply was about to follow.
Phoenix as the Case Study
Phoenix market rents rose about 19% from Q3 2021 to Q3 2022, then returned to pre-boom levels as its pipeline delivered. Houston, Dallas and Atlanta showed a similar pattern, posting the weakest realized rent growth among major metros over two years.
The Development Clock
Altus lays out a predictable sequence. Demand spikes within one year of a migration surge, and storage takes 18 to 36 months to build. Rates then bottom in the second and third years after completion, and markets recover only after three to four years, once absorption catches up.
That timeline is why supply slowdowns matter more to investors than migration headlines.
What Owners and Buyers Should Do
For current owners, Mauro says the window to push rate is now, while pricing power is still intact. He recommends locking in existing tenants before new deliveries hit.
For buyers, strong migration signals argue for waiting. Buying at a migration peak means buying on top of the development cycle.
Why It Matters
The argument cuts against a common underwriting shortcut. Operators and lenders who treat migration as a green light may be pricing in demand that new supply will absorb, a concern that overlaps with the refinancing risk in the sector.
What’s Next
Austin shows the clearest signs of turning, with its pipeline easing and rate growth approaching breakeven. Phoenix remains mid-correction, with a pipeline equal to 6.9% of stock.
The national new-supply forecast for 2026 is down 19% year over year, which Altus calls the first sign that migration-winner markets are approaching recovery.