
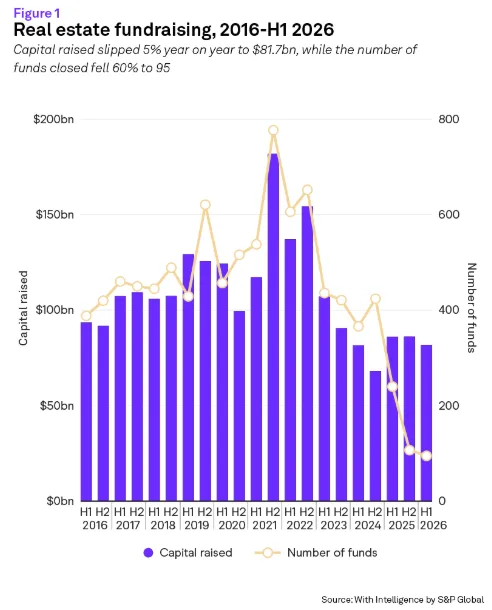
- Closed-end real estate funds raised $81.7B in H1 2026, down 5% year over year, while the number of funds reaching final close fell 60% to 95.
- The 10 largest funds captured 49% of capital raised, established managers took 59%, and first-time vehicles drew only 17% as LPs leaned on track record.
- Allocators keep favoring non-core strategies at 70% of H1 intentions, while open-end core funds and European debt managers face redemption queues and a widening gap between large and small sponsors.
Closed-end real estate fundraising reached $81.7B in the first half of 2026, the third-lowest half-year total in more than a decade, according to With Intelligence by S&P Global. Only the two halves of 2024 were weaker.
Just 95 funds reached final close, down 60% from a year earlier, even though total capital slipped only 5%.
Get Smarter about what matters in CRE
Stay ahead of trends in commercial real estate with CRE Daily – the free newsletter delivering everything you need to start your day in just 5-minutes
Capital Concentrates at the Top
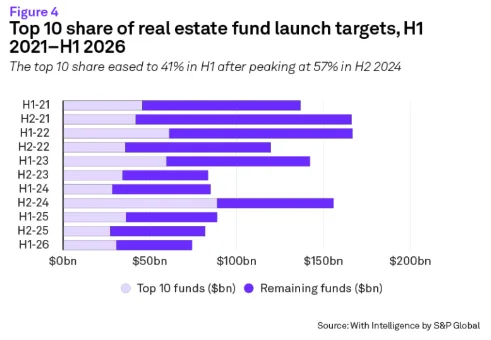
The 10 largest funds accounted for 49% of capital raised, and the top 20 took 69%. Established managers on Fund IV or later raised $48B, or 59% of the total, versus $19B for emerging managers and $14B for first-time funds.
Only two of the 20 largest closings were first-time funds: Digital Realty’s US Hyperscale Data Center Fund and Core Spaces’ Student Housing Fund. That points to strong LP appetite for those sectors.
Launch Targets Fall to a 2017 Low
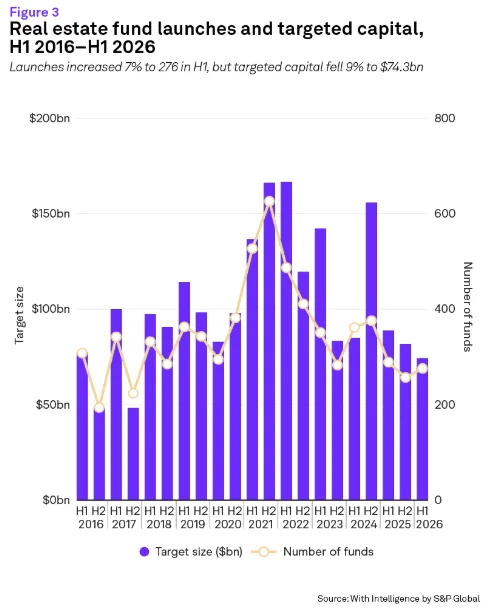
Managers launched 276 funds in H1, up 7%, but their combined $74.3B target fell 9% to the lowest level since 2017. Value-add and opportunistic strategies account for 78% of that target, and diversified strategies represent 48%.
The largest launches came from EQT Exeter’s industrial fund, Aermont’s flagship vehicle and Ares Management’s new real estate secondaries fund.
Non-Core Wins the Allocator Vote
Investor intentions peaked at 398 in Q1 before dropping 25% to 300 in Q2. Non-core strategies made up 70% of H1 intentions, and CalPERS said in June it plans to double the non-core share of its real estate portfolio by 2030.
Data centers remain popular, though New Jersey’s Division of Investment CIO Shoaib Khan told With Intelligence in May that the pension is wary of over-committing. Senior housing specialists are also drawing interest, and the broader shift mirrors how alts fundraising is tilting toward hard assets.
U.S. public pensions dominated the mandate rankings, and U.S. institutions held nine of the top 10 spots. Florida’s State Board of Administration led with 16 mandates, followed by CalSTRS with 11.
Core Funds and European Debt Under Pressure
Redemption queues eased at three of five tracked open-end core funds in Q1. UBS’s Trumbull Property Fund fell to 37% of NAV from 50% but still sits at roughly double the 18% queue at Invesco Core Real Estate.
In Europe, 46 debt funds launched since 2022 target a combined EUR 57B, and the 12 vehicles aiming for EUR 1B or more account for 73%. Brookfield’s EUR 18B BSREP V and Blackstone’s EUR 8B BREDS V alone make up 46%.
Smaller managers are struggling. Catella froze two EUR 500M funds, Niam dropped its debut Nordic debt fund, and several firms cited weak German LP demand.
Core managers have rotated out of office toward healthcare real estate, student housing, parts of retail and data centers. JPMorgan’s Strategic Property Fund queue fell to 7% from 11%, Morgan Stanley’s Prime Property Fund held at 6%, and Intercontinental’s fund dropped to 5.9% from 10.9%.
European equity fundraising recovered somewhat, with $14.8B raised in H1.
Why It Matters
Private wealth is filling part of the gap. The top 10 private REITs hold $95.6B of NAV, with BREIT at $57B, or 60% of the group.
Blue Owl’s net lease trust, at $9.3B, has passed Starwood’s SREIT at $7.9B for second place. Starwood suspended redemptions, and 71% of its portfolio value sits in Sunbelt multifamily where rents have stalled.
What’s Next
With Intelligence ties the slowdown to inflation and rate uncertainty after the February U.S. and Israeli strikes on Iran. Watch whether the Q2 dip in allocator intentions carries into H2 and whether first-time managers can break through.