





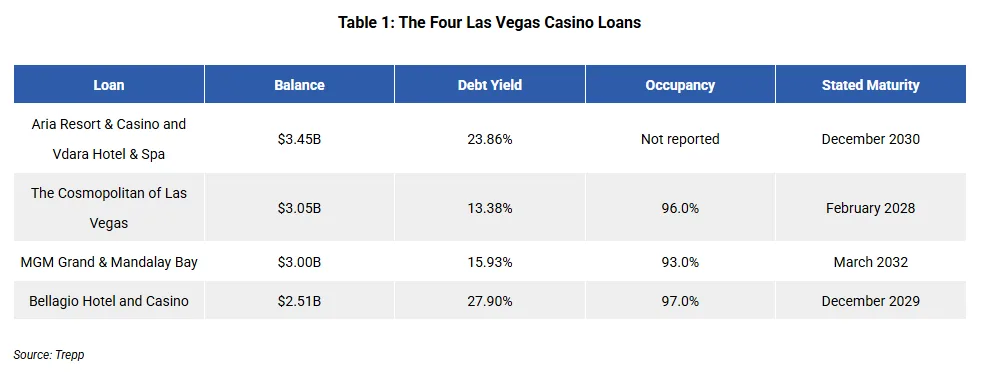
- Four Las Vegas casino resort loans totaling $12.01B, about 13% of securitized lodging, hold the median cash flow change at -1.7% since underwriting; without them it is -8.1%.
- All four pay on time, with debt yields of 13.38% to 27.90% versus the 11.99% sector median, and gaming and entertainment income sets them apart from ordinary hotel loans.
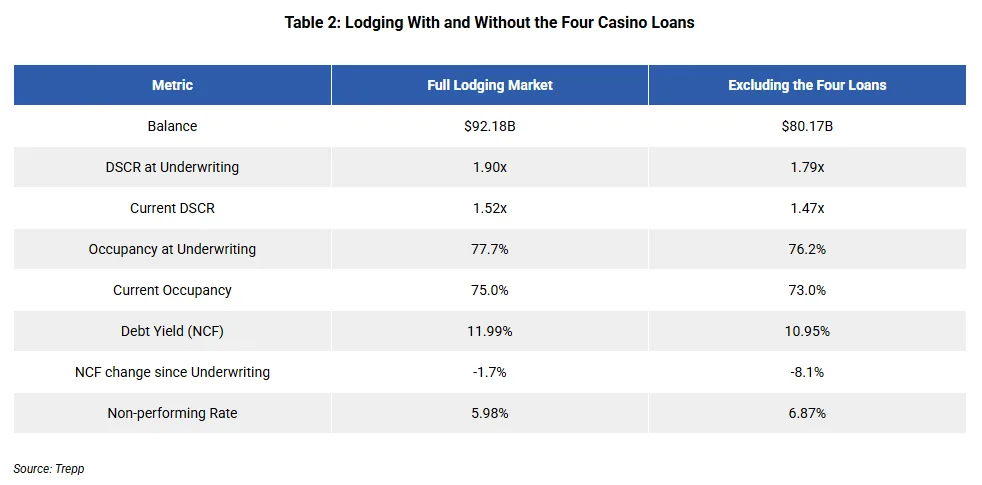
- Removing them lowers median underwriting DSCR to 1.79x from 1.90x and debt yield to 10.95%, and lifts the nonperforming rate to 6.87% from 5.98%.
A handful of Las Vegas casino loans is flattering the cash flow picture for CMBS lodging, according to Trepp’s analysis.
Securitized lodging carries $92.18B in loans, and its balance-weighted median net cash flow is 1.7% under the level assumed at underwriting. Strip out four casino-resort loans and the typical shortfall is 8.1%.
Get Smarter about what matters in CRE
Stay ahead of trends in commercial real estate with CRE Daily – the free newsletter delivering everything you need to start your day in just 5-minutes
The Four Loans
Together the four carry $12.01B, or 13.0% of the sector’s balance. Since the statistics are weighted by balance, positions that large tilt the national figures.
Resorts like these earn money from gaming, entertainment and dining as well as rooms, so their economics are unlike ordinary hotels. Each loan is paying on time, with debt yields between 13.38% and 27.90% against an 11.99% sector median.
Two lack updated numbers. The Cosmopolitan loan, from February 2026, and the Aria and Vdara loan, from December 2025, have no post-securitization financials yet, so Trepp used securitization-era cash flow for their yields.
What Changes Without Them
Without the casinos, median DSCR at underwriting slides from 1.90x to 1.79x and median debt yield from 11.99% to 10.95%.
Performance shifts more. The median loan trails underwritten cash flow by 8.1% instead of 1.7%, and the nonperforming rate climbs from 5.98% to 6.87%.
Why Casinos Are Different
Trepp describes the four as big, well covered and current, and says they do not represent either the wider Las Vegas hotel market or lodging nationally. Their scale and strong coverage pull sector averages upward.
Why It Matters
National lodging numbers can mislead when a few mega-loans dominate the balance. Beneath the headline, the typical loan is much further behind its underwriting, which fits other signs of stress such as limited-service hotels leading CMBS lodging stress.
Brand matters too, as Hilton hotel CMBS distress has outpaced Marriott’s.
What’s Next
Watch for the first post-securitization financials on the Cosmopolitan and Aria and Vdara loans, which will replace the securitization-based debt yields.