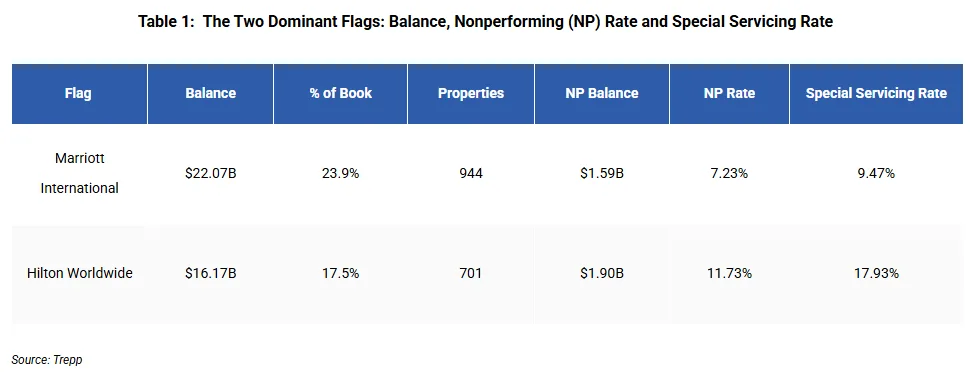
- Hilton-flagged CMBS hotel loans are nonperforming at 11.73%, versus 7.23% for Marriott, with 17.93% of Hilton’s balance in special servicing.
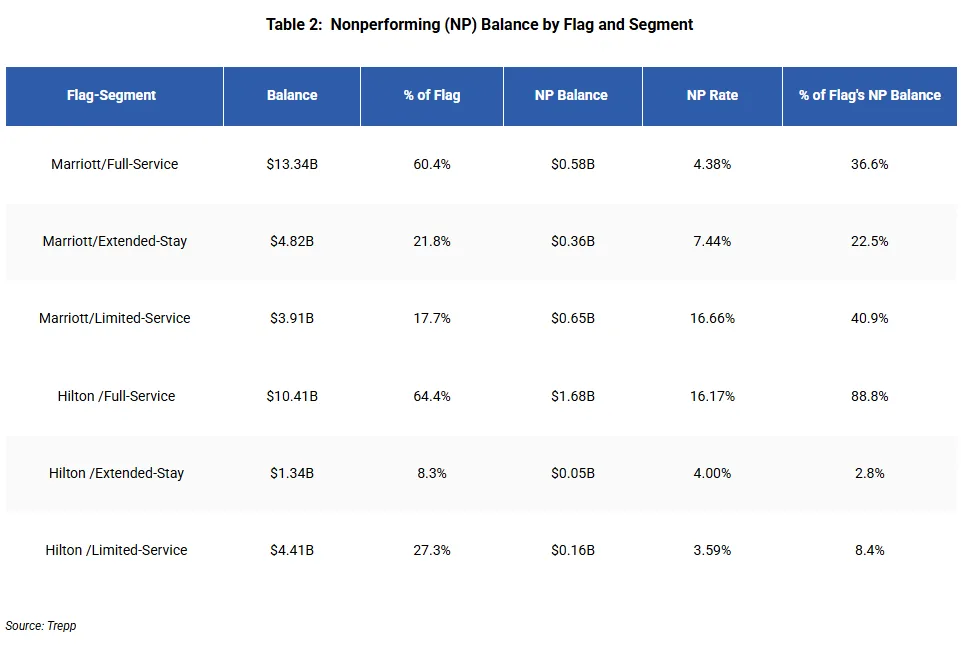
- Full-service hotels account for 88.8% of Hilton’s nonperforming balance, led by the $328.9M Palmer House Hilton loan now in foreclosure in Chicago.
- Brand-level delinquency rates reflect a few large loans more than franchise quality, making loan-level analysis essential for gauging hotel CMBS exposure.
Securitized Hilton-flagged hotel loans are nonperforming at 11.73%, well above the 7.23% rate for Marriott-flagged loans, according to Trepp. The firm traced the gap to a handful of large full-service hotel CMBS loans rather than to Hilton’s book as a whole.
Get Smarter about what matters in CRE
Stay ahead of trends in commercial real estate with CRE Daily – the free newsletter delivering everything you need to start your day in just 5-minutes
Two Flags Dominate Securitized Lodging
Marriott International and Hilton Worldwide are the two largest flags in securitized lodging, franchising a combined $38.24B, or 41.5% of the $92.18B sector, per Trepp.
Marriott carries $22.07B across 944 properties, while Hilton has $16.17B across 701. Yet Hilton’s nonperforming balance of $1.90B exceeds Marriott’s $1.59B.
The Details
Special servicing shows the same split: 17.93% of Hilton-flagged balance sits with special servicers, versus 9.47% for Marriott.
Full-service hotels account for 88.8% of Hilton’s nonperforming balance, with a 16.17% nonperforming rate, more than three and a half times Marriott’s 4.38% full-service rate. Hilton’s limited-service loans, by contrast, are its best performers at 3.59%, compared with 16.66% for Marriott’s limited-service book.
Hilton actually carries a larger limited-service share, 27.3% of its flagged balance versus 17.7% for Marriott, so segment mix doesn’t explain its higher rate. Marriott’s nonperforming balance is spread more evenly, with 40.9% in limited service, 36.6% in full service and 22.5% in extended stay.
One Chicago Hotel Skews the Hotel CMBS Numbers
Chicago accounts for $491.3M of Hilton’s nonperforming balance, most of it tied to Palmer House Hilton. The full-service hotel, securitized in 2018, is in foreclosure on a $328.9M balance, and a related $94.3M mezzanine loan is a nonperforming matured balloon.
Together they total $423.2M, or 86.1% of Hilton’s Chicago nonperforming balance. Occupancy is steady at 82.0%, but the senior loan’s debt service coverage ratio has fallen to 1.04x from 2.49x at securitization, and Hilton Suites Chicago Magnificent Mile, now real estate owned at $64.4M, makes up most of the rest.
That cuts against the broader pattern of limited-service hotels leading CMBS lodging stress, which still holds for Marriott.
Why It Matters
Trepp’s analysis suggests flag-level delinquency rates say more about a few specific loans than about brand strength or segment mix. Judging hotel CMBS exposure by brand alone could miss concentrated risk in individual large loans.
Lodging stress also sits within a broader CMBS delinquency picture where office risk is rising.
What’s Next
The Palmer House foreclosure is the loan to watch, since its resolution will drive much of Hilton’s nonperforming balance. Marriott’s limited-service book, at a 16.66% nonperforming rate, also bears close monitoring in what remains the sector’s weakest segment.