- Nonresidential construction inputs rose 1.3% in August and 8.9% year over year, the fastest annual increase since November 2022.
- Copper, steel, diesel, and repair costs are rising together, affecting ground-up development, renovations, tenant improvements, and ongoing property operations.
- Higher physical asset costs can squeeze net operating margins and debt service capacity when owners are already managing expensive financing and refinancing risk.
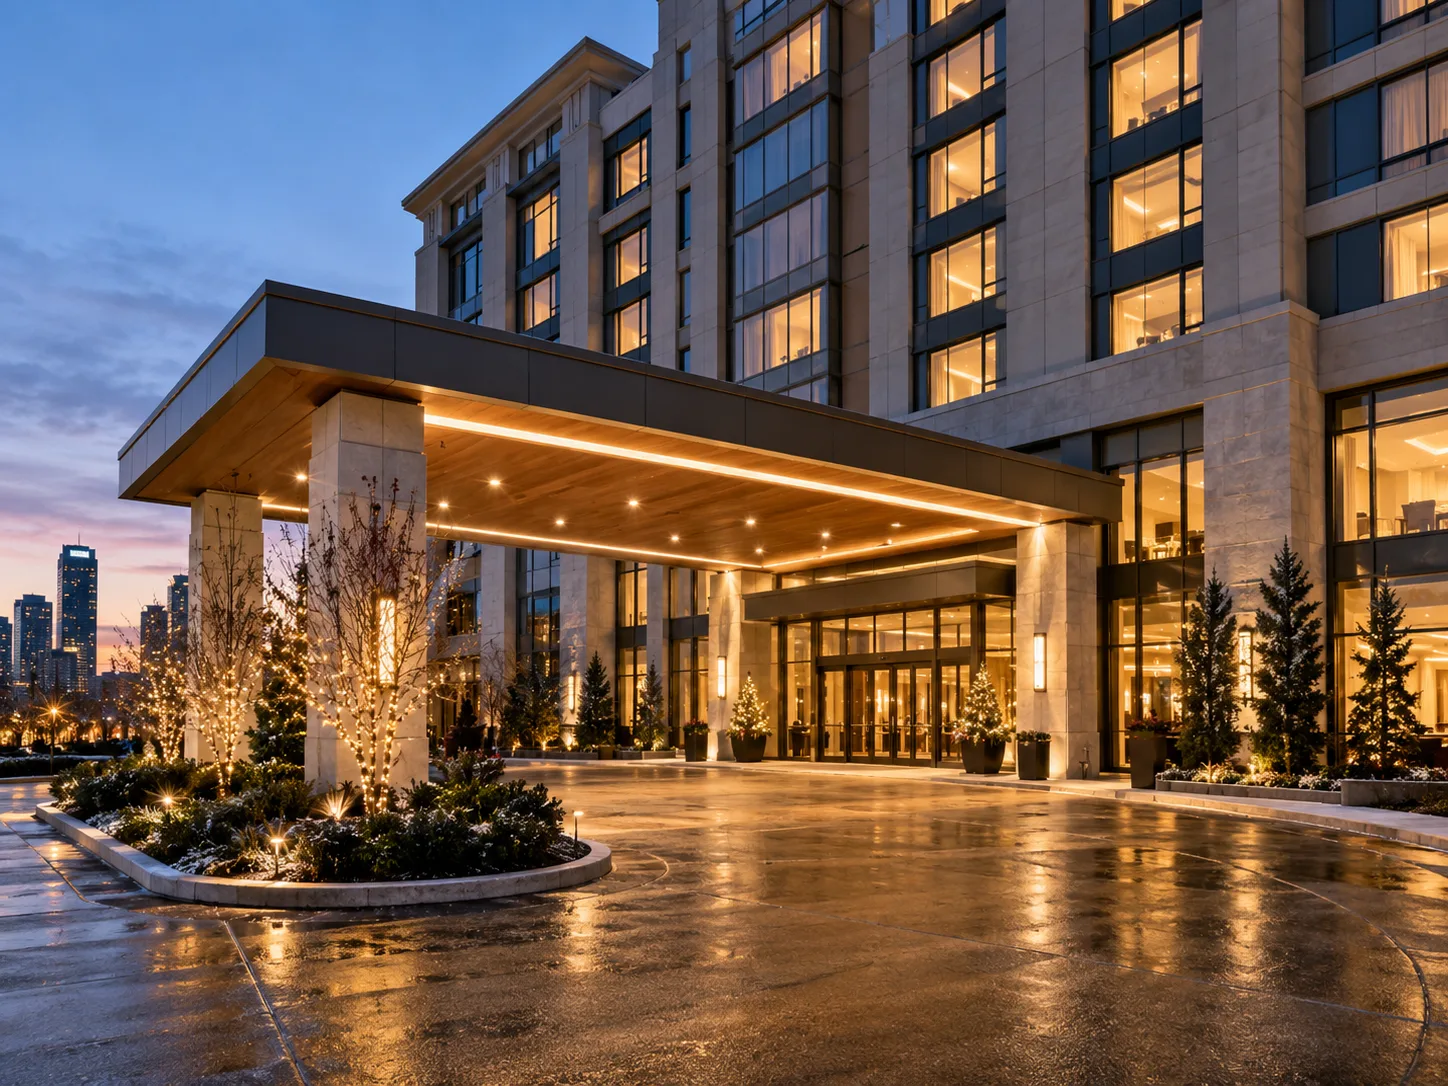
GlobeSt reports that construction and operating costs are rising across commercial real estate after two softer months of inflation data. Final-demand producer prices increased 0.4% in August and 5.4% year over year. For CRE, the sharper move came from property-specific inputs. Nonresidential construction inputs rose 1.3% for the month and 8.9% annually, according to First American economist Xander Snyder. Multifamily inputs also increased 1.3% in August and 7.5% from a year earlier.
Get Smarter about what matters in CRE
Stay ahead of trends in commercial real estate with CRE Daily – the free newsletter delivering everything you need to start your day in just 5-minutes
The Details
Both annual construction-input increases were the fastest since November 2022. That rebound can complicate underwriting for projects already working through tighter margins and higher borrowing costs. The pressure extends beyond new development because owners also face renovation, tenant improvement, replacement, and capital-project expenses.
Several core commodities moved sharply in August. Copper rose 4.2% month over month and 27.2% year over year. Steel increased 1.7% during the month and 23.4% annually. Diesel is another concern because it affects equipment and the movement of building materials. AAA data cited by GlobeSt showed the national average rising from $5.32 per gallon a month earlier to more than $6 by September 11.
Operating Costs Are Accelerating Too
The inflation pressure is also showing up after construction is complete. Nonresidential repair and maintenance costs rose 1.5% in August and 9.6% from a year earlier. Residential repair and maintenance increased 1.2% for the month and 8% annually. Those were also the fastest annual increases since late 2022.
For owners, the immediate risk is a tighter property budget. Snyder said higher repair costs can lead to more deferred maintenance and weaker net operating margins. Lower cash flow can also reduce the amount available for debt service. That matters when lenders are already examining property performance closely and many borrowers are managing refinancing exposure.
Underwriting Has Less Room for Error
The latest data put more weight on assumptions behind each acquisition or development plan. Investors cannot treat construction, maintenance, and energy costs as static inputs when several categories are moving at once. Construction cost pressure across US projects can affect both the initial basis and the later capital needs of an asset.
Snyder also pointed to active expense management as a source of value. Owners can monitor line items closely and capture savings when markets offer them. Insurance is one example where he currently sees lower rates, although he does not expect that relief to last.
Snyder said the operating side of CRE becomes more important when costs move quickly. Hands-on owners can review budgets, time capital work, and capture savings when individual expense categories improve. He pointed to insurance as one current example of temporary relief. More broadly, the lesson is to revisit assumptions rather than rely on the conditions in place when a deal was underwritten.
Why It Matters
The cost picture creates a two-sided squeeze for CRE investors. Financing remains expensive, while the physical cost of building and operating property is rising again. That combination can weaken projected returns even when the acquisition price itself appears attractive.
The August data also may not capture the full effect of the recent diesel increase because it arrived after the reporting period. As a result, later inflation reports could show additional pressure. For owners and developers, cost control is becoming a larger part of return preservation when debt, materials, and maintenance are all demanding more cash.
Construction and maintenance inflation also changes the replacement-cost side of investment decisions. An acquisition without immediate development can still require future capital work or tenant improvements. Higher input costs can therefore affect hold-period returns well after closing. The pressure is broad enough that owners need to evaluate physical asset expenses alongside financing costs, rather than treating them as separate underwriting issues.