


- CMBS distress reached 11.2% of the $617 billion in conduit and SASB loans in October, up from 10.9% a year earlier, as New York improved and other metros slipped.
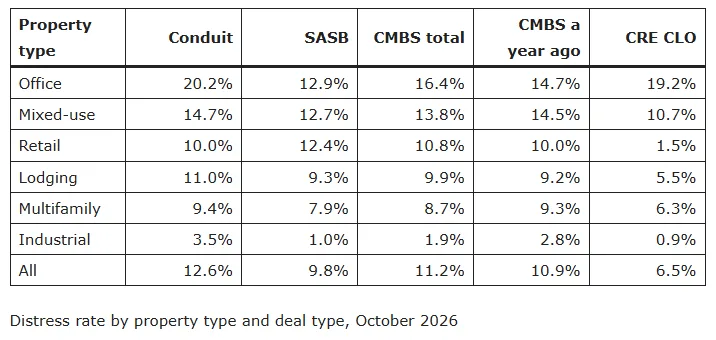
- Office is 16.4% distressed and makes up 44% of troubled balance, while fully leased assets like 2400 Market Street and Fresno Fashion Fair still hit maturity walls.
- The test is now refinancing at current rates and values, which is failing in Los Angeles, Chicago and Houston, and in the 17 remaining 2021-2022 CRE CLOs.
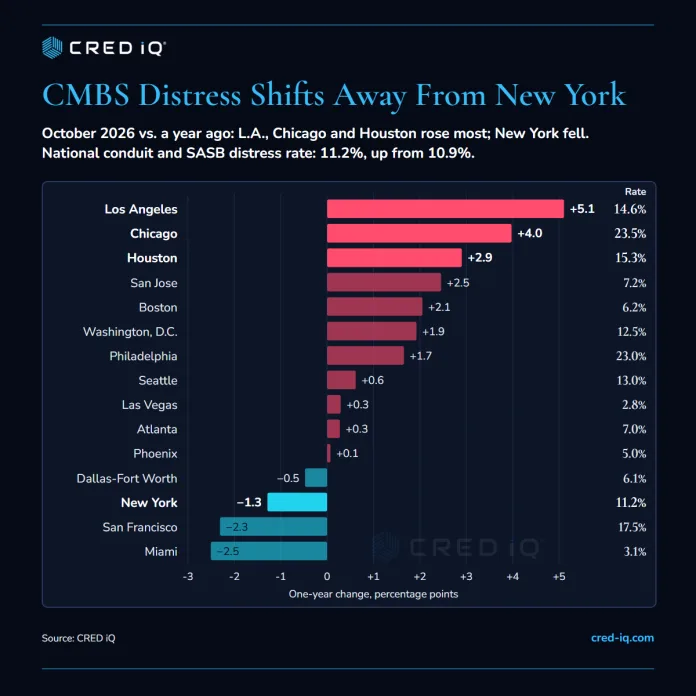
CMBS distress is moving away from New York and into Los Angeles, Chicago and Houston, according to CRED iQ’s October loan data.
Of the $617 billion in conduit and SASB loans, 11.2% is now distressed, up from 10.9% a year earlier.
Get Smarter about what matters in CRE
Stay ahead of trends in commercial real estate with CRE Daily – the free newsletter delivering everything you need to start your day in just 5-minutes
The Map Is Shifting
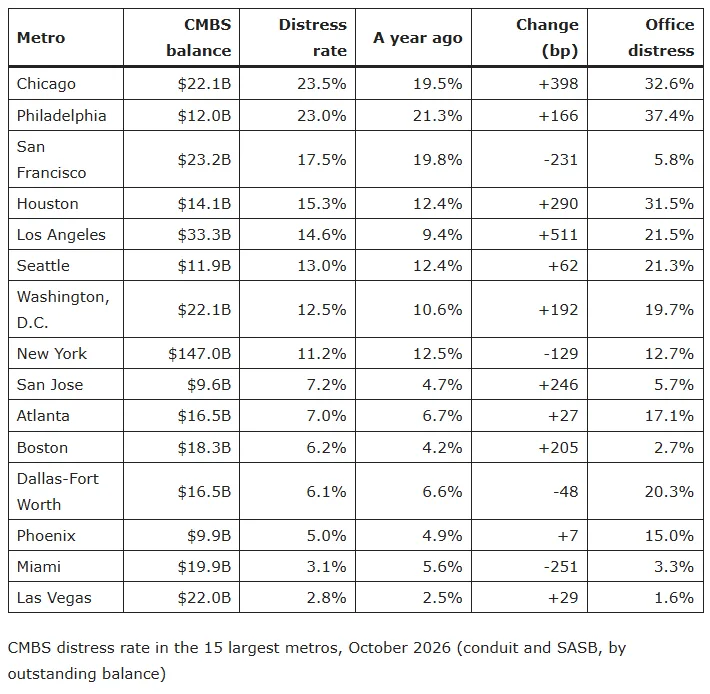
New York improved, sliding to 11.2% from 12.5%. Los Angeles went the other way, jumping to 14.6% from 9.4%.
Houston rose to 15.3% from 12.4%, and Chicago to 23.5%, up from 19.5% last year. Philadelphia sits at 23.0%, while San Francisco improved to 17.5% from 19.8%.
New York’s Misses Are About Maturity
The city’s October alerts mostly came from borrowers who couldn’t pay off at term. The $117 million Essex loan on a largely residential Manhattan building went to special servicing once the borrower admitted it couldn’t repay by Oct. 30.
60 Madison Avenue’s $100 million loan passed its Oct. 6 maturity while the borrower seeks an extension, and the building was 58% occupied at year-end. On the New Jersey side, the 65%-leased 101 Hudson Street in Jersey City, carrying $250 million of debt, went unpaid when it came due Oct. 11.
Office Still Drives the Numbers
Office distress runs 16.4% nationally and represents 44% of troubled balance. In Los Angeles it more than doubled, from 9.9% to 21.5%.
Equitable Plaza’s $74 million loan came due again Oct. 6 after an extension and wasn’t repaid. The tower’s latest valuation of $57.7 million sits far below the $150.5 million it carried at origination.
Chicago office is 32.6% distressed, and a $54 million loan on the 63%-occupied Executive Towers West in suburban Downers Grove went to special servicing. In Houston the office rate rose from 21.9% to 31.5%, and the strain has reached newer debt: three 2025 apartment loans worth $93.5 million combined slipped 30 days late.
Full Buildings Aren’t Safe
Occupancy isn’t protecting borrowers at maturity. 2400 Market Street in Philadelphia is 99.5% leased, with Aramark’s lease running to 2034, yet its $205 million loan was handed to a special servicer Sept. 29 on imminent-default grounds, with a Dec. 9 maturity looming. A modification is the servicer’s goal.
Fresno Fashion Fair’s $325 million loan went 30 days late before its Nov. 1 maturity with the mall 97.6% occupied. Industrial isn’t immune either: LBA 2024-7IND, a $321 million loan against warehouses in 10 states, reached its Oct. 9 maturity unpaid, and an extension is underway.
Why It Matters
CRED iQ flagged $4.5 billion of newly delinquent or newly specially serviced loans in October, and 93% of the flagged balance had already matured or would within six months. By property type, office ($1.5B) and hotels ($1.1B) led, followed by retail ($0.7B) and industrial ($0.5B).
CRE Daily’s earlier look at CRED iQ’s August data had the national rate easing to 10.9% and New York improving to 9.6% after $6.1 billion of loans cured. October shows how quickly that relief can stall once maturity dates arrive.
CRE CLOs look cleaner at 6.5% overall, but the 17 remaining 2021 and 2022 deals are 34.8% distressed, with 71% of their balance modified.
What’s Next
More deadlines are close. 2400 Market Street comes due Dec. 9, and THPT 2023-THL, a $746 million loan secured by 70-plus select-service hotels, was moved to special servicing for imminent default with a Dec. 6 maturity ahead.
The question for each is whether servicers keep choosing modifications and extensions, because refinancing at today’s rates and values is the hurdle these loans can’t clear.
CLOs rarely land in special servicing at maturity. Of October’s flagged CLO loans, 16 of 18 were late payers at or near payoff. The other two were transfers for Tides at Wynn Palms in Las Vegas, where two 2022 MF1 notes totaling $98 million were modified last year and now cover debt service only half the time (0.50x).