- The national CMBS distress rate slipped to 10.9% in August from 11.5% a year earlier, and preliminary September data points to 10.8%.
- Office loans carry a 16.0% distress rate and 45.5% of all distressed balance, driving stress in eight of the 11 metros examined, with Chicago highest at 25.3%.
- National averages hide wide regional gaps: New York is curing billions in loans while Midwestern office cores deteriorate and some healthier markets lean on a few key assets.
The national CMBS distress rate fell to 10.9% in August from 11.5% a year earlier, according to CRED iQ. Preliminary September figures show a further dip to 10.8%.
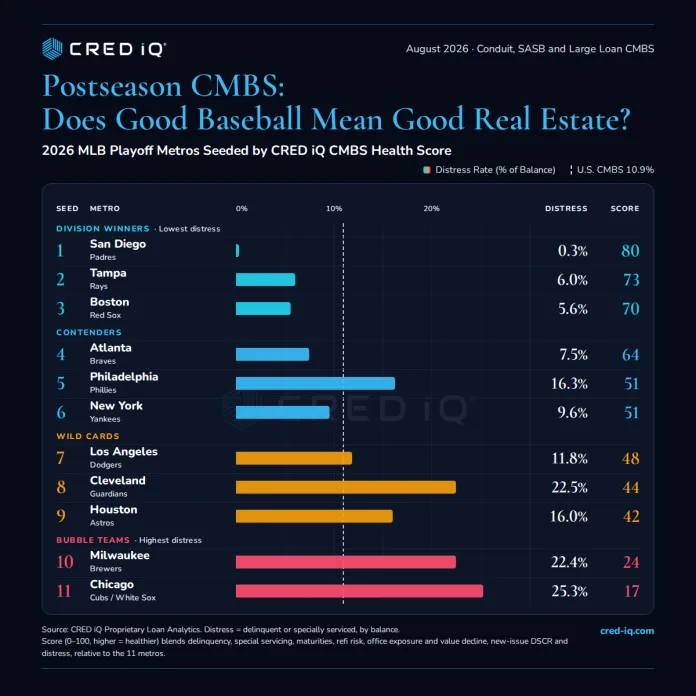
The firm broke the data out for the 11 metros with teams in the baseball postseason, and the results vary widely.
Get Smarter about what matters in CRE
Stay ahead of trends in commercial real estate with CRE Daily – the free newsletter delivering everything you need to start your day in just 5-minutes
Distress Splits the Playoff Metros
San Diego posted the lowest distress rate at 0.3%, followed by Boston at 5.6% and Tampa at 6.0%. Atlanta fell 6.7 percentage points to 7.5% after a $580M hotel portfolio loan paid off.
At the other end, Chicago’s rate hit 25.3%, up 4.7 percentage points year over year. Cleveland (22.5%) and Milwaukee (22.4%) followed.
Aon Center Shows the Damage
Chicago’s Aon Center illustrates the damage.
The loan started at $536M and was appraised at $824M at securitization, but its current valuation is $195M. It matured in July, and servicer commentary said a three-year extension was denied.
In Cleveland, $414M of distressed debt sits within one mile of Progressive Field, and Key Center has been in special servicing since 2020. Milwaukee’s Southridge Mall has lost 74% of its value.
Office Drives the Stress
Office is the common thread. Its 16.0% distress rate accounts for 45.5% of all distressed balance, and it is the main driver in eight of the 11 metros, consistent with the office special servicing surge CRE Daily has covered.
Houston’s rate rose 3.3 points to 16.0% after One & Three Allen Center ($470M) moved to special servicing at 71% occupancy. In Los Angeles, the $1.1B ICON/Hollywood Media Portfolio loan transferred ahead of maturity, and the rate rose 3.5 points to 11.8%.
New York Offers a Contrast
New York shows the other side.
Its rate dropped 2.9 points to 9.6% as $6.1B in loans cured, including 1211 Avenue of the Americas ($1.035B) and One New York Plaza ($810M). Worldwide Plaza still shows a 74% value decline.
Philadelphia’s Market Street West loans total $779M, or 40% of metro distress, while Westfield Countryside mall accounts for 62% of Tampa’s. A single asset can swing a city’s number.
What’s Next
CRED iQ’s takeaway is that national averages mask real regional variation. Watch Midwestern office loans as maturities hit, since the Aon Center shows how quickly a denied extension can turn into a resolution event.