




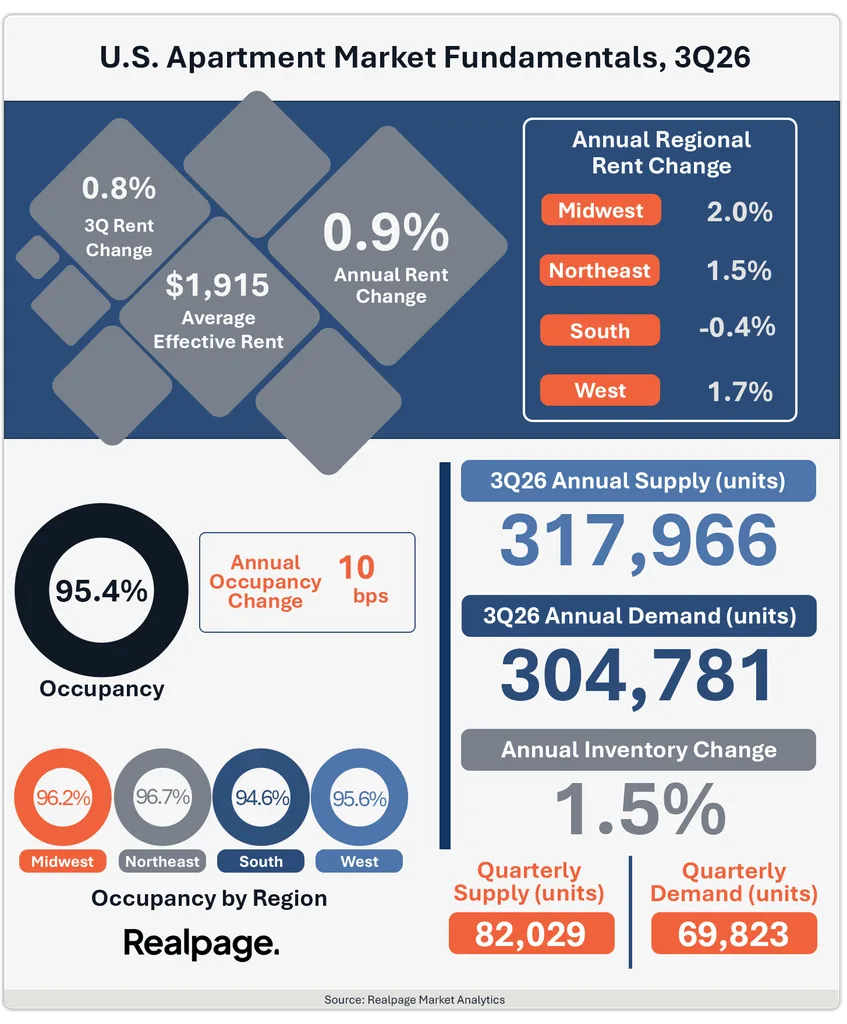
- About 304,800 apartments were absorbed in the year through Q3 2026, against roughly 318,000 completions, leaving a 13,000-unit gap, the smallest since late 2015, per RealPage.
- Occupancy held at 95.4% and effective rents rose 0.9% year over year to $1,915, the first annual gain since Q2 2025.
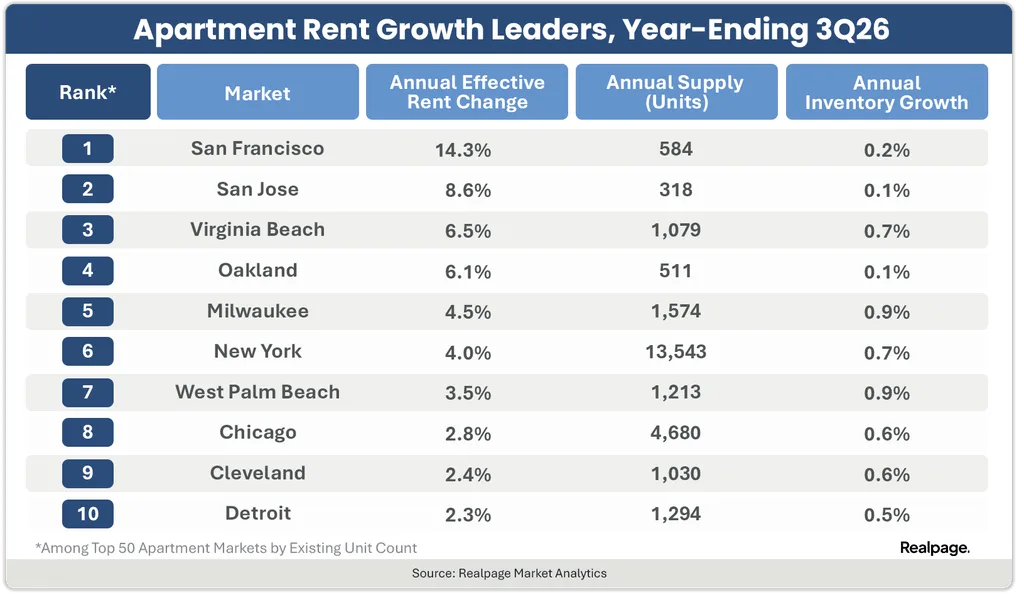
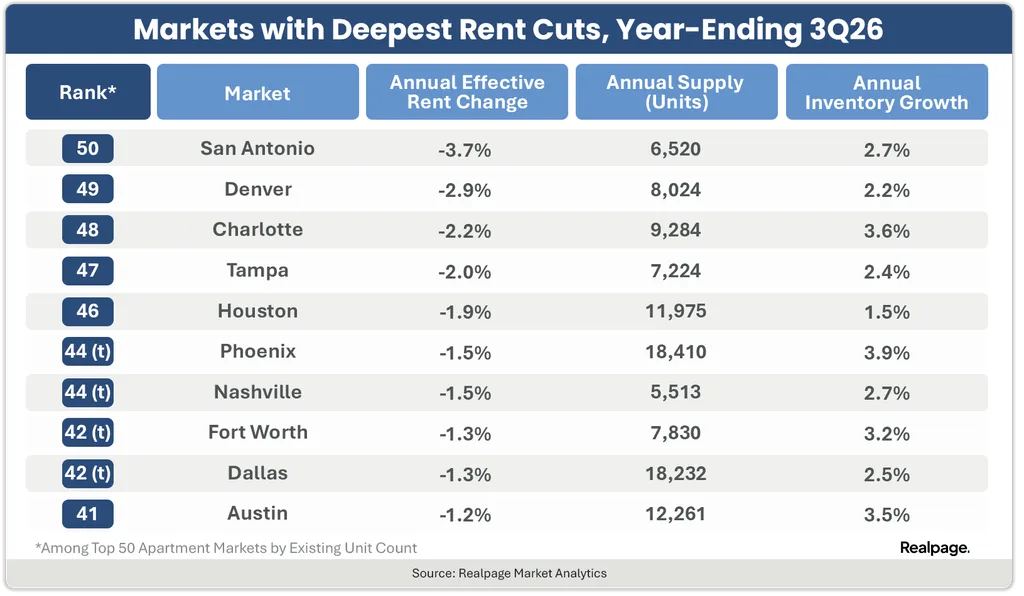
- San Francisco rents jumped 14.3% on the year and the Midwest led regions with 2%, while the South posted the only annual declines, led by San Antonio’s 3.7% drop.
Apartment demand is catching up to a shrinking wave of new supply, according to RealPage, as renters absorbed about 304,800 units in the twelve months through Q3 2026.
Annual absorption remains far under the record above 780,000 units set in Q2 2025, but the market is drifting toward a steadier balance.
Get Smarter about what matters in CRE
Stay ahead of trends in commercial real estate with CRE Daily – the free newsletter delivering everything you need to start your day in just 5-minutes
Supply Wave Recedes
Completions are falling. Roughly 318,000 units opened in the year through Q3, about 46% less than the late-2024 high of nearly 588,000. That cuts the gap between supply and demand to 13,000 units, the smallest in almost a decade, since late 2015.
The third quarter itself was modest. About 69,800 units were absorbed from July through September, more than a year ago but under the usual seasonal pace, partly because fewer empty units are left to lease.
Occupancy Holds, Rents Turn Positive
Occupancy averaged 95.4%, flat on Q2 and 10 basis points higher than a year earlier, the first annual improvement in twelve months.
With supply and demand closer together, operators lifted like-for-like effective asking rents 0.9% from a year earlier, the first annual increase since Q2 2025, to an average of $1,915. Gains have come every quarter this year, 0.8% in Q3 after 1.8% across the first half.
About 22.7% of apartments offered concessions, averaging 7.5%, a slight pullback.
Coastal Tech Hubs and the Midwest Lead
Rent growth varies widely. San Francisco led with a 14.3% annual gain and a 5.6% jump in Q3, while San Jose and Oakland up 6% to 9%. Virginia Beach gained 6.5% with 97.7% occupancy, the highest among the 50 largest markets, and New York slowed to 4%.
By region, the Midwest posted the best growth at 2%, led by Detroit, Cleveland, Chicago and Milwaukee.
Sun Belt Still Absorbing Supply
The South is still digesting new supply. It was the only region with falling annual rents and occupancy under 95%. San Antonio fell 3.7% with occupancy at 93.1%, while Denver, Charlotte, Tampa and Houston dropped between roughly 2% and 3%.
Some trouble spots are mending. Phoenix and Austin have narrowed yearly declines to under 2%, and both rose between July and September.
Why It Matters
Matching demand with supply is the precondition for rent growth, so the return of positive annual rents is a turning point for owners. It also follows signs that apartment concessions ease across large markets.
The recovery remains uneven, with coastal and Midwest markets gaining as oversupplied Sun Belt metros still cut rents.
What’s Next
Watch whether quarterly rent gains continue as completions fall and whether Sun Belt markets such as Phoenix and Austin sustain their improvement.