




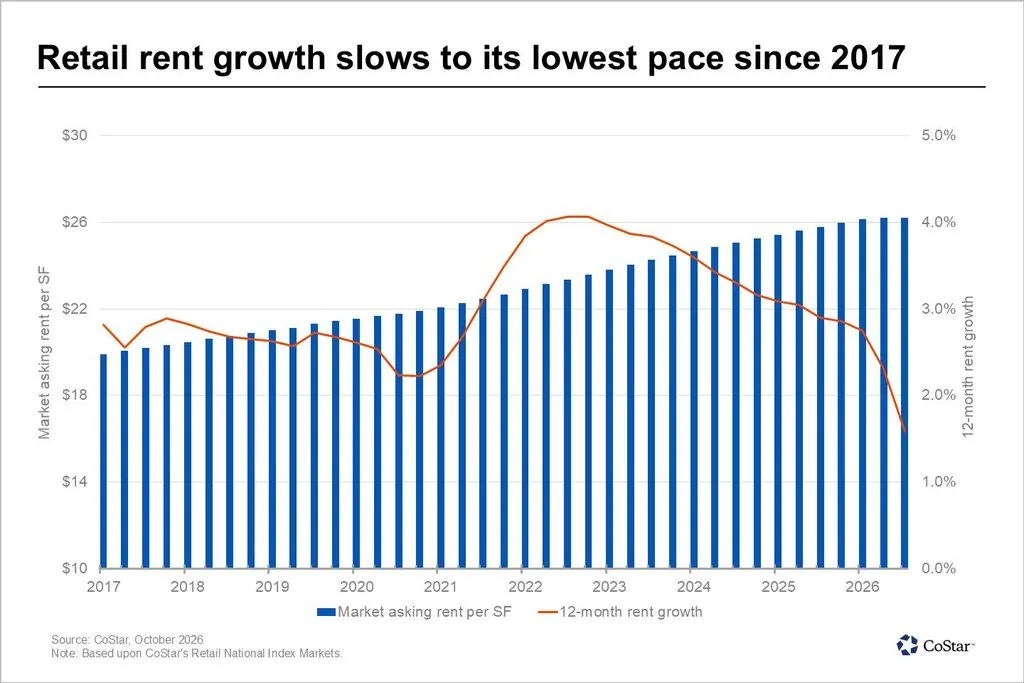
- CoStar’s Q3 data put national annual retail asking rent growth at 1.6%, the weakest since 2017, versus 2.3% in Q2 and 2.9% a year earlier.
- Power and neighborhood centers led at about 2.4%, strip centers and malls gained roughly 1.7%, and general retail, the biggest category by inventory, slowed to about 1.0%.
- Rent momentum is fading despite solid leasing demand because tenant economics cap increases; Cincinnati, Nashville and Charlotte lead large markets, while Pittsburgh and San Diego declined.
Retail asking rent growth cooled to 1.6% in Q3, the slowest pace since 2017, according to CoStar data reported by Chain Store Age.
The rate was 2.3% in Q2 and 2.9% a year earlier. It slowed even as demand held up for a second straight quarter.
Get Smarter about what matters in CRE
Stay ahead of trends in commercial real estate with CRE Daily – the free newsletter delivering everything you need to start your day in just 5-minutes
Power Centers Lead, General Retail Lags
Power and neighborhood centers grew about 2.4% from a year earlier. Strip centers and malls managed roughly 1.7%.
General retail makes up the biggest slice of inventory, and its growth fell to around 1.0%.
Tenants Set the Ceiling
Tenant economics now cap what landlords can charge, said Brandon Svec, who leads retail analytics at CoStar. High operating costs and pickier expansion plans have retailers pushing back on increases.
The resistance is strongest among discretionary retailers, whose sales haven’t kept pace with costs. General retail’s roughly 1.0% sits well below the 1.6% national figure, so the biggest segment is dragging the average down.
Leaders and Laggards
Among metros with at least 100M SF of retail inventory, Cincinnati grew fastest at 6.2%, then Nashville at 5.3% and Charlotte at 5.0%. Pittsburgh slid 1.4% and San Diego 1.3%.
Local strength can run against the national trend. Colliers data covered by CRE Daily showed Southern California retail vacancy at 6.15% in Q3, with Orange County rents up 3% to $2.65 per SF.
Why It Matters
Thin new supply cushions occupancy, but it hasn’t translated into pricing power. CoStar counted 58.3M SF under construction in Q3, down from 60.6M SF in Q2 and 63.3M SF in Q1, about 4% below the 10-year average of 60.7M SF.
As CRE Daily reported, retail starts of 7.7M SF marked the weakest quarter since at least 2016.
For owners, the message is that renewal spreads will depend on tenant sales, not just scarcity.
What’s Next
CoStar expects the pipeline to shrink further before any meaningful recovery. If sales firm up in discretionary categories, rent growth could find a floor, but tenants are setting terms for now.