
- Raleigh, Sacramento and Jacksonville are expected to see meaningful increases in BTR deliveries despite lower recent completion volumes than major supply hubs.
- National BTR completions have fallen below 60,000 units on a trailing 12-month basis after peaking above 70,000, but the pipeline remains substantial.
- Owners can prepare before lease-up by mapping competing projects, pressure-testing rents and tightening leasing operations ahead of new deliveries.
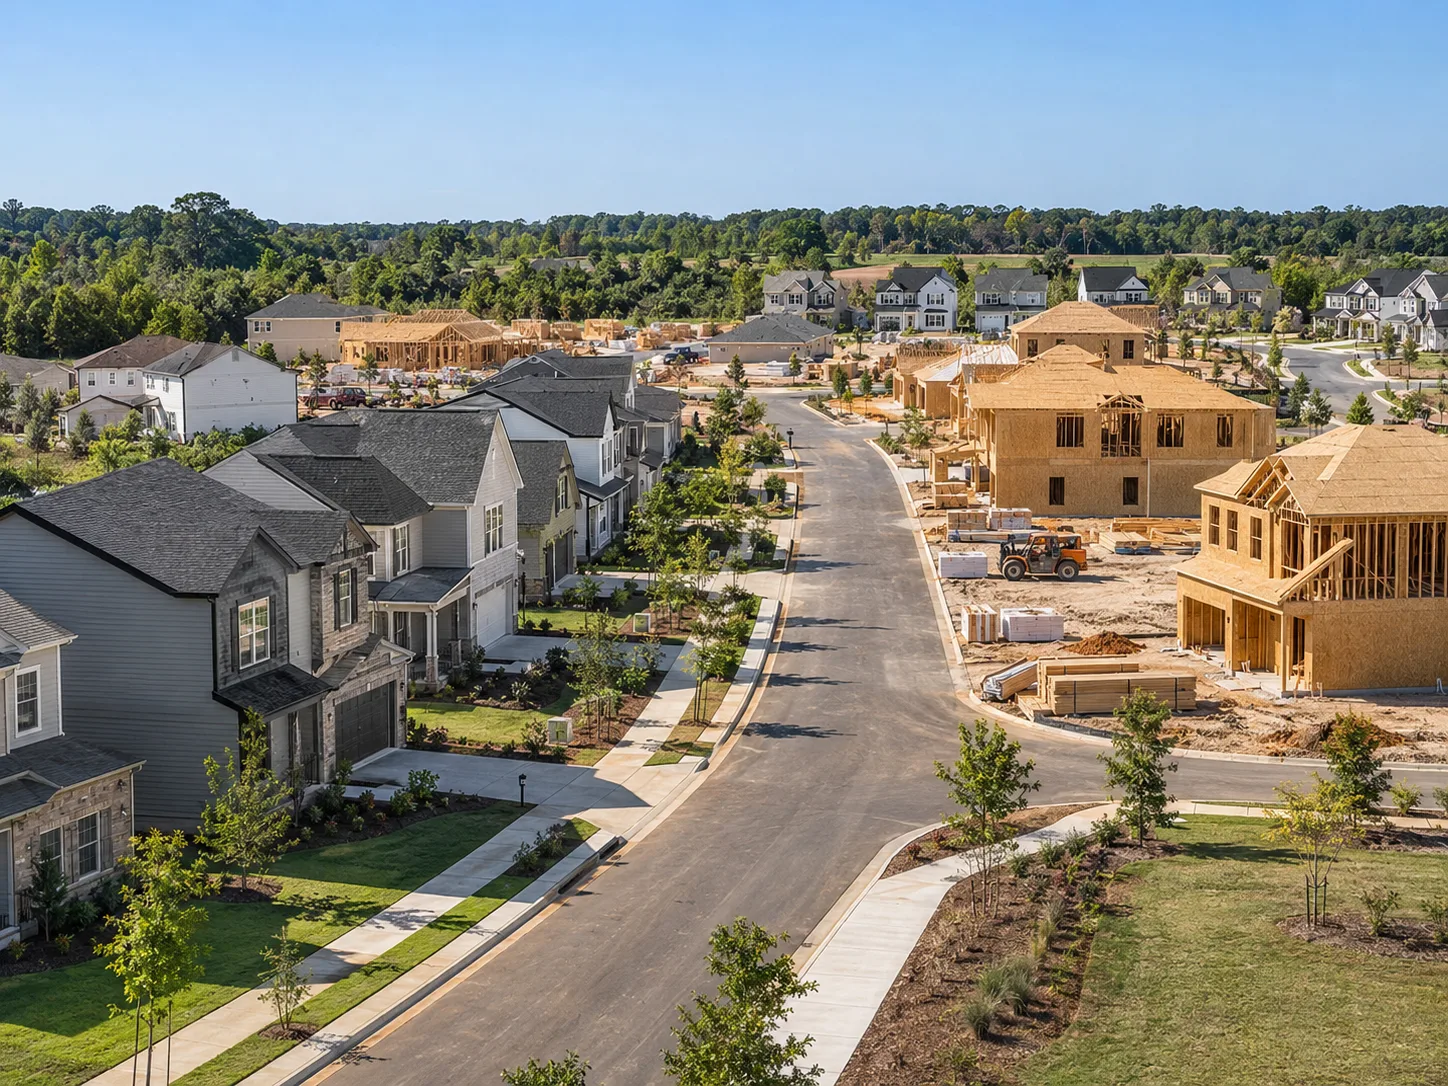
Raleigh, Sacramento and Jacksonville are emerging as the next markets to watch for build-to-rent supply. GlobeSt reports that Jay Parsons highlighted the three metros for meaningful future deliveries. They did not lead recent completion volumes. Their risk is more prospective. Projects under construction can reshape leasing conditions over the next 12 to 24 months as they move into lease-up.
Get Smarter about what matters in CRE
Stay ahead of trends in commercial real estate with CRE Daily – the free newsletter delivering everything you need to start your day in just 5-minutes
Supply Pressure Starts Before Delivery
The national BTR pipeline is easing from a high base, but it remains large. More than 70,000 units were completed at the peak, according to John Burns Research & Consulting data cited by Parsons. Trailing 12-month completions are now below 60,000. Phoenix, Dallas-Fort Worth, Atlanta, Houston and Austin drew the most attention because they received the largest recent delivery volumes. Raleigh, Sacramento and Jacksonville are different because much of their competitive pressure is still ahead. That timing gives incumbent owners an opportunity to prepare before lease-up activity directly changes the renter’s choice set.
The Details
Owners can map projects by location, product type, likely opening date and target renter profile before units hit the market. That preparation matters because new BTR communities can compete with scattered-site rentals for the same households. More rental inventory does not automatically create more renter households. The build-to-rent construction pipeline can affect occupancy, rents and concessions before supply appears in trailing data. It can also raise marketing costs and expose differences in product quality, pricing discipline and property-management execution. Parsons framed the central issue as a supply-and-demand balance rather than a simple benefit from high mortgage rates.
Raleigh and Sacramento Get a Planning Window
Raleigh has not matched Phoenix’s roughly 8,000 recent BTR completions or Dallas-Fort Worth’s nearly 5,500. Still, Parsons expects deliveries to increase meaningfully. Existing owners can compare home sizes, rent bands, school districts, yard offerings and parking against incoming communities. They can also separate resident retention from prospect acquisition. Sacramento operators have a similar window to refine positioning. Existing assets can compete on location, established landscaping, layouts and resident service instead of relying only on broad rent cuts. The source argues that operators should identify those advantages before new communities begin heavy marketing.
Jacksonville Faces Added Pressure
Jacksonville enters the next delivery phase with essentially flat rent growth in the data cited on the podcast. The market also has one of the higher institutional ownership shares within single-family rentals. Additional BTR supply would add purpose-built competition to scattered-site homes and smaller landlords. The source does not identify new construction as the sole driver of current conditions. Still, it shows why owners should monitor future deliveries closely. More choices can reduce pricing power even when underlying renter demand remains present.
Why It Matters
A growing competitive set can lengthen vacancy and increase concession needs. It can also raise the cost of converting leads into leases. Owners with better supply visibility can separate retention strategy from new-lease strategy. Existing residents may value a home, neighborhood or school district enough to stay. Prospective renters are more likely to comparison-shop when newly built alternatives open. That puts more weight on lead response times, digital presentation, tour conversion and pricing accuracy. Operators that wait for slower traffic to appear are reacting after the supply shift has already reached leasing results.
What’s Next
The key operating task is to track projects as they move from land development to vertical construction, preleasing and final delivery. Owners can also pressure-test revenue assumptions for slower lease-up, more concessions or lower new-lease rents. Leasing teams may need stronger follow-up processes and more consistent tour coverage as choices expand. Staffing coordination can matter as lead volume rises without a matching increase in conversion. In all three markets, the useful preparation window is before the new communities are fully open and heavily marketed.