


- A total of $4.42B of private-label CMBS debt reaches hard maturity in November across 201 loan pieces, and more than half has a debt yield under 8%.
- Hospitality, retail and office make up nearly three-quarters of the balance, while retail has a 12.83% delinquency rate and mixed-use carries the highest special servicing share.
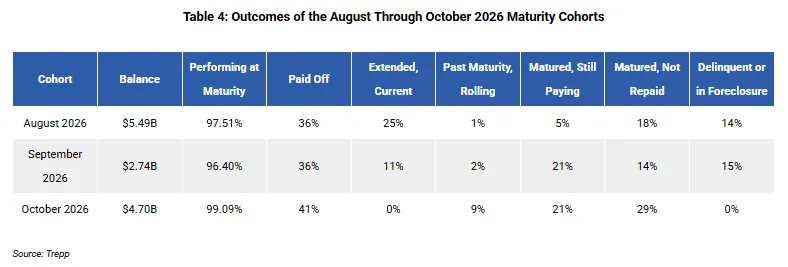
- Even performing loans often miss payoff: only 36% to 41% of the August through October cohorts had repaid by the October remittance, despite 96% to 99% performing at maturity.
Another $4.42B of CMBS debt comes due in November, according to Trepp Research.
It covers 201 loan pieces on 182 whole loans, and over half yields under 8% on current cash flow.
Get Smarter about what matters in CRE
Stay ahead of trends in commercial real estate with CRE Daily – the free newsletter delivering everything you need to start your day in just 5-minutes
Mostly Performing, for Now
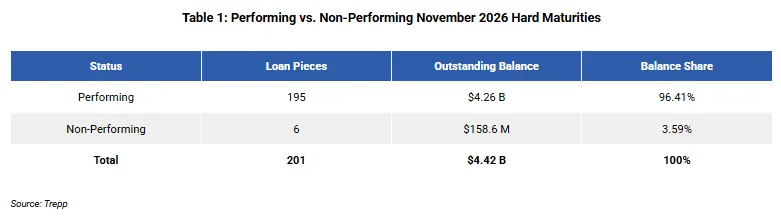
About 96% of the balance, or $4.26B, is performing. Non-performing loans total $158.6M across six pieces, and $145M of that traces to one California mall.
Still, $1.66B (37.62%) sits in special servicing.
Hotels, Retail and Office Lead
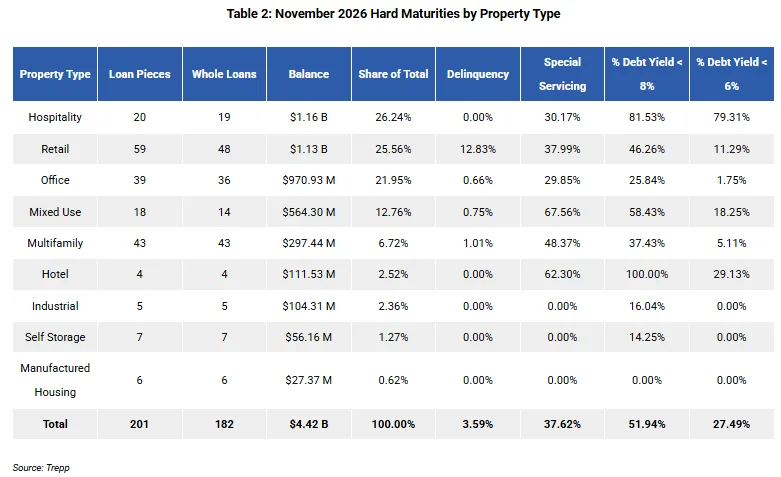
Hospitality is the biggest slice at $1.16B, followed by retail at $1.13B and office at $970.9M. Hospitality has the thinnest cushion: 79.31% of its balance has a debt yield under 6%.
Retail shows the most immediate stress, with 12.83% delinquent. Mixed-use has the highest special servicing share at 67.56%, on just 12.76% of the pool.
An $805M Refi Gap
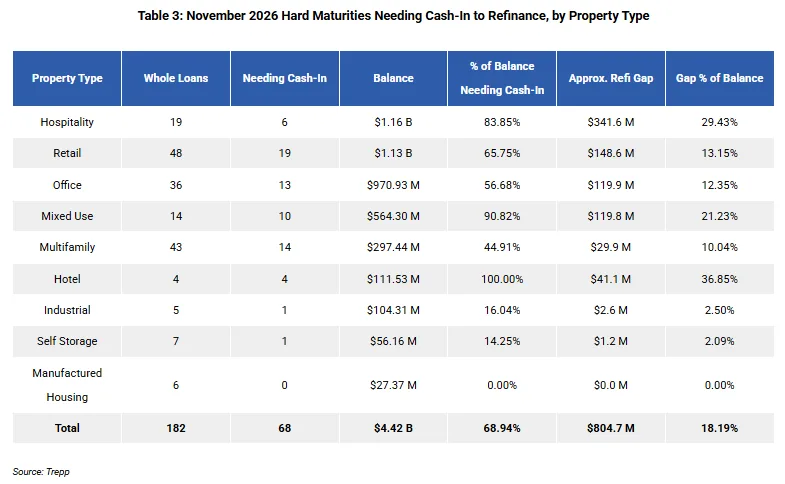
Trepp sized new loans at a 1.35x DSCR and indicative all-in rates of 6.44% to 7.11%. At those terms, 68 of the 182 whole loans, with $3.05B in outstanding debt, cannot refinance at their current balances.
Lenders would need $804.7M in new cash to close the gap, equal to 18.2% of the cohort. Meanwhile, fixed-rate loans account for about 80% of the balance and carry an average 4.14% coupon.
Maturity Isn’t Payoff
Nearly every loan in the three prior monthly groups, from August through October, remained current heading into maturity. However, only 36% to 41% of each group had fully repaid by October’s remittance.
Instead, borrowers took several paths. Some extended their loans, while others passed maturity but continued making payments. The remaining loans either went unpaid at maturity or became delinquent. October remains the least settled cohort because it has only one remittance since maturity.
Zoom Out
Those unresolved loans are one reason the special servicing rate reached 11.74%, a 13-year high, in our earlier coverage.
Why It Matters
A loan that is current can still be stuck if the property can’t support a bigger new loan at today’s rates. Lenders then choose between extending and pushing for equity.
The strain isn’t limited to offices and malls. We covered how multifamily maturities total $250B through 2028.
What’s Next
The five largest November maturities total $1.60B, or 36.23% of the pool. Watch the November and December remittances to see how many pay off, extend or slide into special servicing.