
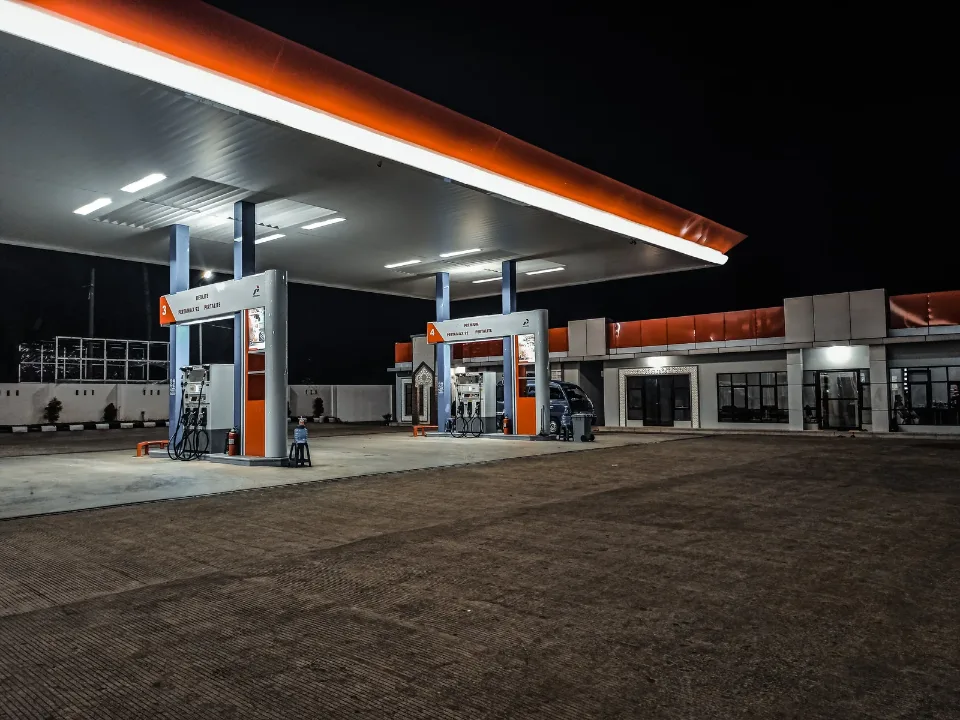



- Global Net Lease has 15 gas station, convenience and car wash properties under contract for about $70M at a 6.5% cash cap rate, versus 7.7% for other occupied sales this year.
- Gas station and car wash buildings count as 15-year property, so 100% bonus depreciation can cover the whole building without much cost segregation work.
- The Boulder Group put average single-tenant net lease asking cap rates at 6.92% in Q3, up 10 bps, while GNL sold office at a 7.5% cash cap rate.
Tax law is setting prices for fuel stops and car washes, and cap rates are falling while the wider net lease market softens, according to GlobeSt.
Global Net Lease agreed to sell 15 of them for roughly $70M, a 6.5% cash cap rate.
Get Smarter about what matters in CRE
Stay ahead of trends in commercial real estate with CRE Daily – the free newsletter delivering everything you need to start your day in just 5-minutes
A Pricing Gap
GNL’s other occupied sales this year priced at 7.7%. Elsewhere, The Boulder Group’s Q3 read on single-tenant net lease asks averaged 6.92%, 10 bps above Q2.
On the earnings call, CEO Michael Weil credited bonus depreciation demand for holding up the price.
Why the Tax Break Fits
Full expensing returned under a 2025 tax law for qualifying assets acquired after Jan. 19, 2025 with recovery lives up to two decades. Because the IRS treats fuel station and car wash structures as 15-year property, the whole structure qualifies, beyond just fixtures.
Typical commercial buildings write off over 39 years, so investors usually commission an engineering review to speed some deductions. These properties mostly sidestep that.
A Year-End Rush
The Tax Refinery notes an asset only counts for a given year if it is in service by year-end, so buyers chasing 2026 deductions need to close soon.
Weil said GNL hadn’t planned to sell but moved fast because the tax break drives year-end buying. The deals are expected to close by December.
What GNL Gives Up
The assets generate roughly 3% of the REIT‘s straight-line rent, falling to about 2% once they close.
Weil said getting a mid-6% cap rate in this market makes the sale worthwhile over the long run.
Zoom Out
Buyers have been drawn to these assets for a while. We covered how gas station real estate drew buyers despite soaring fuel prices.
The tax angle is also behind a broader rush. See our report on how bonus depreciation fuels year-end CRE deals.
Why It Matters
That deduction carries more value for a buyer expensing the whole price than for a long-term holder who has already depreciated most of it. That gap shows up in price.
Office tells a different story. Through Sept. 30, GNL sold $123M of it, pricing leased buildings at a 7.5% cash cap. Office is 68% of its $391M disposition pipeline and now 23% of rent, from 27%.