
- Midwest transportation and warehouse employment rose 30% over the past decade, adding 257,000 workers.
- The sector now employs about 1.1M people, but employment slipped 0.1% over the past 12 months.
- CBRE found 91.3% of surveyed occupiers expect to maintain or expand warehouse and manufacturing footprints.
Midwest industrial labor growth has cooled after a decade of rapid expansion. CBRE’s 2026 Transportation and Warehouse Labor Metrics report found the region added 257,000 transportation and warehouse workers over the past 10 years. Sector employment increased 30% during that period, far ahead of overall employment growth of 5.3%.
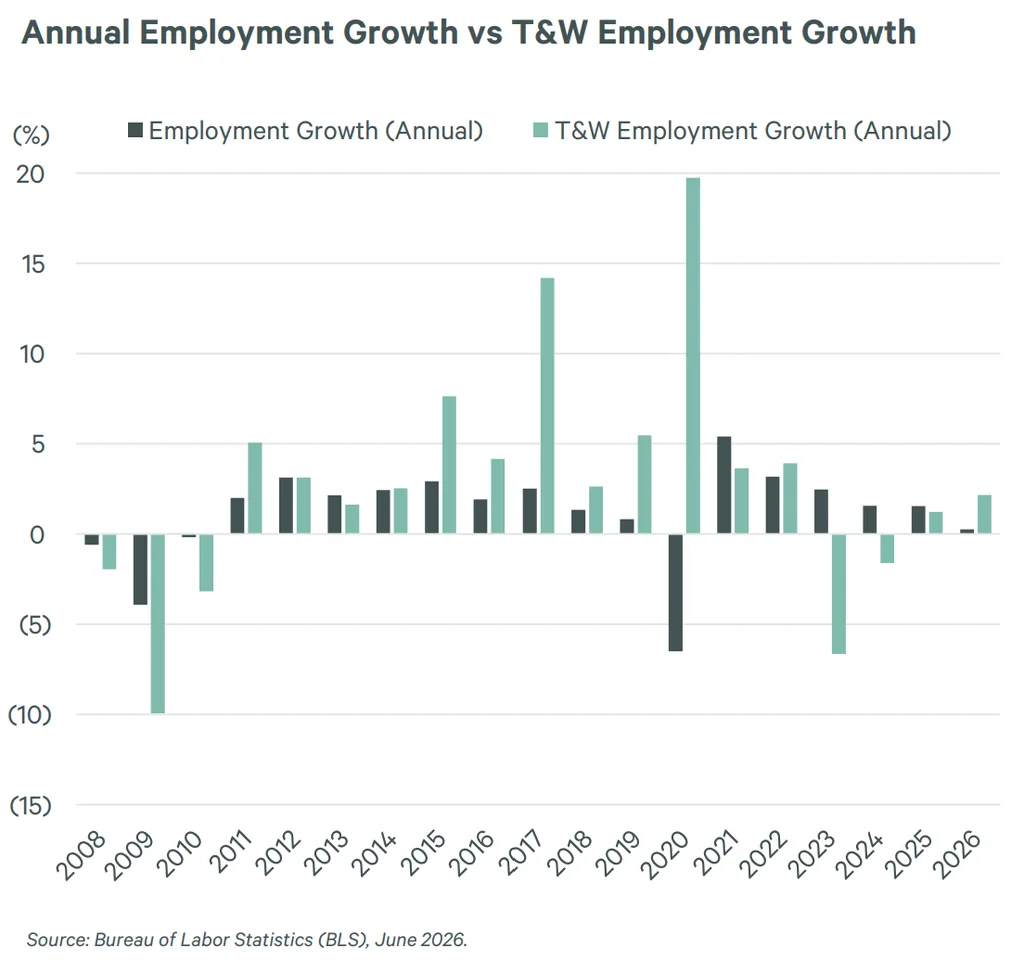
However, transportation and warehouse employment slipped 0.1% over the latest 12 months as development activity slowed. The region’s labor pool totals 22.4M people, while the combined population of the 21 markets is 43.8M. CBRE calculates five-year labor-pool growth at 6.9% and projects population growth of 0.9% through 2031.
Get Smarter about what matters in CRE
Stay ahead of trends in commercial real estate with CRE Daily – the free newsletter delivering everything you need to start your day in just 5-minutes
Labor Growth Normalizes
The report evaluates the 21 largest Midwest markets and compares labor supply with industrial demand. Transportation and warehouse employment now totals about 1.1M workers across those markets. The sector represents roughly 5% of overall employment.
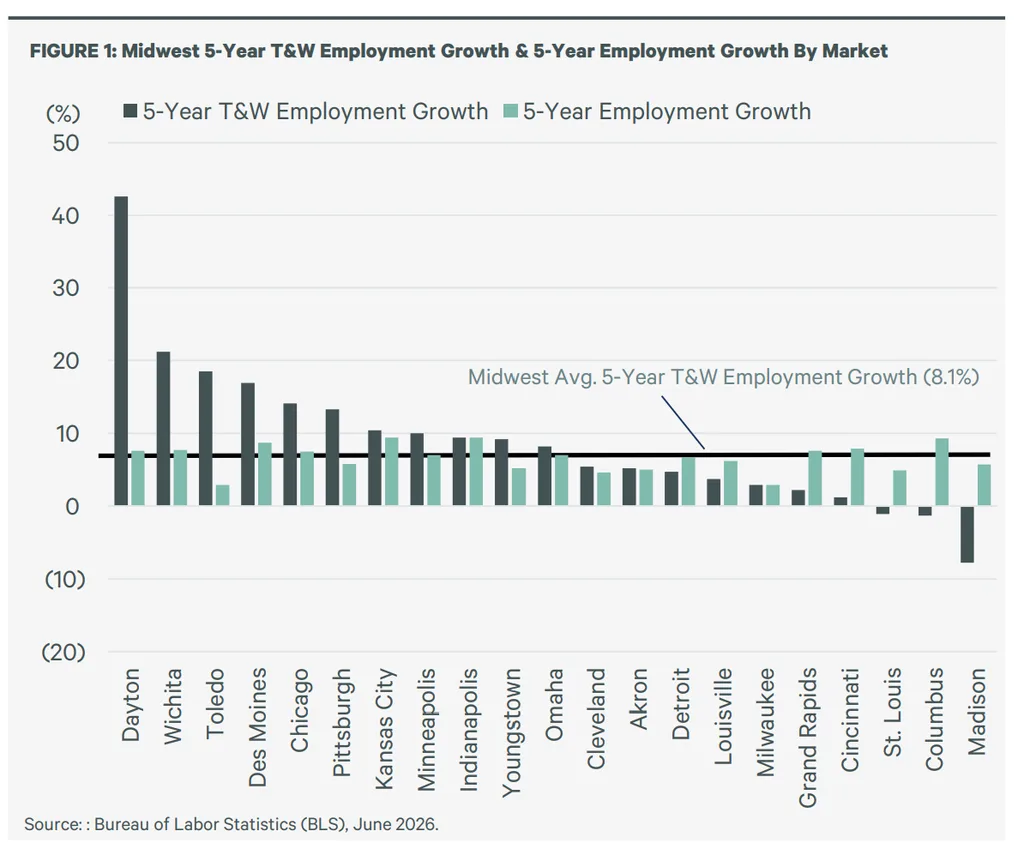
Over the five years ended in 2026, transportation and warehouse employment increased 8.1% across the region. Eleven of the 21 markets exceeded that average. Dayton posted 42.6% growth, followed by Wichita at 21.2%, Toledo at 18.5% and Des Moines at 16.9%. Chicago grew 14.1% and Pittsburgh increased 13.3%. The longer trend remains much stronger than the latest year.
Transportation and warehouse employment averaged 3.0% annual growth since 2016. It also grew faster than the overall workforce during the recovery years following 2020. That expansion lifted the sector’s share of Midwest employment from about 4% to 5% over the decade.
The Details
Industrial real estate expanded alongside the labor force. Major Midwest markets recorded 773M SF of positive net absorption during the past decade. They delivered about 797M SF of new space over the same period. The relationship reflects how distribution growth and warehouse hiring moved together through the expansion cycle.
Six markets have transportation and warehouse employment shares above the Midwest’s 5% average. Louisville leads at 8.7%, followed by Indianapolis at 7.0% and Columbus at 6.3%. Chicago stands at 6.0%, Toledo at 5.8% and Kansas City at 5.5%.
Labor conditions vary widely by market. CBRE assigned positive distribution-market ratings to several metros, including Columbus, Des Moines, Indianapolis, Louisville, Omaha, Toledo and Wichita. Minneapolis received a negative rating, while many others were neutral. The methodology compares supply and cost metrics with national averages.
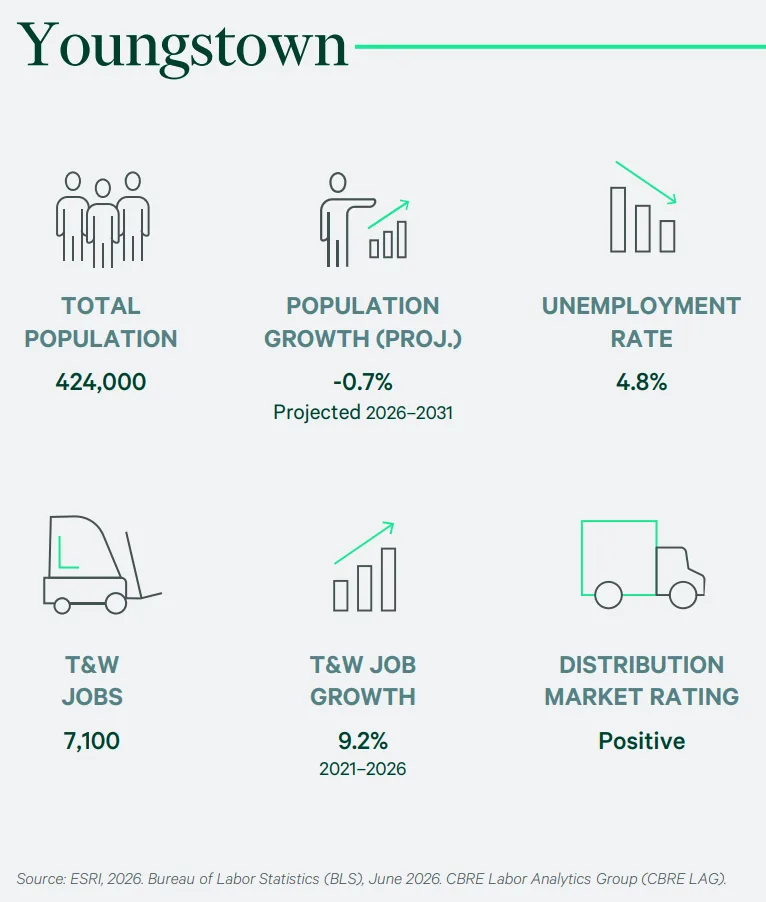
CBRE also reported a regional median household income of $83,991 and median home value of $293,030. Its cost-of-living index was 94.4. About 54.6% of adults age 25 and older had a high-school-through-associate-degree education level as their highest attainment. Those measures help frame the supply and affordability of industrial labor.
Why It Matters
Warehouse users still view the Midwest as an expansion market even as employment growth normalizes. Distribution demand continues to support industrial space needs across the region. CBRE’s 2026 occupier survey found 91.3% of respondents expect to maintain or expand warehouse and manufacturing footprints. Another 21.7% expect to expand in the Midwest, making it the second-most preferred region in the survey. Labor access remains central to those decisions.
Key demand drivers include third-party logistics, e-commerce, consumer retail and suppliers supporting data-center development. The report argues that employers still need deep pools of skilled and cost-effective workers as those occupiers scale.
The survey shows 34.8% of occupiers expect warehouse or manufacturing requirements to increase. Another 56.5% expect them to remain the same. Only 8.7% expect a decrease. That creates a demand backdrop where labor availability may matter as much as real estate availability.
What’s Next
CBRE expects e-commerce to remain a major labor and space driver. Its research projects e-commerce will reach 33.6% of relevant retail sales in the next decade. The Midwest’s challenge is different from the past expansion period. Markets now need to support occupier growth while labor gains have flattened and development has slowed.
The most competitive locations will be those balancing workforce scale, labor costs and industrial capacity. Because warehouse employment has already normalized, future absorption will not automatically produce the same hiring surge seen earlier in the cycle. Market-level differences in unemployment, population growth and labor costs will become more important as occupiers compare locations.