

- TPG Real Estate raised roughly $5 billion for its fifth opportunistic fund and related vehicles, while ACORE Capital closed a $1.1 billion opportunistic credit fund.
- ACORE’s second fund topped its $1 billion target and is more than four times its 2020 predecessor, and TPG says it had $13.7 billion available for real estate at quarter end.
- Both are positioning for owners squeezed by maturities: Trepp counts almost $800 billion of U.S. commercial property loans due by the end of 2026 and $733 billion next year.
Capital for distressed real estate is stacking up as maturities close in: TPG Real Estate and ACORE Capital have raised more than $6 billion combined for opportunistic strategies, Bisnow reports.
Close to $800 billion in U.S. commercial mortgages mature by year-end, with $733 billion more in 2027.
Get Smarter about what matters in CRE
Stay ahead of trends in commercial real estate with CRE Daily – the free newsletter delivering everything you need to start your day in just 5-minutes
The Wall Both Are Eyeing
Lower asset values are colliding with expensive refinancing, which is what both firms are betting on. Our brief on the CRE debt wall view that lenders are now less willing to grant extensions, so more distress is likely to surface.
That pressure is the opening for investors with fresh capital.
TPG’s Fifth Opportunistic Raise
Bisnow reported, that TPG Real Estate raised roughly $5 billion through the fifth fund in its opportunistic real estate series and related vehicles. The money targets assets that are tough to buy from owners in trouble.
The raise as one piece of a major fundraising cycle in its real estate unit. CEO Jon Winkelried said on the third-quarter earnings call that holders of big real estate portfolios increasingly need to sell, at cap rates he called attractive and prices below replacement cost.
Per Bisnow, TPG already closed an off-market national package of medical outpatient buildings in Q3, had $13.7 billion available for real estate at quarter end, and has invested almost $2 billion more year to date than a year ago.
Our earlier brief on TPG’s $14 billion reserve reported a similar posture after the second quarter: patient capital waiting for market stress.
ACORE’s Second Fund
ACORE Capital finished raising ACORE Opportunistic Credit II on Oct. 29, with $1.1 billion pledged against a $1 billion goal. It is over four times as large as ACORE’s first opportunistic credit fund, launched in 2020.
So far it has put $400 million into 14 deals, and ACORE has put $1.34 billion into opportunistic credit since its 2015 founding. The firm manages more than $17 billion, as of June 30, 2026.
Matthew Drummond, who heads high yield strategies, said a significant basis reset across asset classes is creating chances to finance business plans at discounted valuations. With institutional equity investors still selective, he sees equity-like returns higher up the capital structure.
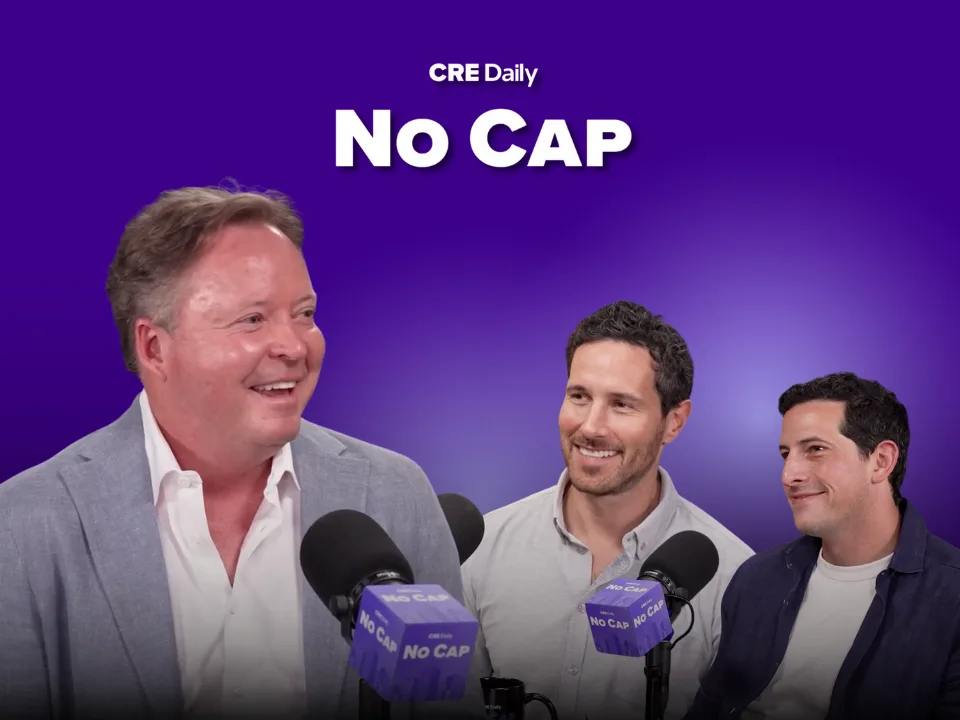
Warren de Haan, ACORE’s CEO and co-founder, said the business was built around navigating cycles, identifying where capital is needed and deploying it with discipline. He laid out how that works in our conversation with de Haan on the No Cap podcast, which went live Nov. 1.
Why ACORE Is Credit First
De Haan traces the approach to 2007. His team at Countrywide’s commercial arm saw underwriting loosen, stopped originating, hedged a roughly $4 billion loan book and sold it to regional banks.
That’s why he calls ACORE credit first and downside first. His line on the podcast: you can hedge credit spread and the underlying index, but you can’t hedge a bad loan.
Buying Into Reset Basis
Forced sellers are resetting basis, and de Haan says that’s a good place to lend from. He pointed to a fully leased San Francisco office building as an example.
The previous lender was in at $800 per SF on a building that had been valued near $1,200. It sold at $600 per SF to an ACORE borrower, and ACORE’s loan sits at $375 per SF.
He said that example is why the maturity wall looks like opportunity to him, not just stress.
Where He Sees Mispricing
With cap rate compression gone, de Haan says selection matters more than themes. If you can’t create value at the real estate itself, he said, it’s probably not a place to play.
He flagged 2021-vintage multifamily loans and spec industrial boxes, where owners now want refinancings that leave them cash neutral.
Scale and the Shakeout
ACORE averages $85 million loans with about 140 employees, and de Haan says that scale is hard to copy. He expects many newer private credit entrants to be washed out, especially those that lean on a single warehouse line.
He also recalled that when he joined Starwood Property Trust, private equity firms didn’t lend to each other. That taboo is gone, and sponsors now routinely borrow from one another’s debt funds.
Why It Matters
Dry powder is concentrating in a few hands. Private real estate fundraising hit its weakest quarter since 2013 in Q3, per PERE data in our brief on the fundraising slump, yet two sponsors just gathered billions.
Opportunistic returns aren’t guaranteed. Blackstone’s opportunistic funds lost 3.2% in Q3. These managers are buying into the same rate pressure that is creating the opportunity.
What’s Next
Watch deployment. ACORE has used roughly a third of its commitments, and TPG’s Q3 deal shows it’s willing to buy off-market. As the 2027 maturities approach, expect these funds to chase owners who can’t refinance.
De Haan’s checklist for what to back is simple: real basis resets, selective bets on 2021-vintage loans and sponsors who can still create value.