


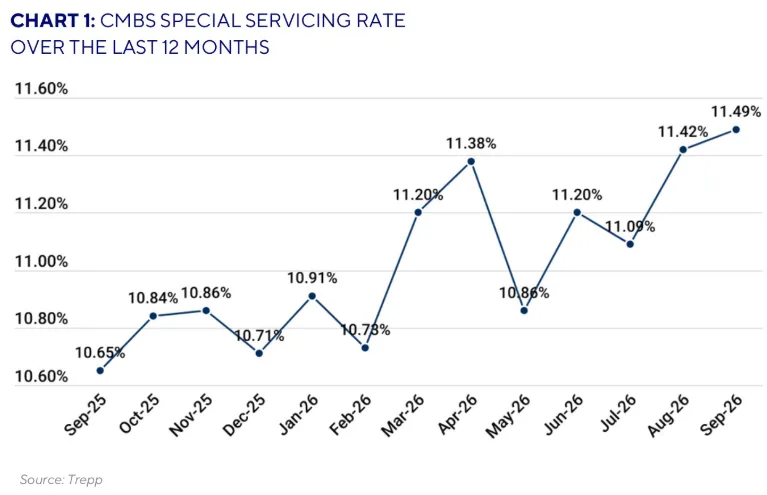
- The CMBS special servicing rate rose seven basis points to 11.49% in September, the highest since February 2013, and is up 84 basis points from a year ago.
- Office made up 57% of the $2.65B transferred to special servicing, led by the $512.8M One SoHo Square loan and the $436.9M Starwood Regional Mall Portfolio.
- Resolutions picked up as $1.95B left special servicing, up 237% from August, yet retail, lodging and multifamily rates all rose while office and industrial edged lower.
Stress in CMBS reached its highest point in over a decade last month, according to Trepp. Its special servicing rate ticked up by seven bps to 11.49%, a level last seen in February 2013.
Against a year ago, the measure is higher by 84 bps. Over half a year, it has gained 49 bps.
Get Smarter about what matters in CRE
Stay ahead of trends in commercial real estate with CRE Daily – the free newsletter delivering everything you need to start your day in just 5-minutes
Retail, Lodging and Multifamily Climb
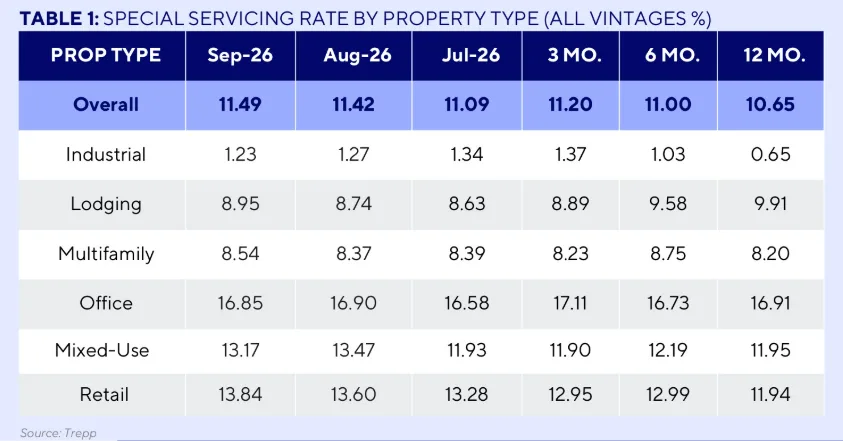
Retail led the increases at 13.84% (up 24 bps), followed by lodging at 8.95% (up 21) and multifamily at 8.54% (up 17). Going the other way were mixed-use, which fell 30 bps to 13.17%, office, off five to 16.85%, and industrial, off four to 1.23%.
Office still carries the most weight, making up 57% of the new inflow of $2.65B even as its own rate dipped, a pattern that fits the office special servicing strain seen elsewhere.
The Biggest Transfers
Forty-two whole loans moved in, 13% less by dollar volume than the $3.04B (29 loans) in August. The biggest, the $512.8M One SoHo Square loan, accounts for roughly 8.5 bps of the overall rate by itself.
The loan is backed by a 786,000 SF New York office property and was flagged for imminent balloon or maturity default. It carries a 2.72% fixed coupon, is current on payments and reports a 1.76x DSCR with 86% occupancy. Its June 2021 appraisal of $1.35B implies a 58.1% loan-to-value ratio.
The second-largest, the $436.9M Starwood Regional Mall Portfolio, covers five malls totaling 3.7M SF and moved over imminent monetary default on Sept. 1. It reports a 0.84x DSCR and 86% occupancy, and a November 2021 appraisal of $561.6M implies a 77.8% LTV.
Other Notable Names
September also brought the $420.0M office loan on 51 W 52nd in New York, the $209.0M Apple Sunnyvale office loan, the $100.0M 8 Times Square and 1460 Broadway mixed-use loan and the $100.0M Hyatt Regency Jersey City.
Two malls also moved: Square One Mall in Saugus, Mass., at $76.0M and Wolfchase Galleria in Memphis at $75.2M. About 79% of the dollars in those named loans arrived because of imminent balloon or maturity default.
Resolutions Pick Up
Exits surged. A total of 48 whole loans worth $1.95B left special servicing, versus $579.7M (32 loans) in August, a 237% jump. Eighteen ($1.00B) were handed back to the master servicer. The remaining 30 ($953.5M) are gone from the books through payoffs or liquidations.
The largest exit was the $425.0M JACX, a 1.1M SF Long Island City office property that spent five months in special servicing before going back to the master servicer with a new maturity of September 2029 plus extension options. The $249.9M Providence Place Mall loan was liquidated in late August, 28 months after it first transferred in April 2024.
Servicer commentary shows the Providence mall at 88.5% inline occupancy as of May, with foot traffic up 6.4% year over year.
Why It Matters
The rate is a gauge of how much CMBS debt servicers are working out rather than collecting on schedule. A 13-year high shows that stress persists even as resolutions accelerate, and rising retail, lodging and multifamily rates suggest it is spreading beyond office. That includes mall exposure, an area where mall loans already face pressure.
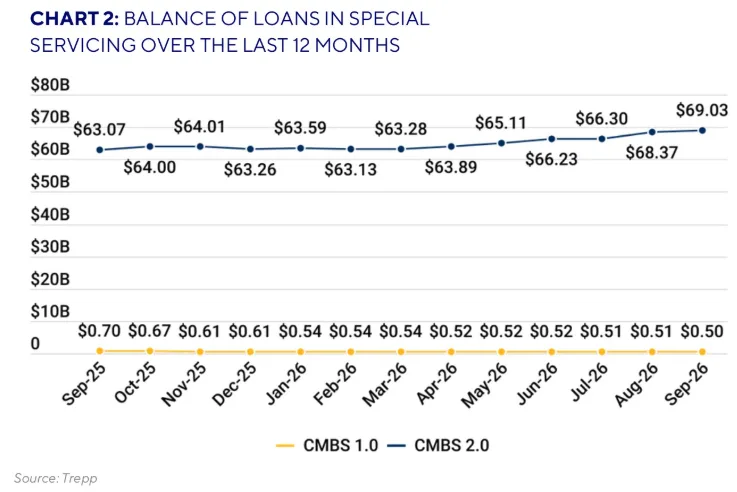
The split by vintage matters too. Post-crisis CMBS 2.0+ deals sit at 11.42%, up seven bps, while pre-2008 CMBS 1.0 deals stand at 61.89%, down seven. Just $500.0M of what servicers are handling comes from CMBS 1.0.
What’s Next
Watch the large maturity-related transfers, including One SoHo Square, which is performing but flagged ahead of a default. Whether more loans exit through payoffs and extensions, as with JACX, will decide if the rate keeps rising from here.