

- Four Las Vegas casino resort loans total $12.01B, or 13.0% of the $92.18B securitized lodging market, and all four are current with debt yields of 13.38% to 27.90%.
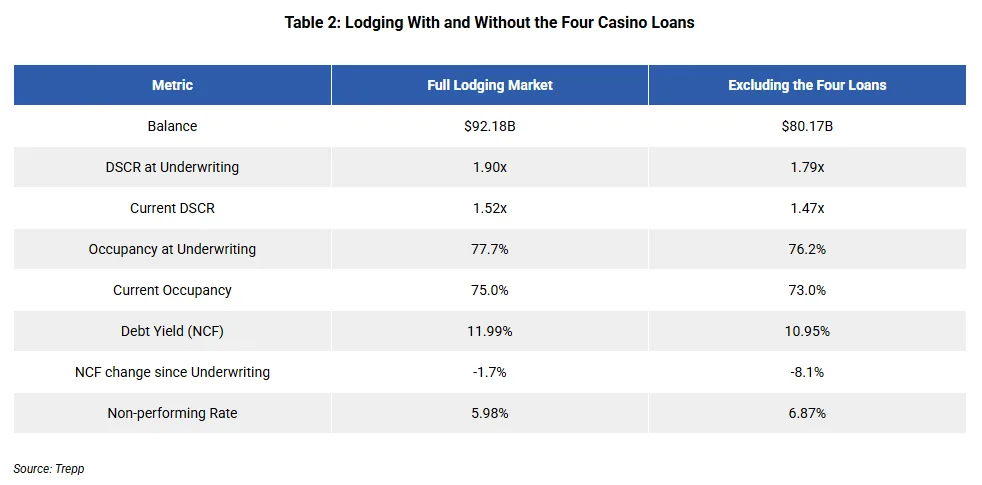
- Excluding them, median net cash flow falls 8.1% below underwriting instead of 1.7%, and the nonperforming rate rises from 5.98% to 6.87%.
- Because sector statistics are balance-weighted, a few large, well-covered loans can obscure deterioration across typical hotel loans, and the casino loans are not representative.
Four Las Vegas casino resort loans are masking cash-flow compression across the securitized lodging market, according to Trepp. The balance-weighted median change in net cash flow since underwriting is negative 1.7% for the $92.18B sector, but it widens to negative 8.1% without the four loans.
The loans total $12.01B, or 13.0% of securitized lodging balance.
Get Smarter about what matters in CRE
Stay ahead of trends in commercial real estate with CRE Daily – the free newsletter delivering everything you need to start your day in just 5-minutes
The Four Loans
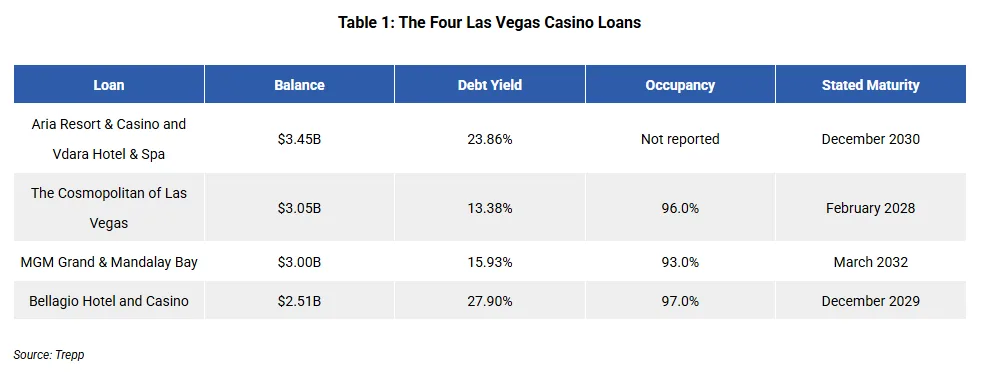
The Aria Resort & Casino and Vdara loan is the largest at $3.45B, with a 23.86% debt yield and a December 2030 maturity. The Cosmopolitan carries $3.05B at a 13.38% debt yield and 96.0% occupancy, maturing in February 2028.
MGM Grand and Mandalay Bay total $3.00B at a 15.93% debt yield and 93.0% occupancy, maturing March 2032. Bellagio holds $2.51B at a 27.90% debt yield and 97.0% occupancy, due December 2029.
What Changes Without Them
Removing the four loans lowers the sector’s median debt yield from 11.99% to 10.95%, and median DSCR at underwriting from 1.90x to 1.79x. Current DSCR moves from 1.52x to 1.47x.
Current occupancy drops from 75.0% to 73.0%, and the nonperforming rate rises from 5.98% to 6.87%.
Why Casinos Are Different
All four loans are current, but casino resorts combine lodging with gaming, entertainment and food and beverage revenue. Their operating profiles differ from conventional hotels.
The Cosmopolitan (originated February 2026) and the Aria and Vdara loan (originated December 2025) have not yet reported post-securitization financials, so their debt yields reflect securitization cash flow.
Why It Matters
Headline lodging statistics can overstate the sector’s health because balance-weighting lets a handful of big loans dominate. Typical hotel loans are showing considerably more deterioration, and earlier Trepp data showed that limited-service hotels lead lodging stress.
The casino loans are well covered and current, but Trepp cautions they do not represent the broader Las Vegas hotel market or lodging nationally.
What’s Next
Watch the first post-securitization financials for the Cosmopolitan and Aria and Vdara loans, and whether other brand-specific trends such as the Hilton and Marriott distress gap show up in the data.