- Soft rents and capital-market pressure have narrowed the gap between market and restricted rents, making market-to-affordable conversion less expensive to execute today than after a recovery.
- Standard Communities closed the roughly $410 million Park Kiely deal in San Jose in 34 days and renovated Lakeside Village in San Leandro without displacing residents.
- Winning conversions takes speed, fluency in tax and subsidy programs, and in-place renovation skill, and the structure can keep market-rate upside on part of a property.
Most institutional capital looking at affordable housing is asking the same question: How do we build more of it? We absolutely need new construction. But at this point in the cycle, investors should also ask how quickly existing market-rate housing can be converted to long-term affordability, and what that costs today.
In many markets, new supply has pressured rents, leasing has softened, and owners are facing maturities or capital partners looking for an exit. That is a difficult environment for a market-rate owner. For an affordable housing converter, it can create one of the most attractive entry points we have seen in years.
Get Smarter about what matters in CRE
Stay ahead of trends in commercial real estate with CRE Daily – the free newsletter delivering everything you need to start your day in just 5-minutes
The gap is the cost
When a market-rate property is restricted to affordable rents, the investor gives up the difference between what the units could earn at market rents and what they can earn under the affordability restriction. That difference is the economic cost of creating affordability. The wider the gap between market and restricted rents, the more return has to be replaced through subsidy, tax relief or other structuring.
When the spread is narrow, the cost of creating affordability falls. That is why timing matters more than people think. Every dollar of rent growth that returns before a conversion is a dollar someone will have to pay for later.
Conversion should complement new construction, not compete with it. Ground-up development adds supply over time. Conversion can preserve existing housing now and, at the right point in the cycle, do it with fewer resources.
Speed is the edge
The economics only matter if you can win the asset. Market-rate sellers are not waiting nine months for an affordable buyer to assemble a capital stack. They want certainty and a clean close.
At Park Kiely in San Jose, a 948-unit community on 32 acres, we completed the approximately $410 million acquisition in just 34 days. The conversion will preserve hundreds of homes for lower- and moderate-income households for 30 years.
That close was possible because the financing and regulatory path were sufficiently developed before the opportunity appeared. If you start learning the public programs, structuring the capital or solving the regulatory side after you have control of the property, you are already behind.
You have to underwrite, structure the public side and close on a timeline that looks like a market-rate buyer. Speed is not a nice-to-have. It is the edge.
The economics have to work for investors, too
Institutional capital is making a real trade. On the restricted units, an investor gives up some market-rate rent growth when the cycle turns. We should not pretend otherwise.
The way to solve for that is with a deeper toolkit. Property-tax exemptions, subsidy contracts and state and local programs can put return back into the deal while keeping rents affordable. Many conventional multifamily operators have never had to learn those programs. Knowing what exists in each jurisdiction, and how to execute it, matters.
The public-sector proposition works for the same reason. When the market-to-restricted spread is smaller, long-term affordability can require fewer resources. Communities can get affordability sooner, along with visible investment in an existing property.
The structure also does not have to be all or nothing. Some transactions can restrict part of a property while leaving the rest market rate. That gives an investor stability on the affordable units and continued upside on the market-rate units as leasing conditions recover.
There is also a back-end question. More predictable cash flow can change how investors value risk at exit. In my view, some of the rent growth given up on restricted units can be offset by the value the market places on stability. Add the current yield created by tax and subsidy tools, and the trade can work on both ends of the investment. I also expect the buyer pool for stable, cash-flowing affordable assets to deepen over time.
The residents win and the benefit grows over time
These are not vacant buildings. The residents are already home.
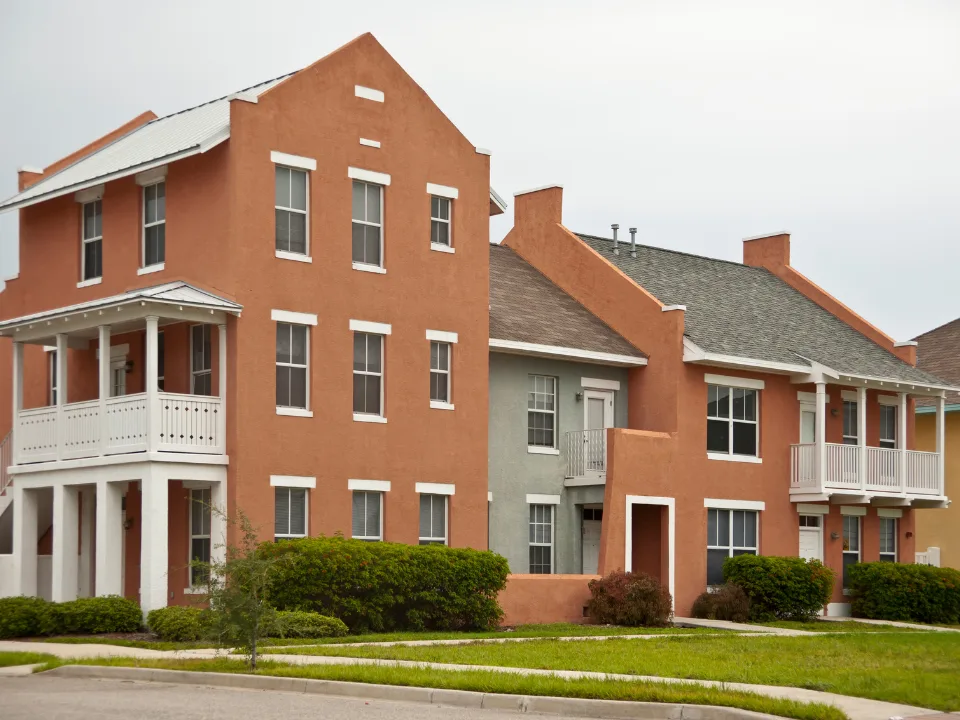
At Lakeside Village in San Leandro, we converted an 840-unit community across 48 residential and amenity buildings with more than 1,400 residents. The property had not undergone significant physical improvements since the late 1960s. We completed an approximately $20 million tenant-in-place renovation without displacing residents.
That requires a different kind of execution. Construction schedules, resident communications, property operations and access have to work as one system. It is one reason we built construction and architecture capabilities around rehabilitation with residents in place. Existing residents should receive the benefit of the renovation, not be moved out for it.
The resident benefit also grows over time. Restricted rents are tied to income limits rather than moving entirely with the market. On day one, the restricted rent may be relatively close to market. Years later, if the surrounding neighborhood becomes more expensive, the difference can be significant. By 2018, rents at Lakeside were approximately $400 below those of similar market-rate properties.
For policymakers, that long-term payoff can be difficult to see on day one. A conversion can create affordability immediately and pair it with improvements residents and communities can see. Over time, the residents who benefit are the ones who are not pushed out as the neighborhood around them becomes more expensive.
The window is the trade
Market-to-affordable conversion is not a shortcut or simply a financing maneuver. To execute it well, you need to know the programs in each jurisdiction, understand how to renovate around residents in place and be able to close at the speed of a market-rate buyer.
But the point in the cycle matters. Soft rents, capital-market pressure and a narrower spread between market and affordable rents can make affordability less expensive to create today than it may be after the market recovers.
For investors looking for an entry point into affordable housing, I think that is the opportunity: buy existing market-rate housing when the gap is small, use the public toolkit to make the restricted economics work, preserve affordability for the long term, and retain market upside where the structure allows it.
The question is whether you want to create that affordability while the gap is small, or later, when you will have to pay more for it.
About the Author
Jeffrey Jaeger is Co-Founder and Principal of Standard Communities, a national affordable housing investment, development and operations platform with approximately $7 billion in assets under management, nearly 30,000 units and more than 200 communities across 22 states and Washington, D.C.