
- Altus Group found that CRE inflation protection varies materially across 16 property subtypes rather than moving uniformly by sector.
- Warehouse and mall properties showed evidence that embedded rent gaps can convert into future income growth through lease rollover.
- Office remained the exception, with rent gaps showing weak or negative relationships to later income even after occupancy controls.
Commercial real estate can hedge inflation, but the mechanism is far less uniform than the sector label suggests. Altus Group’s analysis of lease-level valuation data found that lease rollover determines whether market rent growth becomes realized income. The study covered 91 quarters of valuation data through Q2 2026 and examined 16 subtypes across industrial, retail and office.
Get Smarter about what matters in CRE
Stay ahead of trends in commercial real estate with CRE Daily – the free newsletter delivering everything you need to start your day in just 5-minutes
How Altus Tested the Thesis
Altus used valuation data spanning 91 quarters from Q4 2003 through Q2 2026. The subtype analysis was limited to periods beginning no earlier than 2013, when the cross-section became dense enough for the study. Lease-structure fields were available for space leases measured in SF rather than units or keys. That limited the test to industrial, office and retail, plus 16 subtypes with complete lease series. The analysis was run at both parent-property and subtype levels. Altus then examined whether wider embedded rent gaps were followed by stronger income growth after leases rolled.
Lease Rollover Drives the Hedge
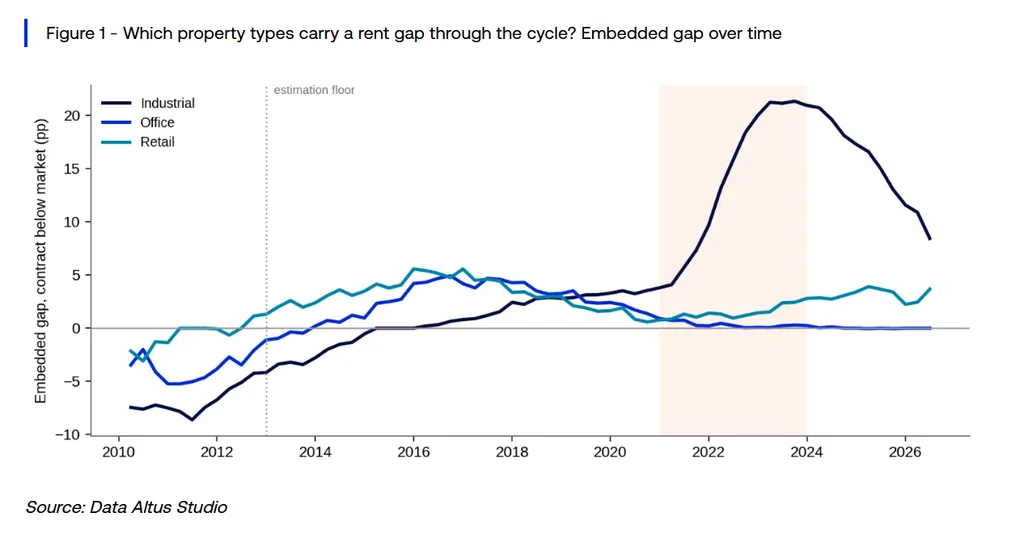
The core idea is simple. Inflation can push market rents above contract rents, creating an embedded rent gap. However, that spread is only potential income until leases expire and reset. A property can show pricing power on paper without converting it into cash flow. Altus therefore tested whether larger rent gaps historically led to stronger income growth after rollover. The study found that conversion appears in select subtypes rather than consistently across entire property categories.
The Details
Industrial produced the clearest split. Warehouse properties showed statistically significant rent-gap conversion, supporting the sector’s reputation as an inflation hedge. Flex properties showed little evidence of the same mechanism.
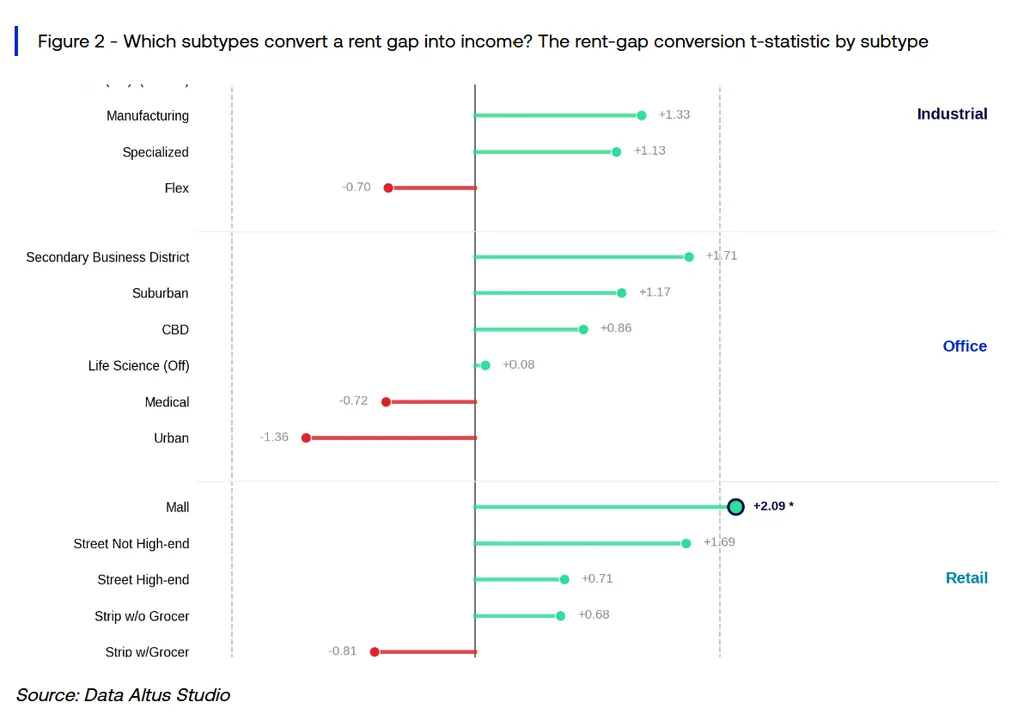
Manufacturing and specialized industrial assets pointed in the same direction as warehouses, but the relationship was less consistent. That distinction supports a narrower view of lease structure as an inflation hedge than a blanket industrial allocation. Altus’ results suggest the warehouse format is doing much of the work behind the broader industrial narrative.
Retail Splits by Format
Retail also behaved differently by subtype. Malls showed evidence that embedded rent gaps can translate into future income growth. Several strip-center formats did not show the same reliable conversion. As a result, two retail assets can face similar inflation and market rent growth but produce very different income outcomes. The difference is whether lease terms and rollover timing allow owners to capture the spread. Viewed only at the parent-sector level, that divergence can disappear inside a relatively neutral retail average.
Office Remains the Outlier
Office showed the weakest pattern. Across office subtypes, larger rent gaps generally did not lead to stronger future income. Altus said the result predates the pandemic and remained visible after controlling for occupancy changes. That finding challenges the assumption that a wide gap between market and in-place rents automatically represents future upside in office portfolios.
Why It Matters
For underwriting, the inflation question becomes asset-specific. Investors and lenders need to assess the size of the market-to-contract rent gap, the frequency of lease rollover and the historical conversion of that gap into income. When all three conditions align, inflation can support operating performance.
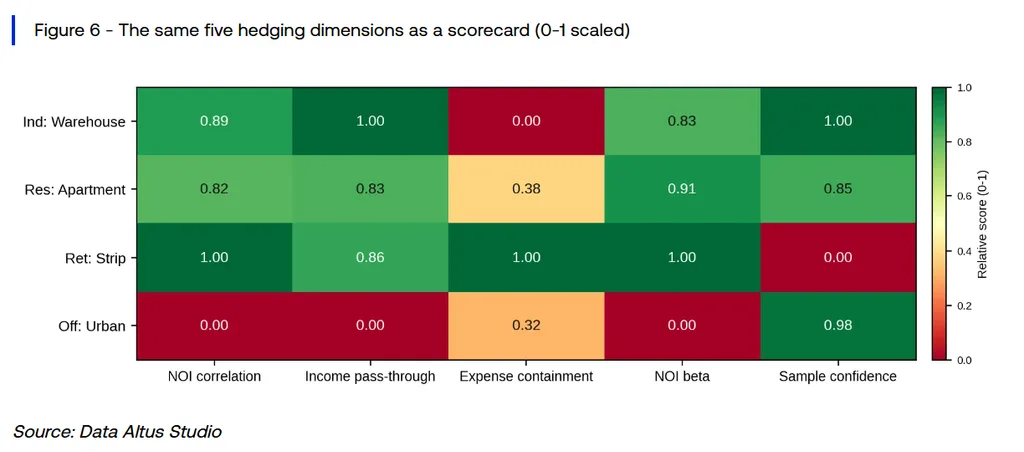
When they do not, higher market rents may never fully reach property cash flow. Altus’ analysis therefore favors lease and subtype analysis over broad sector assumptions. That approach also reduces the risk of treating a visible rent gap as realized upside before lease mechanics prove it can be captured.
What’s Next
The underwriting focus shifts from asking whether a sector benefits from inflation to asking whether a specific lease structure can capture it. Altus frames three questions as central: how large the market-to-contract rent gap is, how often leases roll and whether past rollover converted that gap into income. The strongest hedge is therefore not simply the asset with the widest current spread. It is the asset whose leases have historically turned that spread into cash flow.