- US CLO issuance totaled $43.8B across 97 deals in August, down from $46.4B in July.
- European issuance dropped to €9.7B across 23 deals, with refinancing and resets representing about 70% of volume.
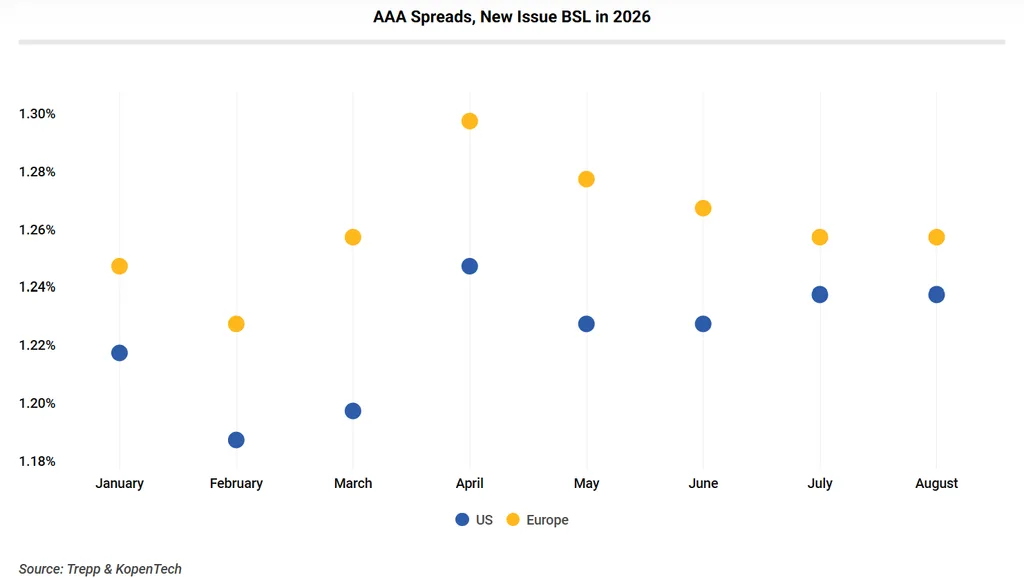
- AAA spreads stayed broadly stable, while US refinancing and reset AAA pricing tightened to 118 basis points.
Trepp’s August market snapshot shows CLO issuance cooled across the US and Europe. US volume reached $43.8B across 97 deals, down from $46.4B in July. European issuance fell more sharply to €9.7B across 23 deals from €15.6B.
Despite the slowdown, US new issuance increased during August. Meanwhile, refinancing and reset activity continued to dominate both markets. AAA spreads also remained largely steady, extending the pricing pattern in place since June.
Get Smarter about what matters in CRE
Stay ahead of trends in commercial real estate with CRE Daily – the free newsletter delivering everything you need to start your day in just 5-minutes
Refinancing Still Dominates Activity
US broadly syndicated loan transactions contributed $38.2B across 86 deals. Middle-market transactions added another $5.6B across 11 deals. New issuance totaled $19B across 40 deals, the highest monthly new-issue total of the three months Trepp showed.
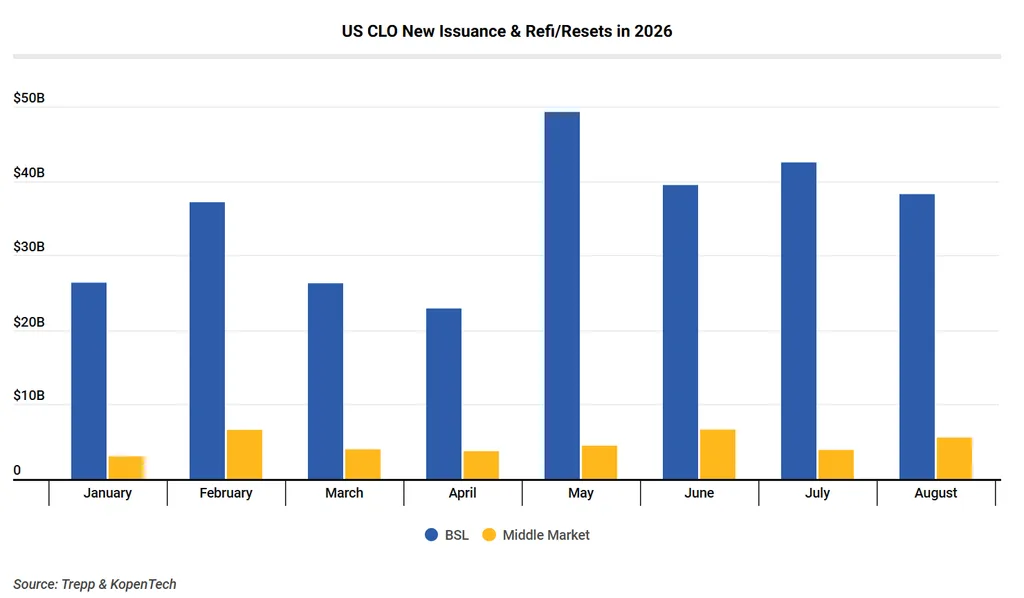
Refinancing and reset activity still led at $24.8B across 57 US deals, representing about 57% of August volume. Resets accounted for $13.7B across 29 deals, while refinancings totaled $11.1B across 28. Combined activity fell from $33.1B in July and $35.3B in June.
The US total declined from $46.4B in July, but new issuance still increased to $19B. That suggests lower refinancing and reset activity drove much of the monthly slowdown. New deal formation held up better than the overall issuance figure suggests.
The Details
European issuance fell from €15.6B across 37 deals in July to €9.7B across 23 deals in August. Refinancing and resets totaled €6.8B across 16 deals, representing about 70% of monthly activity. That share increased from 63% in July, while new issuance fell from 14 deals to seven.
Resets drove most European repricing activity at €5.7B across 13 deals. Refinancings added €1.2B across three transactions. Europe recorded no middle-market activity during August, further concentrating issuance among new BSL deals and existing structures.
US new-issue BSL AAA spreads averaged 124 basis points, unchanged from July and above the 122-basis-point year-to-date average. European new-issue AAAs averaged 126 basis points, also consistent with July. US refinancing and reset AAAs averaged 118 basis points, while European transactions averaged 126 basis points.
Non-call periods exceeded year-to-date averages across every segment Trepp measured. US new issues averaged 2.03 years versus 1.99 years year to date. European new issues averaged 1.69 years compared with 1.56 years year to date.
Reinvestment periods showed a more mixed picture. US new issues averaged 5.05 years against a 5.02-year year-to-date average. European new issues averaged 4.72 years compared with 4.62 years. However, US refinancing and reset periods fell below their year-to-date average.
Why It Matters
The August figures show slower total issuance without a broad pricing shock. New-issue AAA spreads remained flat in both markets, while US refinancing and reset spreads tightened. That combination suggests pricing conditions remained relatively stable despite lower aggregate volume.
Activity also remained heavily weighted toward refinancing and resetting existing structures, particularly in Europe. However, rising US new issuance shows managers continued bringing fresh transactions to market. The pattern sits alongside a broader CRE CLO market recovery that has renewed attention on securitized private-credit structures.
Longer non-call periods also matter for managers and investors. These periods limit how quickly transactions can return for refinancing or resets. August averages exceeded year-to-date levels across every US and European segment Trepp tracked.
What’s Next
US year-to-date issuance reached $320B across 730 deals through August. European year-to-date issuance reached €84.2B across 205 deals. Trepp noted that new-issue pricing remained flat across both markets heading into the final months of 2026.
Squarepoint Capital also appeared to price its first CLO under its own management platform in August. Squarepoint US CLO 1 marks another step in the firm’s expansion into direct CLO management.
Squarepoint has held CLO exposure since 2021 through a capital partnership with Arini Capital Management. Arini priced its first European CLO in 2023 and its first US CLO earlier this year. Squarepoint began building its own platform in 2025 and hired an industry veteran to lead it in January 2026.