


- U.S. CLO issuance slipped to $41.1B across 92 deals from $43.8B in August, while European volume rose to €10.7B and new issuance retook the lead there.
- Refinancings overtook resets in the U.S. for the first time since April, at $15.4B versus $11.9B, and three managers priced debut CLOs during the month.
- AAA spreads tightened in both markets, and lower funding costs are expected to keep driving CLO activity into the fourth quarter, with U.S. year-to-date issuance at $361.1B.
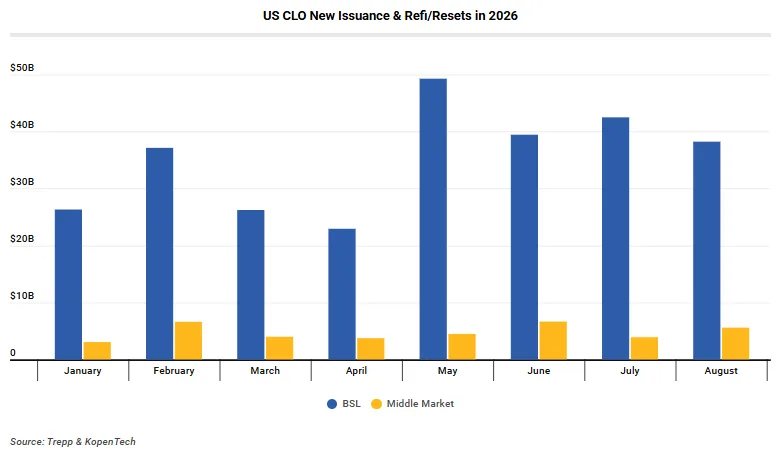
September CLO issuance moved in opposite directions across markets, per Trepp. U.S. volume dipped to $41.1B across 92 deals from $43.8B in August, the weakest month since April.
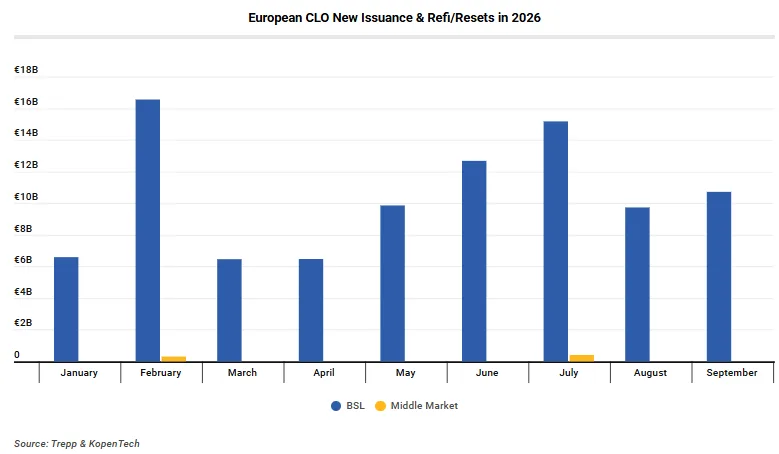
Europe went the other way, with €10.7B across 24 deals, up from €9.7B.
Get Smarter about what matters in CRE
Stay ahead of trends in commercial real estate with CRE Daily – the free newsletter delivering everything you need to start your day in just 5-minutes
Refinancings Take the Lead
Broadly syndicated loan deals supplied $34.3B of the U.S. total across 77 transactions. Middle-market CLOs added $6.8B across 15 deals, their best monthly dollar and deal-count showing of 2026.
New-issue activity dropped to $13.8B across 30 deals, compared with $19.0B across 40 in August, as new BSL deals went from 32 to 21. Repricing carried the month instead.
Refinancings and resets together reached $27.3B across 62 deals, roughly two-thirds of volume. Refis came to $15.4B and edged past resets at $11.9B, the first time that has happened since April. Valuation Research Corporation’s third-quarter update says managers are focused on liability management and expects refis to take a bigger share than in 2025.
Europe Rebounds on New Deals
European new issuance jumped to €7.6B across 17 deals from €2.9B across seven in August, its biggest month since February. That ended a run since June in which repricings led.
Refinancings and resets shrank to €3.1B, about 29% of volume against roughly 70% a month earlier. Resets made up €2.7B, and one refinancing added €0.4B. No middle-market deals priced for a second straight month.
The rebound fit the outlook. Late-August reporting from GlobalCapital said market participants expected European supply to stay strong, possibly setting a record, despite thin arbitrage and soft equity returns.
Spreads Tighten
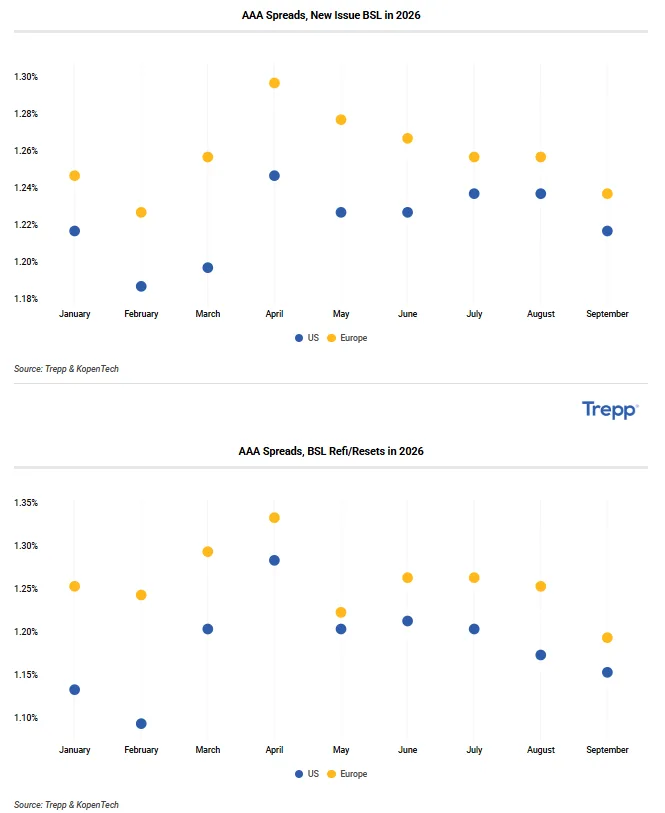
U.S. new-issue AAA tranches priced at an average of 122 basis points over benchmark, two points tighter than August and level with the 2026 average. Refinancing and reset AAAs in the U.S. came in at 116, from 118.
In Europe, new-issue AAA notes priced at 124 on average, four points tighter than August and under the 126 yearly mean. European refi and reset AAAs hit 120, the tightest month of the year, after 126 in August.
Structure and Debuts
Reinvestment windows shortened as managers leaned on refis, which reprice debt without the added reinvestment time a reset provides. In the U.S., refis and resets carried 3.03 years versus 3.61 for the year to date, the briefest of 2026, and their 1.28-year non-call periods were the shortest since February.
Three managers priced first-time CLOs: DS2 Capital’s $510M DS2 CLO 1, Fasanara Capital’s €404M Valey Primus and Kartesia’s Kartesia CLO I, upsized to €459M from a €400M target. Per GlobalCapital, investors demanded a modest premium of roughly 4-5 bps on Fasanara’s AAA notes.
Elsewhere, Anchorage Capital Advisors took over management of 11 U.S. vehicles previously run by ORIX Advisers, about $4.7B of assets, which lifts its platform to 60 vehicles and roughly $26.1B of collateral. Monroe Capital also priced a $398.9M private credit deal, with Deutsche Bank as arranger.
Why It Matters
CLOs are a major buyer of leveraged loans, so cheaper liabilities feed through to borrowers. The pivot to refis shows managers trimming costs on existing vehicles, much like the bridge-to-bridge loans that are buying time for stretched CRE borrowers.
Fresh managers entering the market also signals capital formation continues despite the monthly dip.
What’s Next
Year to date, U.S. issuance sits at $361.1B across 822 deals, and Europe at €94.9B across 229. Trepp points to lower funding costs as a key driver as the fourth quarter begins.