- National average rent for a one-bedroom reached $1,665 in September, up 0.8% from a year earlier, with a two-bedroom at $1,932 and vacancy at 7.8%.
- Chicago (+5.7%), Brooklyn (+5.2%) and New York (+4.2%) led city gains, while San Antonio, Katy and Las Vegas posted the steepest drops, none worse than 0.9%.
- Supply is the swing factor: Las Vegas rents are slipping on new deliveries, while Cleveland’s office-to-apartment conversions are lifting luxury rents downtown.
The national average rent was $1,665 per month for a one-bedroom in September, up 0.8% from September 2025, according to the Apartments.com Rent Report.
Two-bedrooms averaged $1,932, and the national vacancy rate stood at 7.8% at the start of autumn.
Get Smarter about what matters in CRE
Stay ahead of trends in commercial real estate with CRE Daily – the free newsletter delivering everything you need to start your day in just 5-minutes
Chicago and New York Lead Gains
Chicago topped the report’s list of September increases at 5.7%, followed by Brooklyn (5.2%), New York (4.2%), Hollywood, Fla. (4.2%) and Pittsburgh (4.1%).
Chicago has been in the top five since March 2025, when its vacancy fell to the lowest level since 2000. Vacancy there is now about 5%, 2.8 percentage points below the national average.
The city table shows the same pull in the Northeast. Manhattan one-bedrooms average $4,210, up 3.3% year over year, and Boston averages $3,584, up 3.1%.
Jersey City ($3,318) and Hoboken ($3,913) also climbed more than 3% over the year.
Steady Gains in Mid-Priced Markets
Several lower-cost metros posted solid year-over-year increases. Charleston, S.C. rose 3.4% to $1,923, Milwaukee gained 2.5% to $1,224 and Kansas City climbed 2.1% to $1,256.
Philadelphia rose 2.1% to $1,777, and Minneapolis added 1.9% to $1,412.
Texas Metros and Las Vegas Slip
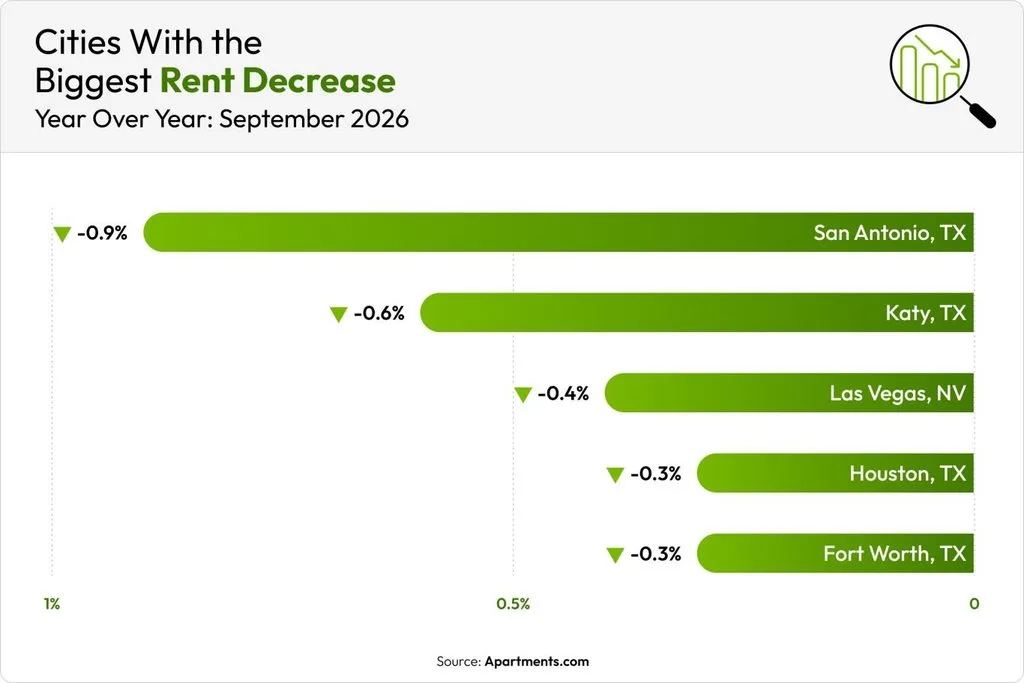
The report’s biggest September declines were San Antonio (-0.9%), Katy (-0.6%), Las Vegas (-0.4%), Houston (-0.3%) and Fort Worth (-0.3%). Apartments.com says declines have cooled now that moving season is over, with none of the five topping 1%.
Las Vegas is the only city outside Texas on the list. More than 2,000 new units entered the market in the first half of 2026.
The city table shows wider year-over-year losses in several Sun Belt markets: Las Vegas (-2.3%), San Antonio (-2.1%), Phoenix (-1.4%) and Houston (-1.2%). Denver and Charlotte each fell 1.1%.
Florida and the West Coast Diverge
Florida markets split in the city table. Miami rose 1.7% to $2,255 and Jacksonville gained 1.0% to $1,309, while Tampa (-0.8%), Fort Lauderdale (-0.9%) and Orlando (-0.2%) slipped.
On the West Coast, San Diego rose 1.1% to $2,440, Portland gained 1.0% to $1,531 and Seattle edged up 0.5% to $2,129. Sacramento fell 0.9% to $1,574, and Los Angeles was flat at $2,198.
States Split on Rent Growth
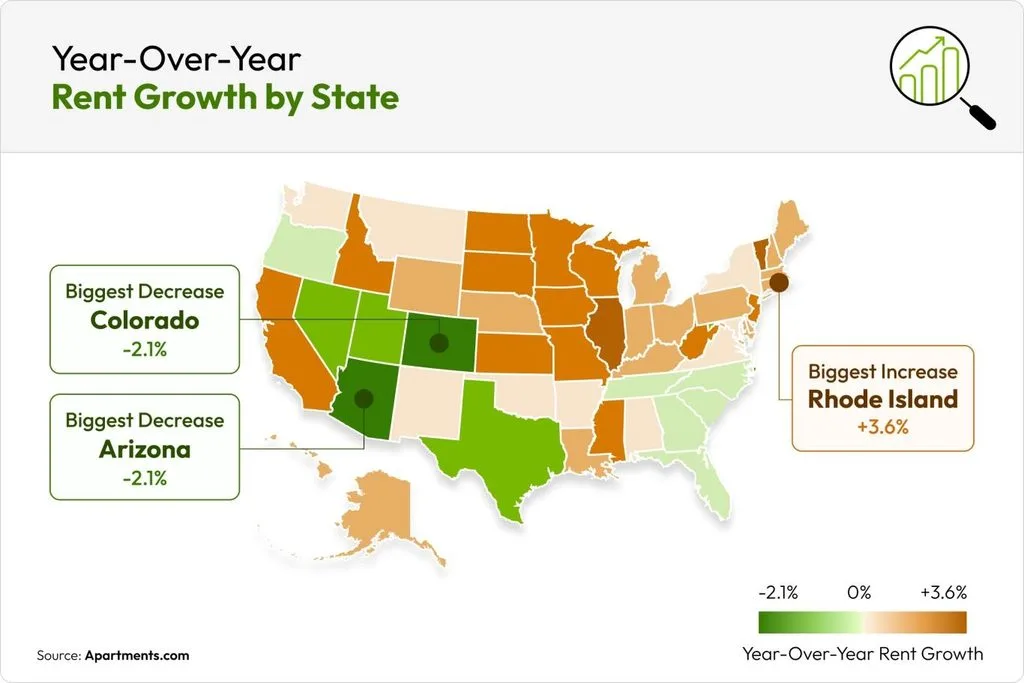
Rhode Island posted the largest state increase at roughly 3.5%, followed by Illinois (3.4%) and Idaho (2.9%). Arizona and Colorado tied for the steepest decline at 2.1%.
Oklahoma has the cheapest rent in the country at $921 per month, up 0.9% from a year earlier. Arkansas and West Virginia round out the three least expensive states.
Cleveland’s Conversion Wave
Cleveland rents rose 1.8% to $1,379 for a one-bedroom as construction wrapped up on luxury communities downtown.
CoStar’s Veronica Miniello said much of the new supply comes from office-to-apartment conversions and new builds in developing neighborhoods. Cleveland’s office vacancy is 11%, and financing for the Erieview Tower redevelopment was recently added to the conversion pipeline.
Why It Matters
Rent performance is hyperlocal. The same report shows Chicago rising nearly 6% while San Antonio and Las Vegas fall, and supply is the common thread.
That fits other reads on the market, including a separate look at how national rent dips as vacancy eases.
The report draws on CoStar Group Market Trend data, combined with Apartments.com internal data and public records. It covers more than 2,400 cities, including the top 80 national markets.
What’s Next
Cleveland’s elevated multifamily vacancy means renters may not feel the benefit of the redevelopment pipeline yet.
Watch whether the rent growth outlook improves in supply-heavy Sun Belt markets as deliveries slow.