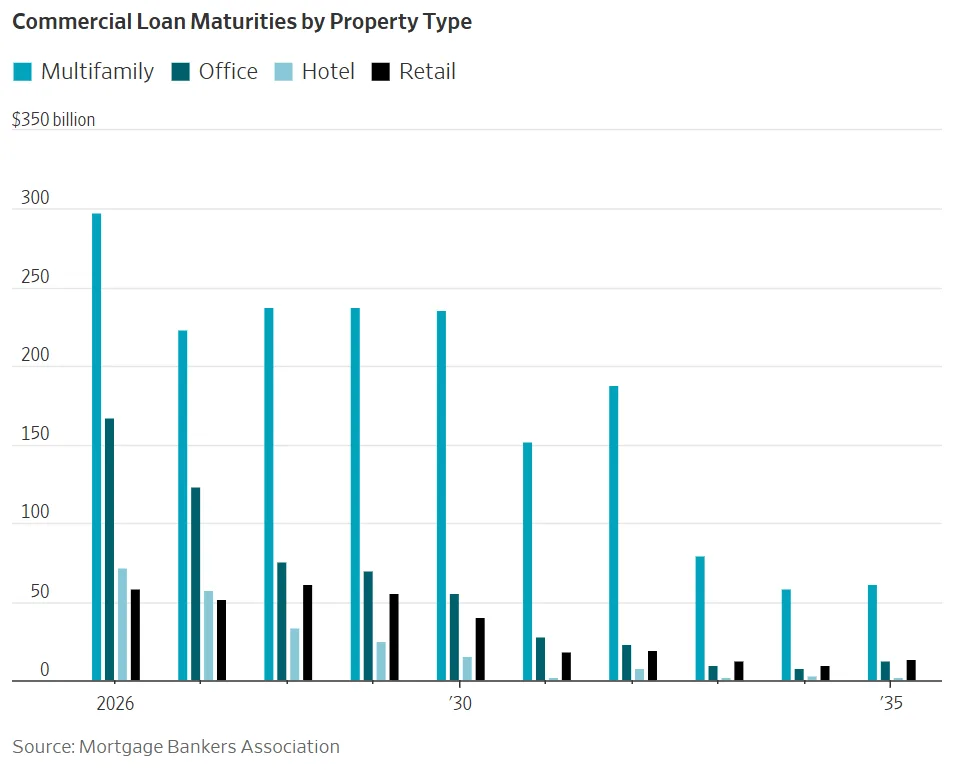
- Apartment landlords face about $757B of debt maturities from 2026 through 2028, including nearly $300B this year.
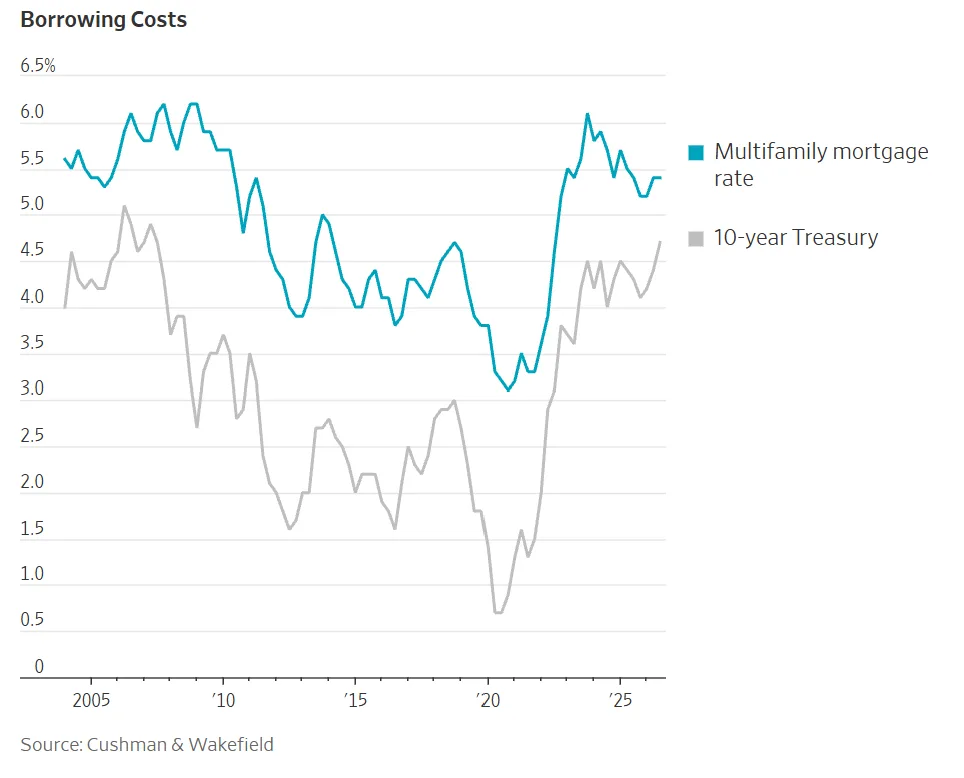
- Refinancing rates near 6% are replacing pandemic-era apartment mortgages around 3%, pressuring owners, values, and development plans.
- CMBS multifamily delinquencies reached 7.1% this year as lenders became more aggressive with borrowers that had relied on extensions.
Apartment landlords are entering a concentrated refinancing cycle with borrowing costs far above pandemic-era levels. The Wall Street Journal reviewed the apartment debt market and found more than $1.8T of apartment debt due over the next decade. About $757B matures from 2026 through 2028. That is the largest near-term total among major CRE sectors. Nearly $300B is due in 2026 alone, following a record $310B in 2025.
Get Smarter about what matters in CRE
Stay ahead of trends in commercial real estate with CRE Daily – the free newsletter delivering everything you need to start your day in just 5-minutes
Rising Rates Reverse Pandemic-Era Math
Multifamily became a favored investment during 2020 and 2021 as apartment mortgage rates fell to roughly 3%. Rents were rising at double-digit rates nationwide. Meanwhile, office, retail, lodging, and senior housing faced pandemic-era disruption. That backdrop encouraged heavy borrowing and aggressive apartment acquisitions. The economics changed as new supply flooded several Sun Belt markets. Phoenix, Denver, Atlanta, and Austin were among the cities hit with new luxury inventory and weaker occupancy pressure.
The Details
Owners refinancing today can face rates near 6%, roughly double the 3% financing available five years ago. TruAmerica Multifamily Investments CEO Bob Hart described that reset at a Raleigh property. Its 3.5% loan is coming due. Keeping the asset would require a refinance near 6% and a large equity contribution. Hart is considering a sale instead.
Other owners are selling at losses, handing properties to lenders, or restructuring balance sheets to absorb higher mortgage payments. Developers are also pulling back on new construction and pursuing distressed acquisitions instead.
Lenders Push Harder
For years, borrowers survived because lenders extended loans while both sides waited for stronger rents and lower rates. That strategy has not delivered the expected relief. Bain Capital real estate head Ryan Cotton said creditors are becoming more aggressive. Pressure is no longer limited to smaller syndicators. Blackstone defaulted in June on a $90M loan tied to a North Dallas apartment building acquired in 2021. S2 Capital has accumulated $400M in defaults across its Sun Belt apartment portfolio. The firm plans to sell six defaulted properties for $290M. It is also working to refinance hundreds of millions in additional distressed loans.
Tenant Pressure Can Follow
Financial strain can also reach renters. The source notes that owners may raise rents, add fees, or reduce repairs to cover debt costs. The Tenant Union Federation has organized rent strikes at distressed properties where landlords deferred maintenance or increased rents. That creates an operating risk beyond the balance sheet. Higher debt service can collide with tenant pushback when owners try to recover refinancing costs through property operations.
Why It Matters
Stress is becoming more visible in credit metrics and property values. A Morgan Stanley report put multifamily CMBS delinquencies at 7.1% this year, up from 1% in October 2023. That was the largest increase among major property types. Trepp said about 3% of non-extendable loans maturing this year are in distress. That is the highest share in five years. Green Street said apartment values fell about 3.5% in the past month. Values remain more than 20% below their 2022 peak. The refinancing squeeze is also reshaping multifamily distress as lenders become less willing to extend troubled loans.
Capital Starts Moving
The debt reset is already influencing strategy across the sector. AvalonBay Communities and Equity Residential agreed in May to combine in a $69B megamerger. The companies said part of the rationale was to rely less on expensive debt and fund more projects from revenue. Cash-rich buyers are also moving toward foreclosures and lender-controlled assets. Cityview said it is buying directly from lenders, something the firm had not done in years. It is acquiring a renovated Dallas-area complex at roughly a 40% discount after foreclosure.
What’s Next
The next phase will depend partly on rent growth and lender appetite. CoStar expects rents to increase 1.9% by year-end, up from a prior 0.5% forecast. Better rent growth could improve property cash flow. It could also make lenders more willing to take back assets and wait for recovery. For owners with near-term maturities, the immediate choices remain refinancing, adding equity, selling, or negotiating a lender solution.