




- Insurance lenders posted the largest LTV increase of any CRE lender group in the first half of 2026, rising 2.5 percentage points to 62.7%.
- Private equity ownership of insurers and a pivot into private credit and data centers are pushing carriers into newer, sometimes riskier bets.
- Insurer-held CRE loans face $44B in maturities in 2027 and more than $55B in each of the next two years, with rates expected to stay high or rise.
Life insurers, long among the most conservative CRE lenders, are making riskier loans as they increase lending volume, according to Bisnow.
Carriers are raising leverage and deepening exposure to sectors like data centers just as capital costs keep climbing.
Get Smarter about what matters in CRE
Stay ahead of trends in commercial real estate with CRE Daily – the free newsletter delivering everything you need to start your day in just 5-minutes
Leverage Creeps Higher
Across all lender types, loan-to-value ratios reached 65.9% in the first half of 2026, up from 64.2% a year earlier. Investor-driven lenders carry the highest ratio at 69.5%.
Insurance lenders posted the largest jump of any group this year, up 2.5 percentage points to 62.7%, according to MSCI.
MSCI’s Jim Costello said insurance lenders were traditionally the most conservative underwriters. That is changing through riskier commercial mortgages and CMBS loans, and through a broader range of investment types.
Private Equity Changes the Playbook
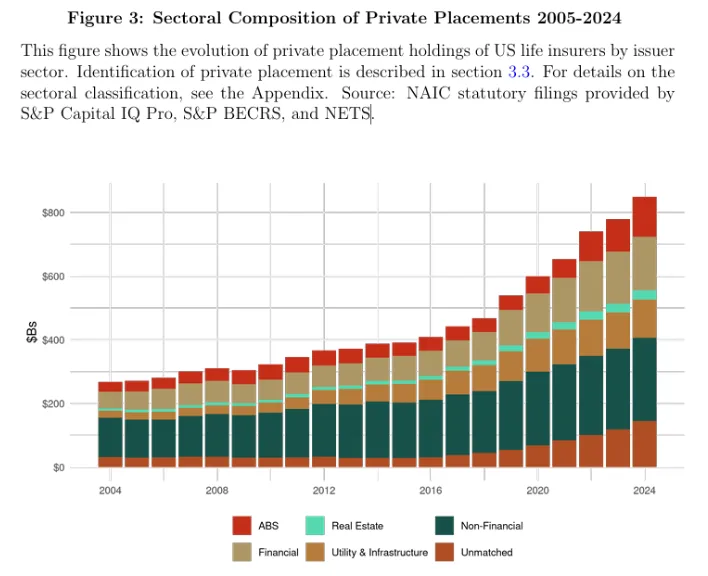
A surge in private equity acquisitions of insurers has pushed the companies into newer bets, including private credit, per a Federal Reserve Bank of Chicago study. Blackstone bought Allstate Life for $2.8 billion in 2021, and Brookfield Reinsurance bought American National for $5.1 billion.
Private credit tied to real estate has largely avoided the wave of defaults that has hit other corners of that market, though some deals have still raised eyebrows.
Global Finance reported more than $75 billion in insurance M&A between Apollo’s 2022 Athene deal and September 2025. Insurers have also lifted private credit holdings to $1.2 trillion.
Maturities and Data Centers
Life insurers hold more than 95% of the insurance industry’s commercial loans and carried $940 billion of CRE exposure in 2024, including mortgages and CMBS. Moody’s projected the total would reach $960 billion for 2025, with roughly 2% annual growth.
Insurer loans face $44 billion in maturities in 2027, $55.5 billion in 2028 and $57.3 billion in 2029, per MSCI. About 30% of insurance lending to real estate went to data center projects last year, a segment some analysts say is growing too quickly.
Why It Matters
MRV Associates’ Mayra Rodriguez Valladares called the trend a potential real problem and said rates could rise further or hold where they are. That would raise default odds for borrowers now compared with January, she said, even as private lenders compete for the same deals.
Valladares said insurers have lent heavily to real estate while also investing in private equity and other private credit to try to make more money. The market sees that exposure, she said, which explains the sudden concern about insurance companies.
Borrowers are struggling, she added, because they now need to pay insurers more than they expected years ago.
KKR’s Matt Salem sees opportunity instead, arguing the repricing of real estate assets favors senior secured CRE debt in insurance portfolios.
What’s Next
Regulators are paying attention. Sen. Elizabeth Warren asked the National Association of Insurance Commissioners last month about oversight of insurers’ private credit bets after two Guggenheim-linked insurers reclassified $20 billion of investments as affiliated transactions.
Warren wrote that if an insurer fails because of weak valuations and loan underwriting in private credit, policyholders could lose benefits they paid premiums to secure.
The NAIC responded that it will tighten its assessments of private credit and complex investments and has opened a review of insurers’ data center investments.