- An Eaton Vance-managed fund acquired Foundry on 19th and Ellison Heights, two luxury communities with a combined 436 units, from Greystar.
- Both properties opened in 2021 on the same Greater Heights block, with units ranging from 622 to 2,218 square feet and a 12-story tower at Ellison.
- The deal extends Eaton Vance’s Houston buildout as institutional buyers target infill submarkets where occupancy and rents outperform the broader metro.
An Eaton Vance fund has acquired two luxury communities totaling 436 units in Houston’s Greater Heights from Greystar, according to Multi-Housing News, citing Yardi Matrix data.
The deal adds a pair of newer Houston Heights apartments to Eaton Vance’s growing Houston portfolio. Pricing was not disclosed.
Get Smarter About What Matters in Texas
Subscribe to our free newsletter covering the biggest commercial real estate stories across Texas — delivered in just 5 minutes.
Two 2021 Deliveries
Both properties delivered in 2021. Texas Department of Licensing and Regulation filings estimate development costs of $72 million for the 284-unit Foundry on 19th.
For the 152-unit Ellison Heights, Fifth Third Bank provided an $87.8 million construction loan in 2019, per Yardi Matrix.
The Details
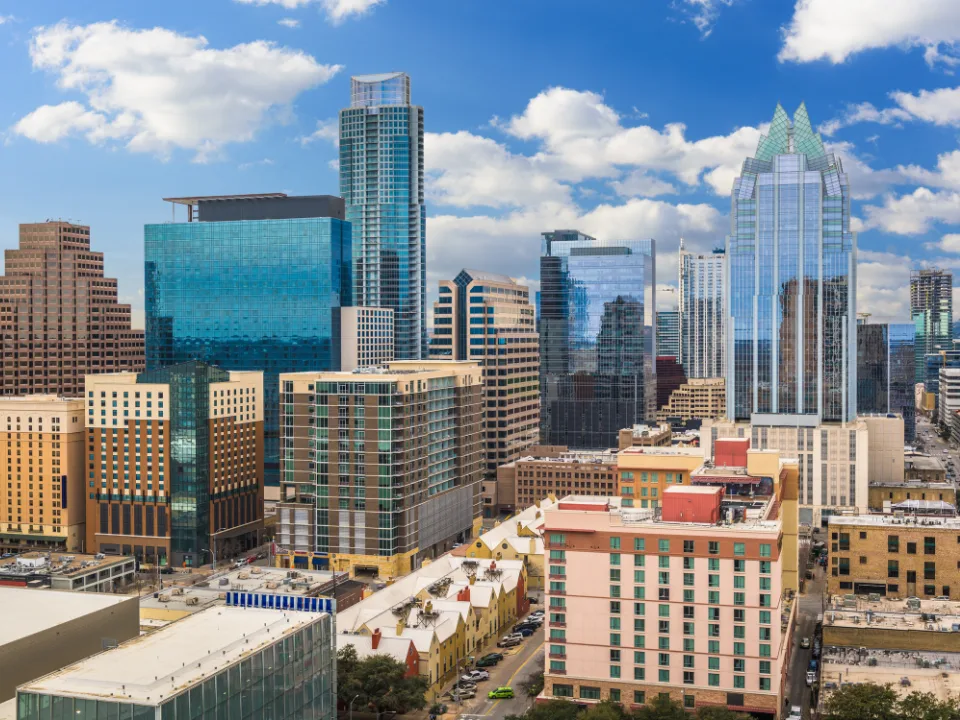
The two communities share a city block at 555 W. 19th St. and 510 W. 20th St., about five miles northwest of downtown Houston. Foundry rises five stories, while Ellison stands 12 stories, including a three-level concrete garage.
Units range from one to three bedrooms, including penthouses, spanning 622 to 2,218 square feet. Both properties offer coworking space, clubrooms, and pool terraces.
The Heights Outperforms Houston
The Heights posted 92.1% occupancy in June 2026, compared with a Houston market average of 88.9%, according to Cushman & Wakefield. Average rents in the submarket reached $1,664, 26.8% above the metro figure.
That outperformance comes as multifamily rent growth spreads across more major U.S. metros, making well-located Class A product in Sun Belt infill neighborhoods a target for institutional capital.
Why It Matters
Eaton Vance’s Real Estate Investment Group manages more than $10 billion in commercial real estate, including over 30,000 apartment units, per its website. Morgan Stanley acquired Eaton Vance for $7 billion in 2021.
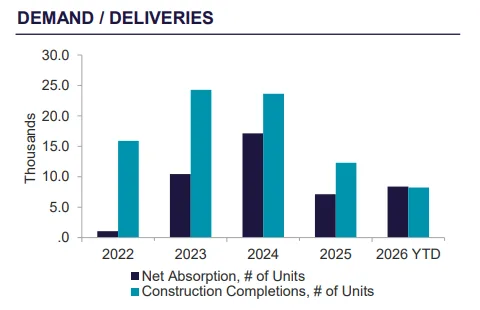
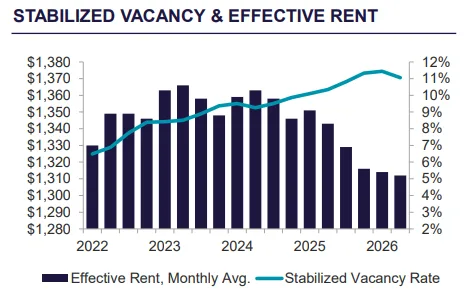
The firm is doubling down on Houston, where a shrinking construction pipeline and steady demand are improving the outlook for owners. Deals like this reflect how institutional ownership continues to expand across the U.S. apartment market.
What’s Next
Earlier in 2026, Eaton Vance bought Elite 99 West, a 360-unit, 2016-built community in Katy, from Electra America. With two more Houston deals now in hand, expect the firm to keep hunting in the metro.
For Greystar, the sale is an exit from two stabilized assets roughly five years after they opened, and a data point for sellers weighing Houston’s newer Class A product.