


- Trepp counts $1.82B of securitized manufactured housing loans reaching hard maturity from November 2026 to December 2027, with no delinquency and nothing in special servicing.
- Fannie Mae and Freddie Mac hold 93% of the balance, and only $45.2M carries a debt yield below 8%, so thin coverage is rare across the cohort.
- Freddie Mac’s manufactured housing maturities show a 12.1% median debt yield against 9.5% for conventional multifamily, pointing to an easier refinancing runway.
None of the $1.82B in securitized manufactured housing loans heading for hard maturity through 2027 is delinquent, according to Trepp.
A hard maturity means no extension options remain, so borrowers must repay or negotiate with the lender. Trepp’s cohort covers November 2026 through December 2027.
Get Smarter about what matters in CRE
Stay ahead of trends in commercial real estate with CRE Daily – the free newsletter delivering everything you need to start your day in just 5-minutes
Agencies Own the Wall
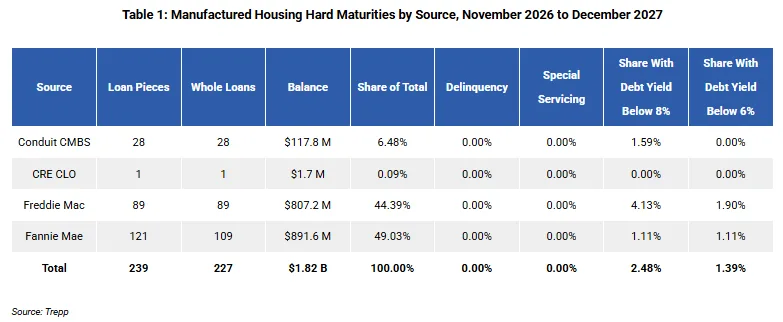
Fannie Mae loans account for $891.6M, or 49%, and Freddie Mac for $807.2M, or 44%. Conduit CMBS makes up $117.8M, and one CRE CLO loan adds $1.7M.
The cohort covers 239 loan pieces across 227 whole loans. No loan is late or with a special servicer.
Thin Coverage Is Rare
Just $45.2M of the balance has a debt yield under 8%, and $25.3M, or 1.39%, is under 6%. Every one of those loans is current.
Trepp left out loans already in foreclosure or REO, so the cohort isolates near-term refinancing risk.
Versus Conventional Multifamily
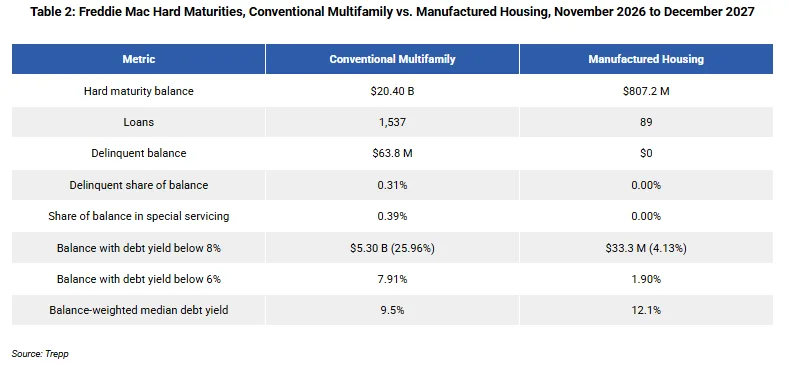
Within Freddie Mac’s book, 4.13% of manufactured housing maturities show debt yields under 8%, versus 25.96% of conventional multifamily’s $20.40B. The median debt yield is 12.1% for manufactured housing and 9.5% for conventional apartments.
Conventional multifamily has 0.31% of its balance delinquent. Manufactured housing has none.
Zoom Out
Trepp ran a similar test on another niche. We reported that seniors housing maturities total $2.24B across 156 loans, with 1.75% delinquent and 14.47% showing debt yields under 8%.
Why It Matters
Manufactured housing looks like the safe corner of the maturity wall, which matters to the investors buying it. Institutional ownership is also drawing political attention. We covered how House Democrats asked Brookfield to limit rent increases and evictions at Yes Communities, with a Nov. 20 deadline to respond.
Strong credit may help owners refinance, but pressure on tenant protections could shape how big investors approach the sector.
What’s Next
Trepp says the cohort faces a relatively clean runway. Watch for Brookfield’s response to Congress after Nov. 20.