




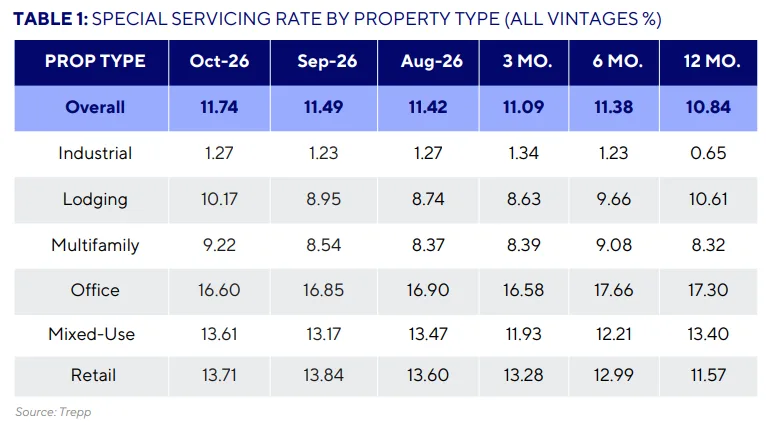
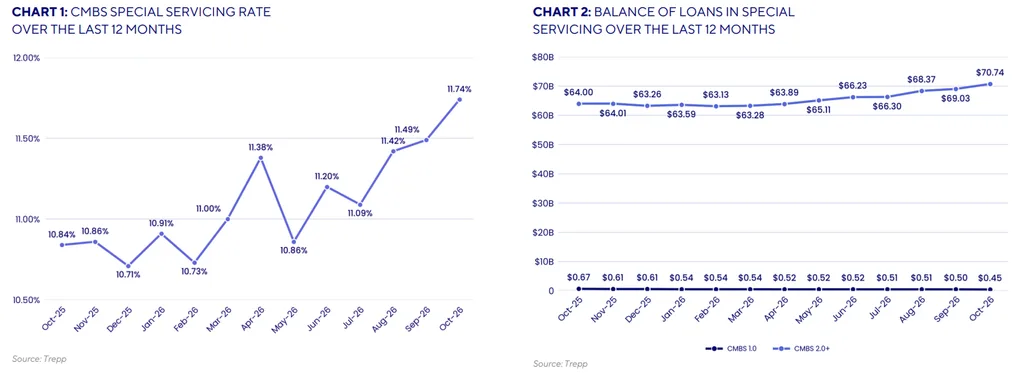
- The Trepp CMBS special servicing rate rose 25 basis points to 11.74% in October, up 90 basis points from a year earlier and the highest reading since December 2012.
- Lodging made up 37% of the $3.01 billion of new transfers, led by the $745.7 million Project Prime hotel portfolio loan and the $517.7 million, Texas-heavy Blackjack apartment portfolio.
- Maturity pressure, not just weak operations, is steering loans into servicing, and hotels and apartments are now carrying more of that stress than office or retail.
Trepp says the special servicing rate on CMBS loans hit 11.74% in October, up 25 bps in a month and the worst reading since December 2012.
The rate is 90 bps above a year ago. Some $3.01B of loans moved into special servicing across 46 loans, up 14% from September.
Get Smarter about what matters in CRE
Stay ahead of trends in commercial real estate with CRE Daily – the free newsletter delivering everything you need to start your day in just 5-minutes
Lodging Leads the Surge
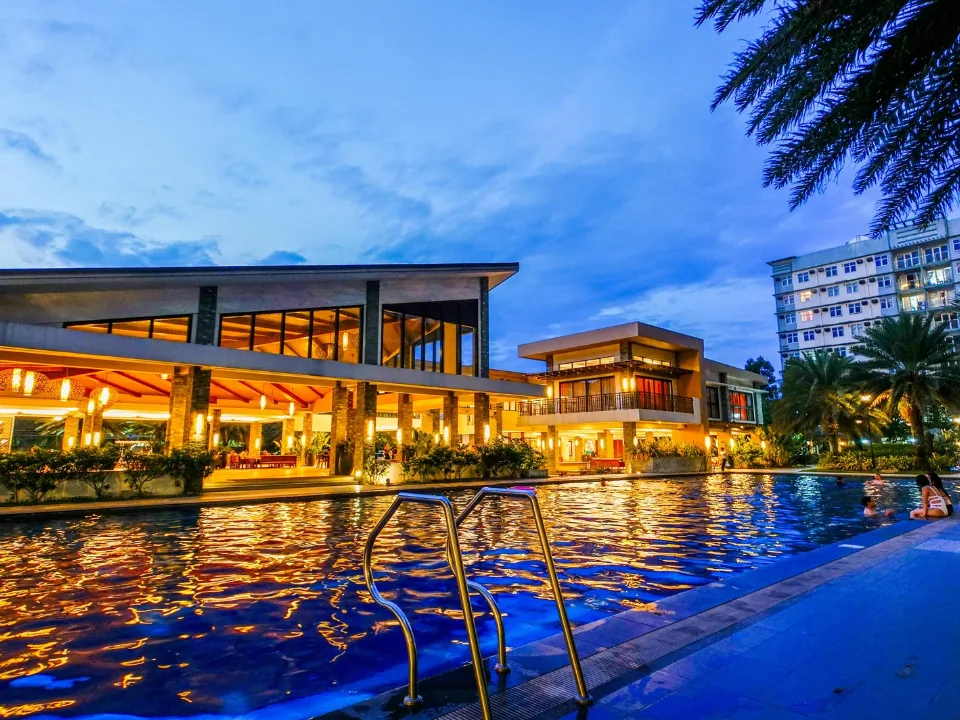
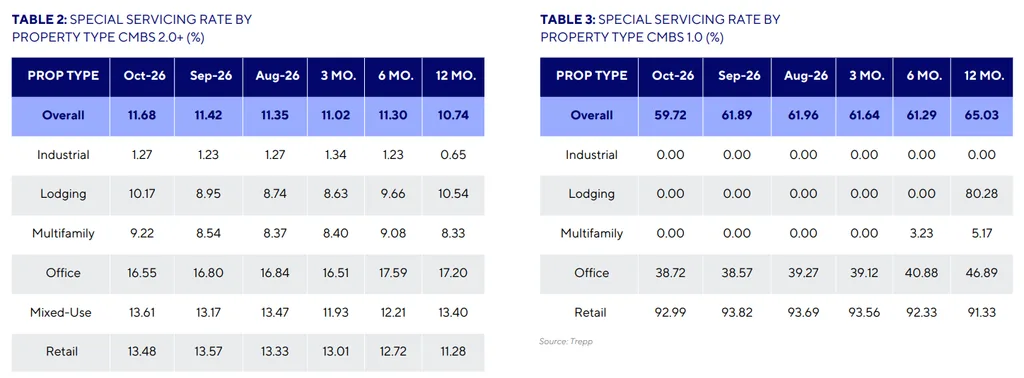
Hotels made up 37% of the new transfers, and the lodging rate jumped 122 bps to 10.17%.
The biggest was Project Prime, a $745.7M loan on 84 hotels and 7,993 rooms. It matures Dec. 6 and moved over because a payment default looked imminent. Occupancy is 77%, and net cash flow for the year to June was $79.55M, covering debt service 1.25 times. A June 2023 appraisal valued the portfolio at $987.1M.
The $302.2M Hyatt Regency Waikiki Beach Resort & Spa in Honolulu also transferred.
Apartments and Mixed-Use Follow
Next came the $517.7M Blackjack Portfolio, which covers 21 apartment properties with 6,671 units, mostly in Texas. The floating-rate loan hit its fully extended maturity on Oct. 9.
Multifamily’s rate rose 69 bps to 9.22%. Mixed-use climbed 44 bps to 13.61%, helped by the $285M Gateways loan in Newark, N.J. Roughly 45% of the dollars in those bigger loans moved because a balloon payment or maturity was about to be missed.
Office and Retail Ease
Office improved by 25 bps to 16.60%, and retail eased 13 bps to 13.71%. Industrial edged up four bps to 1.27%.
Exits slowed. About $1.53B across 38 loans left special servicing, down 22% from September. The largest was the $350M loan on 225 Bush, a 579,987 SF San Francisco office building, where the lender sold the note and took the building back through a Sept. 24 deed-in-lieu, at a price far above its $153M 2025 appraisal.
Zoom Out
Special servicing isn’t the same as delinquency. Trepp’s CMBS delinquency rate fell 15 bps to 7.87% in October, which we covered, even as retail, office and multifamily readings rose.
Together, the two measures show a market where headline relief can hide pockets of stress.
Why It Matters
Loans are landing in special servicing because floating-rate and bullet loans can’t refinance at today’s rates. Apartments are next in line, with multifamily maturities reaching nearly $250B through 2028, per Yardi Matrix data we covered earlier this month.
Hotel owners with near-term maturities face the same refinancing math.
What’s Next
Watch Project Prime’s Dec. 6 maturity. How servicers resolve it will signal how much value lenders can recover on large lodging portfolios.