
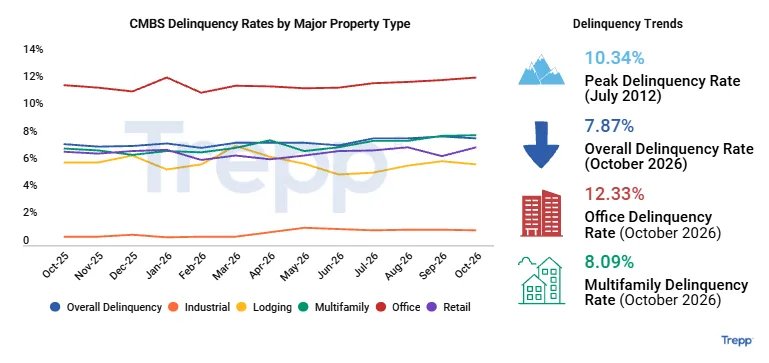
- The Trepp CMBS delinquency rate fell 15 basis points to 7.87% in October from 8.02% in September, largely because a $975 million showroom loan in High Point and Las Vegas returned to current status.
- Retail rose 63 basis points to 7.21%, office rose 17 to 12.33% and multifamily rose five to 8.09%, while lodging fell 24 to 5.94% and industrial slipped four to 1.10%.
- Office led new delinquencies, including a $384.3 million Los Angeles loan, so the headline decline masks continued stress in three of the five major property types.
Trepp’s CMBS delinquency rate slid to 7.87% in October, a drop of 15 basis points, but the improvement hides worse readings in three of five property types.
One loan did most of the work. A $975 million showroom portfolio loan, tied to High Point and Las Vegas, returned to current status, pulling the rate down from September’s 8.02%.
Get Smarter about what matters in CRE
Stay ahead of trends in commercial real estate with CRE Daily – the free newsletter delivering everything you need to start your day in just 5-minutes
Retail and Office Move Up
Retail posted the month’s biggest increase. Its delinquency rate reached 7.21%, up 63 bps. Meanwhile, office climbed 17 bps to 12.33%, the highest rate of any property type. Multifamily also edged up 5 bps to 8.09%.
Lodging and Industrial Improve
By contrast, lodging improved to 5.94%, down 24 bps. Industrial also eased 4 bps to 1.10%. It remains by far the lowest rate among the property types.
Office Leads New Troubles
The largest new delinquencies included a $384.3 million Los Angeles office loan. Another was a $210 million apartment loan in the Bay Area.
Trepp also identified five major new cases. They included office towers in Chicago, Los Angeles and Washington. The list also featured a D.C.-and-Northern-Virginia office portfolio and a New Orleans hotel.
Zoom Out
Multifamily stress has continued to build throughout the year. In our brief on multifamily CMBS delinquencies, the MBA reported a 7.28% rate for Q1 2026. That marked a 70-basis-point increase from the prior quarter. Meanwhile, high rates continued to stall refinancing.
Trepp’s 8.09% reading uses a different loan pool and methodology. Therefore, the figures aren’t directly comparable. Still, both point to mounting pressure.
Why It Matters
A lower headline rate can hide underlying distress. For example, removing one large cure reveals a mixed picture. Three of the five property types worsened in a single month.
Office remains the biggest problem, with a rate above 12%. Moreover, it accounted for most of the month’s new trouble.
What’s Next
Trepp’s full report breaks out CMBS 1.0 and 2.0+ readings. Next, watch November’s data to see whether retail’s sharp increase continues.