




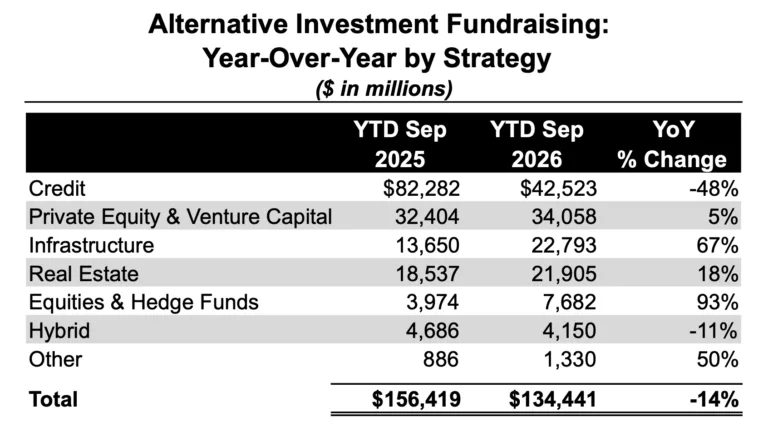
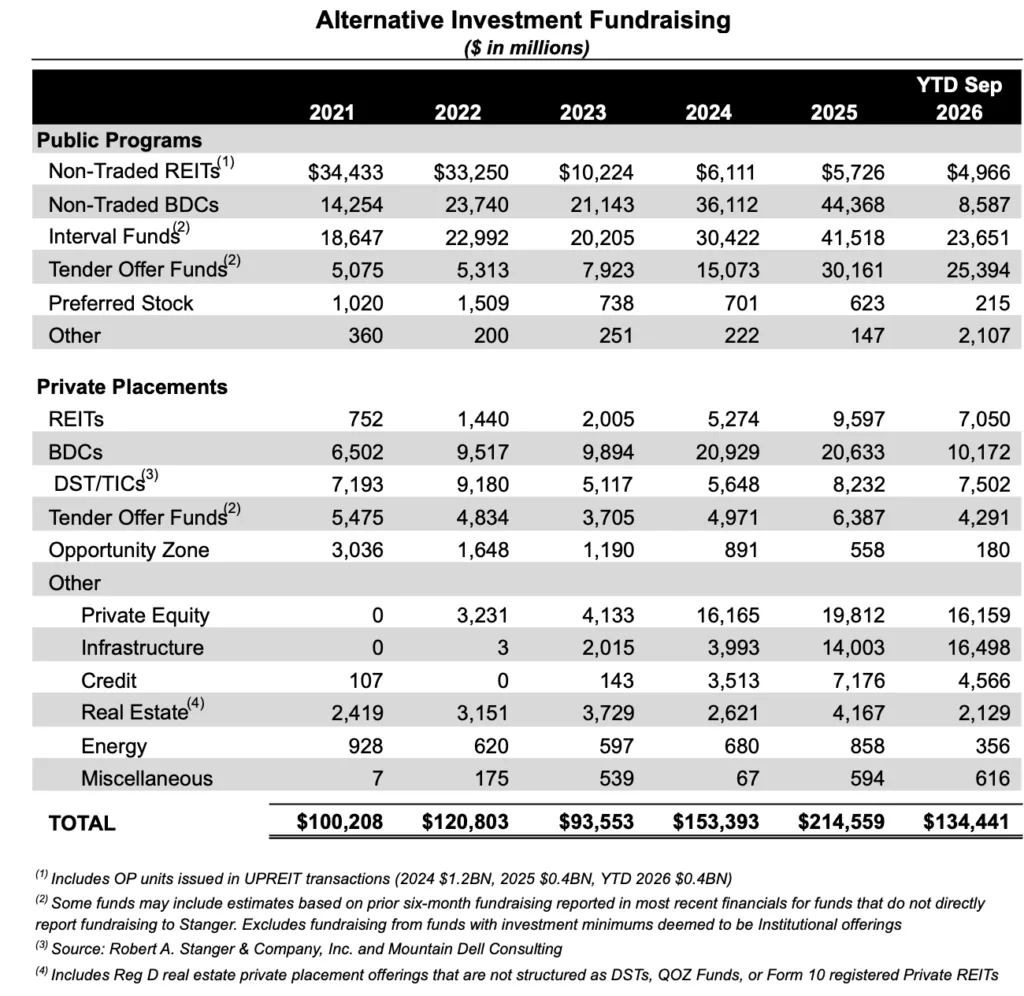
- Alternative investment fundraising totaled $134.4B through September, down 14% from a year earlier, as credit strategies fell 48% to $42.5B while non-credit fundraising rose 24% to $91.9B.
- HALO strategies, meaning real estate and infrastructure, raised $44.7B, up 39%. Infrastructure rose 67% to $22.8B and real estate 18% to $21.9B, and hard assets have led credit for six months.
- Private placements now account for 52% of fundraising versus 40% a year ago, and BDC fundraising fell 62%, which shows wealth channel dollars rotating away from credit toward hard assets.
Alternative investment fundraising totaled $134.4B through September, down 14% from $156.4B a year earlier, per Robert A. Stanger & Co. data reported by AltsWire.
Hard assets are the bright spot. They have now outraised credit for six straight months.
Get Smarter about what matters in CRE
Stay ahead of trends in commercial real estate with CRE Daily – the free newsletter delivering everything you need to start your day in just 5-minutes
Credit Drags the Total
Credit strategies raised $42.5B, down 48% year over year. Non-credit fundraising grew 24% to $91.9B.
Business development companies drove the credit slide. Combined BDC fundraising fell 62% to $18.8B from $49.1B, with nontraded public BDCs down 76% to $8.6B and private placement BDCs down 27% to $10.2B.
Hard Assets Take the Lead
HALO strategies, the hard-asset bucket of real estate and infrastructure, raised $44.7B. That is up 39% and $2.2B ahead of credit.
Infrastructure jumped 67% to $22.8B and real estate rose 18% to $21.9B.
The third quarter made the split plain. HALO raised $16.3B, up 54%, while credit fell 61% to $11.1B. In the same quarter of 2025, credit had outpaced the two hard asset categories together by about 2.7 to 1.
Private Placements Gain Ground
Private placement vehicles raised $69.5B, up 10%. Public programs raised $64.9B, down 30%.
Private placements made up 52% of fundraising, versus 40% a year earlier, and passed 55% of Q3 volume.
Who’s Raising It
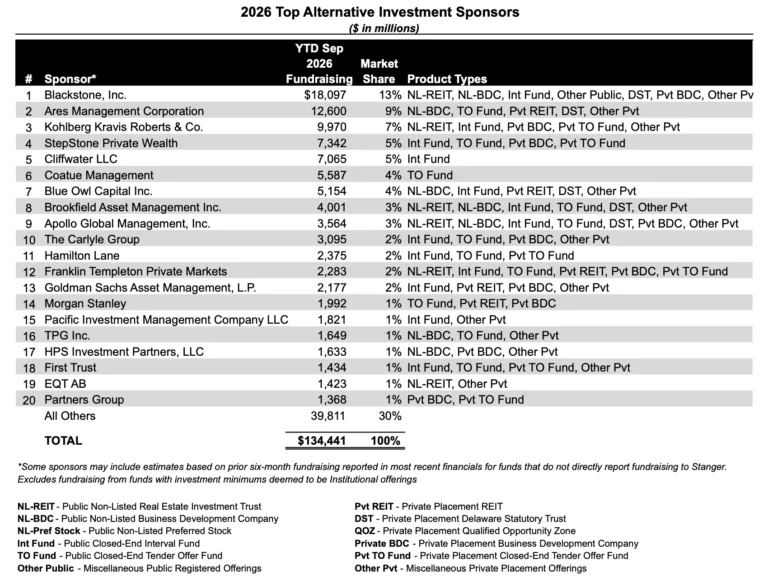
Blackstone captures 13% of sponsor fundraising. Ares takes 9%, KKR 7%, and StepStone Private Wealth and Cliffwater 5% each.
Blackstone’s own real estate results are more mixed. CRE Daily reported its opportunistic real estate funds lost 3.2% in the third quarter while core-plus funds gained 1.6%.
Cliffwater, meanwhile, is pushing into hard assets. Its new Cascade Real Assets Fund, a real estate-focused interval fund effective in August, raised $895M in its first closing in September.
Why It Matters
Stanger chairman and CEO Kevin T. Gannon said credit is skewing the totals while the rest of the market keeps expanding.
For real estate sponsors courting wealth advisors, the data shows retail capital is still flowing, just toward hard assets and away from credit.
What’s Next
Watch whether hard assets hold the lead in the fourth quarter and whether launches like Cascade pull more credit-heavy platforms into real estate interval funds.