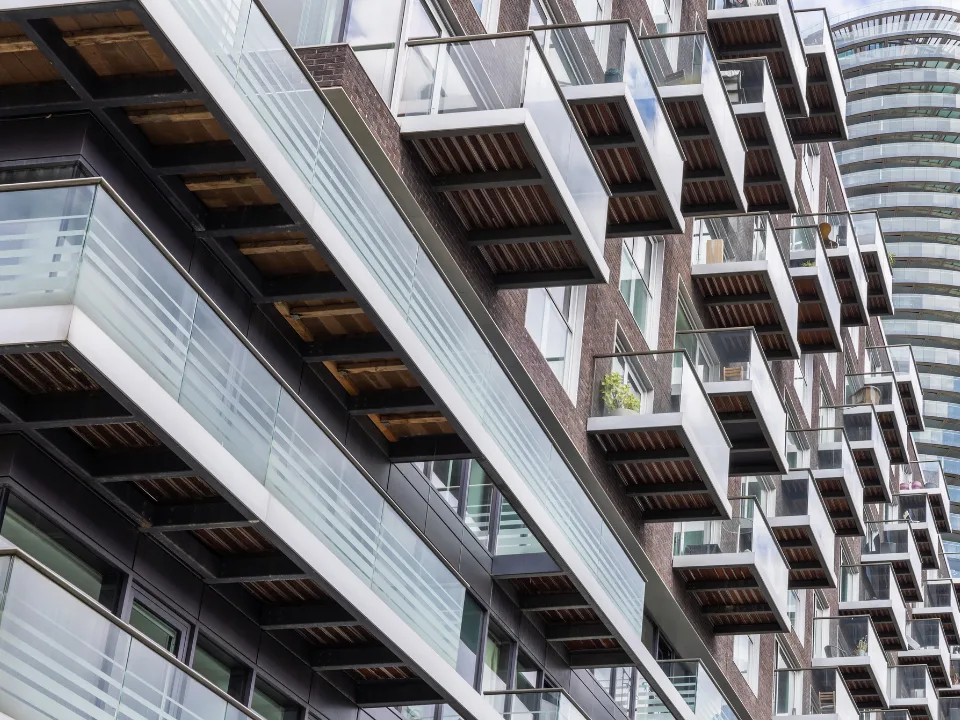



- Genesis Capital, Rithm Capital’s lending arm, closed NRMLT 2026-RTL1, a $375M securitization backed by 55 loans on apartment developments and existing properties.
- No earlier Genesis securitization has been apartment-only since Rithm acquired it in 2021, and multifamily now makes up 40% of the lender’s origination volume.
- Quarterly apartment originations at Genesis rose from $160M in early 2024 to $637M in the second quarter of 2026, a sign of strong demand for short-term multifamily credit.
Genesis Capital, the lending arm of Rithm Capital, has wrapped up a $375 million securitization backed by apartment loans, Commercial Observer reported. Rithm announced the news on Wednesday.
Every loan in the pool was originated by Genesis, which Rithm bought in 2021.
Get Smarter about what matters in CRE
Stay ahead of trends in commercial real estate with CRE Daily – the free newsletter delivering everything you need to start your day in just 5-minutes
A First for Genesis
Commercial Observer reported that Genesis had not completed an apartment-only securitization since Rithm acquired the lender in 2021. Meanwhile, Rithm said apartment lending now accounts for 40% of Genesis’ originations.
The deal, called NRMLT 2026-RTL1, includes 55 loans, according to Commercial Observer. Together, they finance both ground-up developments and operating properties.
Who Ran the Books
Performance Trust Capital Partners led the offering. Barclays, Deutsche Bank, Goldman Sachs, Nomura and Wells Fargo also served as bookrunners.
Rithm managing director Sanjeev Khanna described the deal as proof of the owner-operator model in a statement quoted by Commercial Observer. He said it connects Genesis’ lending directly to bond investors. Moreover, the structure gives Genesis flexibility to meet the varied financing needs of apartment investors.
The Origination Ramp
According to Rithm, Genesis’ quarterly apartment originations rose from $160M in early 2024 to $637M in the second quarter of 2026. Commercial Observer reported the figures. That represents roughly a fourfold increase in just over two years.
As the loan book grows, Genesis has more loans to package into securities. Each securitization also returns capital to fund another round of lending.
Rithm’s Bigger Push
Commercial Observer reported that Rithm manages $63B under CEO Michael Nierenberg. The company trades as a mortgage REIT. In September 2025, it bought Paramount Group’s office holdings for $1.7B. Those properties now operate under the name Elecor Properties.
Just days earlier, Rithm acquired Crestline, a $17B private credit manager. Together, these deals reflect Rithm’s broader effort to expand its asset base.
Why It Matters
Bond investors continue to buy apartment loan pools despite the sector’s heavy maturity pressure. As a result, short-term borrowers still have access to lenders that originate loans and package them for securitization.
Meanwhile, apartment cap rates remain close to Treasury yields. Therefore, lenders that sell loans into the bond market have a funding advantage over those that must hold loans on their balance sheets.
What’s Next
Watch for more apartment-only securitizations from Genesis. Also, look for other Rithm credit platforms to adopt a similar structure. Ultimately, borrower demand will depend on how long financing costs remain high.