
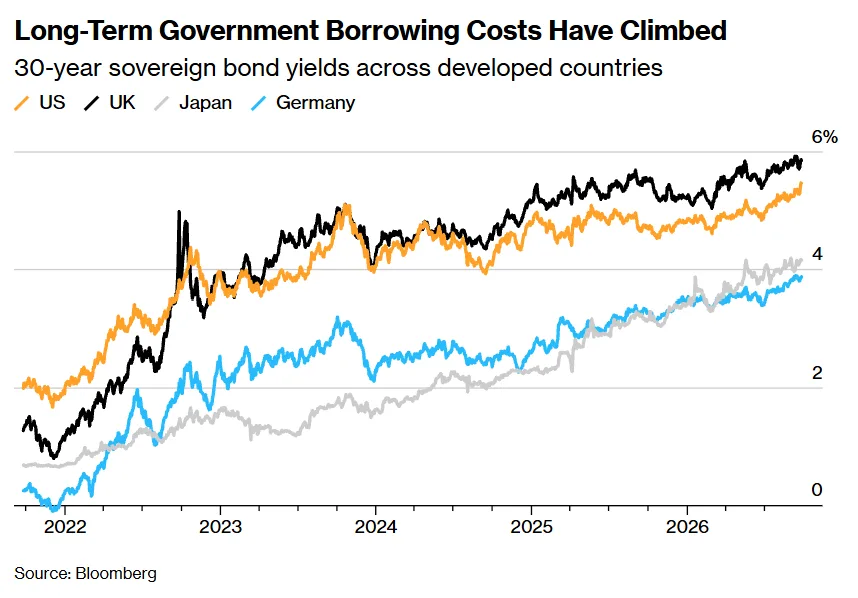
- US 10-year Treasury yields moved above 5%, while global sovereign yields averaged 4%, a level last seen in 2007.
- Investors are demanding more compensation for long-term debt as government borrowing grows and traditional buyers pull back.
- Higher long-bond yields feed into mortgages and corporate debt, keeping financing costs elevated even without another short-rate increase.
Bloomberg says long-term government borrowing costs are climbing as investors demand more compensation to hold longer-dated debt. Its analysis of the global bond selloff notes that US 10-year Treasury yields moved above 5%. That is the highest level in almost two decades. The average yield on global sovereign debt has reached 4%, matching a level last seen in 2007. The moves suggest the low-yield era may be giving way to a structurally higher baseline.
Get Smarter about what matters in CRE
Stay ahead of trends in commercial real estate with CRE Daily – the free newsletter delivering everything you need to start your day in just 5-minutes
Long Bonds Reprice Higher
The shift is most visible at the long end of the curve. In September, 30-year US Treasury yields reached their highest level since 2004. Japanese peers were near all-time highs. UK 30-year yields reached their highest level since 1998. Bloomberg says investors are weighing persistent inflation, growing fiscal deficits, and higher energy costs. Governments are also competing for capital with technology companies issuing large amounts of debt for AI infrastructure. Longer maturities are especially sensitive because inflation has more time to erode fixed payments and principal.
The Details
Bond supply and investor demand are changing at the same time. Governments are issuing more debt. Foreign appetite has weakened, and central banks have reduced holdings after years of purchases. The US national debt exceeds $40T. In August, the Congressional Budget Office estimated the annual fiscal shortfall will reach $2.1T. Private buyers are becoming more important in the market. Those investors tend to be more price-sensitive than central banks and other traditional long-term buyers. Pension and retirement-system changes have also reduced some structural demand. Bloomberg Economics estimates the term premium on 30-year Treasuries has risen by more than three percentage points from its 2020 low.
Why It Matters
Long-term Treasury yields matter well beyond government finance. They underpin borrowing costs across mortgages and corporate debt. US 30-year mortgage rates track the 10-year Treasury yield closely because many homeowners repay or refinance earlier. CRE debt also prices off the same broader rate environment. That keeps benchmark borrowing costs elevated even without another increase in short-term policy rates. The move reinforces the link between rising Treasury yields and tighter CRE debt markets. Higher yields can help savers and bond investors. They can also increase pressure on borrowers that need to refinance fixed assets at much higher coupons.
A Structural Shift in Demand
Bloomberg describes a market where the traditional convenience of Treasuries is being tested. Investors have historically accepted lower yields because US government bonds are liquid, safe, and useful as collateral. Some market participants believe rising debt and policy uncertainty have eroded part of that advantage. Others argue those concerns are overstated and Treasuries remain the world’s safest debt. The disagreement matters because even a modestly higher term premium can keep long borrowing costs elevated across the economy.
Higher Yields Cut Both Ways
The rise is not entirely negative for investors. Bondholders can earn more income than they could during the near-zero-rate period after the financial crisis. Bloomberg also notes that higher yields can reflect a global economy strong enough to absorb more expensive capital. The risk is a disorderly selloff. Sharp moves can strain governments that rely on debt markets and can transmit quickly into mortgages, corporate bonds, and other long-duration financing.
What’s Next
Governments are trying to manage the pressure without solving the underlying supply-demand imbalance. The US Treasury expanded buybacks of 10- to 30-year bonds in August. Even so, 10-year yields reached multiyear highs. Some governments are tilting issuance toward shorter maturities. That lowers current coupons but requires more frequent refinancing. Bloomberg says investors ultimately want confidence that inflation and fiscal deficits will be controlled. Wells Fargo economists described the environment as closer to ‘normal for longer’ than simply ‘higher for longer.’ If that framing holds, pre-crisis yield levels may be a more useful benchmark for CRE borrowers and lenders.