
- More than 1,000 new condo units are expected to hit the Manhattan market by year-end, a 94% jump over last year’s deliveries.
- Just 2,800 new development units remained in Manhattan at the end of August, and more than 60% sit in the Financial District and Midtown.
- Long-term supply stays tight, with deliveries through 2029 projected to run 16% below pre-2021 levels and skew heavily toward ultra-luxury product.
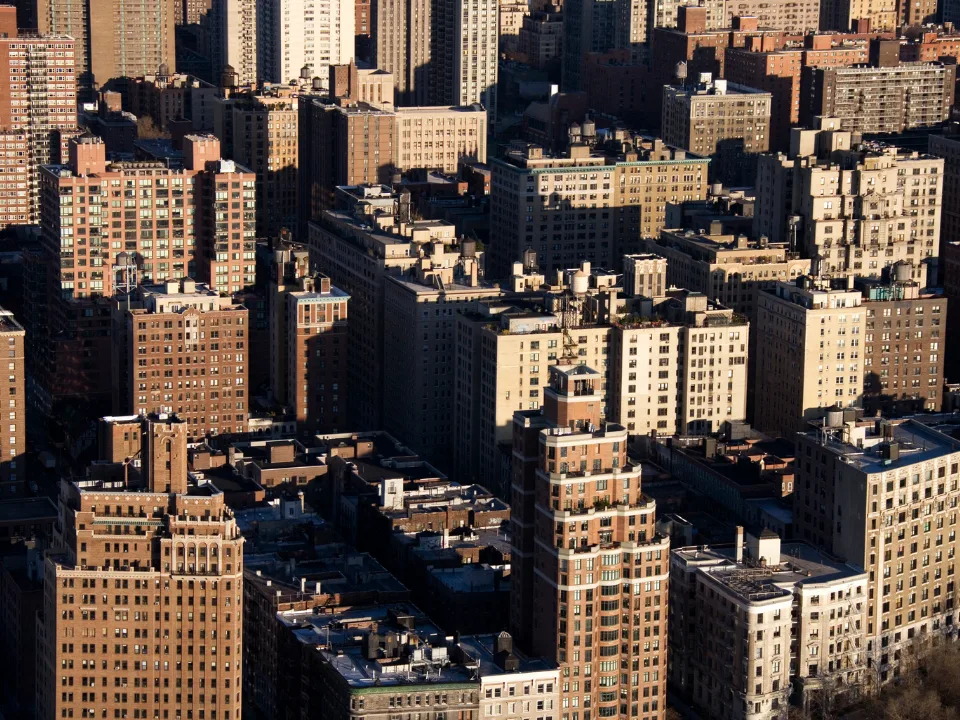
Manhattan condo buyers have been starved for options, with new development inventory dropping to its lowest point in more than a decade, according to The Real Deal. That drought may be easing: developers plan to bring more than 1,000 new units to market between now and the end of 2026.
Get Smarter About What Matters in New York
Subscribe to our free newsletter covering the biggest commercial real estate stories across the five boroughs — delivered in just 5 minutes.
Demand Without Supply
Marketproof data shows that new development contracts fell 26% from April through September compared with the same period last year. Meanwhile, resale condo contracts rose 12%. The figures suggest that buyers remain active but have fewer new options.
Over the past year, sponsor sales have outpaced new unit introductions by roughly 2-to-1. By the end of August, Manhattan had only 2,800 new development units available. That marked the lowest total since 2014.
The Details
Much of the remaining inventory consists of slow-moving stock. More than 60% of Manhattan’s condo inventory sits in the Financial District and Midtown.
The inventory includes long-marketed buildings such as One Wall Street, 125 Greenwich, the Waldorf-Astoria conversion, and Malabar Residences on 57th Street. Dan Parker of Compass Development Marketing described much of this stock as stubborn inventory.
By contrast, projects in prime locations have sold almost as quickly as they launched. Legion Investment Group and Nahla Capital’s 1122 Madison is nearly sold out in under a year. The project recently included a penthouse deal with an $89 million asking price.
The Village West at 525 Sixth Avenue has sold all 68 units. Meanwhile, 220 East Ninth Street sold out without ever opening a sales gallery.
The fall lineup targets similar neighborhoods. Corcoran Sunshine is marketing the 72-unit 101 Franklin. According to Marketproof, it is Tribeca’s largest project in a decade.
Legion also plans an 83-unit building at 550 West 21st Street. Pricing will start at $2.5 million. The firm is also developing the 34-unit Greenwich Spire at 11 West 13th Street with EJS Group.
Uptown, Nortco’s 37-unit 200 West 88th Street will start at $5 million.
A Pipeline Tilted Toward the Top
Corcoran Sunshine’s Kelly Mack said the fall wave represents a 94% increase over last year. It also runs 10% above the 10-year average.
However, the longer-term outlook is less positive. The trend echoes earlier forecasts that the condo pipeline shrinks through the end of the decade.
Corcoran Sunshine projects roughly 1,500 units per year from 2026 through 2029. That figure sits about 16% below pre-2021 levels.
The Upper East Side should add 182 units annually. That represents a 54% increase over its previous 10-year average. Meanwhile, the Financial District will receive no new major condo buildings.
Midtown deliveries are expected to rise 46%. Downtown deliveries should fall 10%, while Brooklyn could see nearly 30% fewer units than its previous decade.
Why It Matters
The development mix is shifting sharply toward the luxury market. Corcoran Sunshine forecasts only 43 units per year priced at a blended $1,800 per square foot or less.
That figure represents a 74% drop from the previous decade. By comparison, developers expect to deliver 123 units per year priced above $5,000 per square foot. That is nearly three times the historical average.
Large projects are also becoming less common. Manhattan buildings with more than 150 homes could see unit deliveries fall almost 40% over the next three years.
Mack pointed to elevated development costs and the difficulty of assembling large sites. As a result, only top-of-market projects may remain financially viable.
What’s Next
Brown Harris Stevens Development Marketing’s Robin Schneiderman called this fall’s launches a litmus test for the market. The projects will bring new supply to several prime locations.
The lineup includes the long-awaited relaunch of 262 Fifth Avenue with a new Sotheby’s International Realty team. Strong absorption in Tribeca, Chelsea, and the Upper West Side would indicate that supply constraints, rather than weak demand, have driven the slowdown.
On the Upper West Side, Extell’s 430-unit project on the former Disney campus will account for most of the neighborhood’s projected 8% annual increase in new condos over the next three years.