- Real estate secondaries reached a record $20.3B in 2025, according to Ares, as sponsors increasingly looked beyond traditional property sales for liquidity.
- GP-led transactions accounted for $14.5B, or 72%, of 2025 volume as continuation vehicles, recapitalizations, and other structures let sponsors retain assets while returning capital to investors.
- Panelists at the 2026 Real Estate GP/LP Summit argued that secondaries and GP stakes are evolving from niche transactions into permanent tools for financing assets and operating platforms.
Real estate secondaries are having their institutional moment.
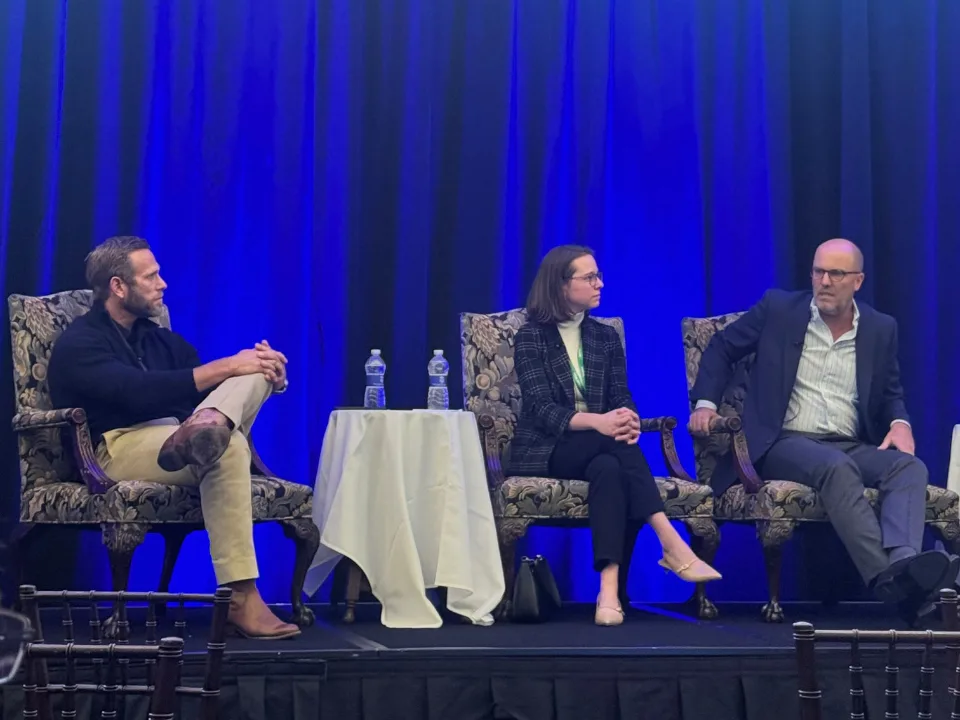
At the Real Estate GP/LP Summit in New York on Sept. 23, executives from Ares Management, Goldman Sachs, StepStone Group, GCM Grosvenor, Madison International Realty, and Gibson Dunn laid out how secondary transactions and GP stakes are reshaping the relationship between real estate managers and their investors. The underlying theme: Selling the building is no longer the only way to generate liquidity.
The inaugural summit, produced by IMN in partnership with GP-LP Match, brought together more than 150 LPs and 150 GPs. Sherida Sessa, SVP of Real Estate at IMN, said the event was designed to create “meaningful investment and capital raising opportunities in real estate.”
Get Smarter about what matters in CRE
Stay ahead of trends in commercial real estate with CRE Daily – the free newsletter delivering everything you need to start your day in just 5-minutes
From niche solution to $20B market
The shift comes after several years in which higher interest rates, slower transaction activity, and weak distributions disrupted the traditional private real estate fund cycle.
Ares Secondaries Group tracked $20.3B of real estate secondary transactions that closed or went under contract in 2025, up 39% from $14.6B in 2024. GP-led transactions jumped 60% to $14.5B and represented 72% of the market, according to Ares’ 2026 market report.
That growth is giving sponsors another option when a fund reaches the end of its planned hold period but the underlying real estate still has room to run.
The details
The basic problem is increasingly familiar to private real estate managers. An LP may want its money back, while the GP believes selling the property today would leave future value on the table.
A secondary transaction can help bridge that divide. Existing investors may cash out or, depending on the structure, roll some or all of their interest into a new vehicle. The sponsor can retain control of the real estate, while new capital effectively resets the ownership structure and potentially funds the next phase of the business plan.
Panelists emphasized that these deals can look a lot like the recapitalizations CRE owners have used for decades. What’s changing is the size, institutional participation, and range of structures available.
The market now encompasses everything from fund and portfolio recapitalizations to minority interests in individual assets, continuation vehicles, and capital invested directly into real estate operating companies.
Real estate liquidity gets another lane
That flexibility matters because the traditional closed-end fund model was built around a relatively predictable sequence: acquire assets, execute the business plan, sell, distribute proceeds, and raise another fund.
The last several years have scrambled that timeline.
Panelists argued that the real estate cycle and capital markets cycle have become increasingly disconnected. An asset may still have attractive operating fundamentals even when financing conditions or LP liquidity requirements make the original ownership structure difficult to maintain.
Senior housing offers one example. Assets acquired before COVID may have underperformed original expectations after the pandemic disrupted operations, but today’s demographic and operating outlook can make the same properties attractive at a reset basis. Instead of forcing a sale and potentially disrupting an operating-intensive asset, a secondary investor can provide liquidity while keeping the property and operator together.
The same principle applies beyond any one property type. Panelists said these investments tend to be situational rather than based on filling predetermined sector allocations.
Why it matters
Secondaries effectively add another exit — or non-exit — option to the CRE capital stack.
Ares estimates more than $2T of NAV remains in closed-end private real estate funds and non-fund vehicles including joint ventures and co-investment structures. Meanwhile, global direct real estate transaction volume remained 34% below its 2021 level as of year-end 2025, according to CBRE data cited by Ares.
That gap helps explain why secondary investors are finding more opportunities. A sponsor that previously faced a binary decision between selling an asset or asking existing investors for more time can increasingly bring in a new capital partner instead.
But giving GPs more flexibility can also create new questions around alignment.
“During distress the alignment of interests between a GP and an LP tends to diverge and needs careful attention,” Aleksey Chernobelskiy, CEO and co-founder of GP-LP Match, told CRE Daily.
A GP, for example, may have reputational or fundraising reasons to avoid a sale or foreclosure even when an LP’s priority is maximizing the likelihood of getting its capital back, Chernobelskiy said. Similar conflicts can emerge during recapitalizations, making it important for LPs to understand their options and advocate for their own interests.
The implications extend beyond individual properties. GP stakes and platform-level investments can also give growing operators capital to hire teams, expand vertically, enter new markets, or fund GP commitments without surrendering control of the company.
For emerging and middle-market managers, that creates another potential bridge to institutional scale. But it also raises the bar on reporting, valuation, governance, and track record — areas panelists said secondary and platform investors scrutinize closely.
What’s next
The market still has plenty of runway. Ares expects real estate secondary volume could double over the next several years as investors look for liquidity across the more than $2T of NAV sitting in private real estate vehicles.
The bigger shift may be behavioral. What started as an alternative when conventional exits were difficult is becoming a permanent part of how sponsors manage capital.
For GPs, that means the end of a fund’s hold period doesn’t necessarily have to mean the end of ownership. For LPs, it creates more ways to choose between liquidity and continued exposure. And for secondary investors, the prolonged mismatch between property-level business plans and fund-level timelines is creating an increasingly deep pipeline of deals.