

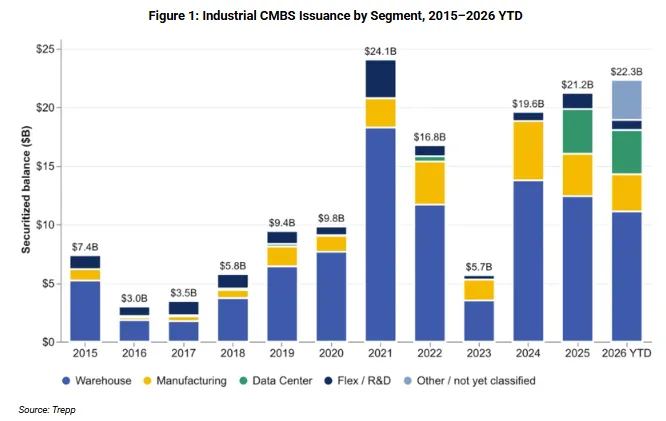
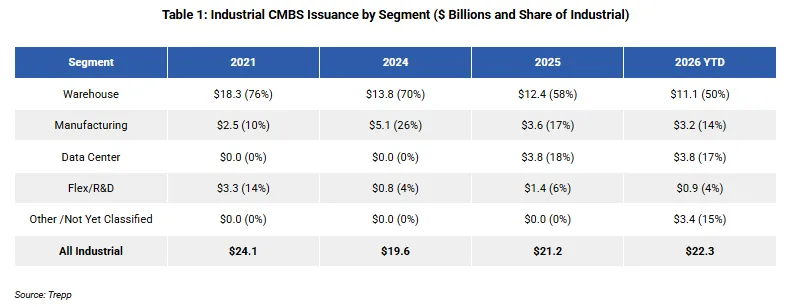
- Industrial CMBS issuance hit $22.3 billion through Oct. 29, or 20% of private-label CMBS, leaving only $1.7 billion to beat the 2021 record of $24.1 billion.
- Warehouses fell to 50% of issuance from 76% in 2021 as refinancings (91% of this year’s warehouse loans with a stated purpose) replaced acquisition financing.
- Data centers added $3.8 billion this year, nearly all from four Blackstone loans, so the segment’s performance rests on a handful of loans and one sponsor.
Industrial CMBS issuance totals $22.3 billion as of Oct. 29, Trepp research shows, a fifth of private-label CMBS this year.
Only 2021, at $24.1 billion, topped it since 2015. The record is $1.7 billion away with two months left.
Get Smarter about what matters in CRE
Stay ahead of trends in commercial real estate with CRE Daily – the free newsletter delivering everything you need to start your day in just 5-minutes
Warehouses Lose Share
Warehouses still lead with $11.1 billion, but that is only half of industrial issuance. In 2021 warehouses held 76%, and in 2024 they held 70%. Manufacturing contributes $3.2 billion, and flex/R&D just under $1 billion.
Another $3.4 billion is large portfolio deals that haven’t been assigned a property subtype yet, so shares will shift. Warehouses back $43.8 billion, or 59%, of the $74.5 billion industrial CMBS balance.
Refinancing Replaces Buying
Among 2021 warehouse loans that disclosed a purpose, 54% financed acquisitions. This year acquisitions are 8% and refinancings 91%, though purpose is blank for 26% of this year’s warehouse balance, Trepp notes.
Single-borrower warehouse volume slid from $16.5 billion to $9.6 billion. Jumbo warehouse loans of $500M-plus dropped from 11 worth $10.3 billion to eight worth $6.1 billion, and deed transfers of industrial properties fell 32% between 2021 and 2025.
Data Centers Arrive
No year before 2025 saw more than $0.5 billion of data center CMBS. Issuance reached about $3.8 billion in 2025 and has matched that pace year to date.
Outstanding data center CMBS rose from $4.5 billion to $8.2 billion in twelve months. Four Blackstone single-borrower deals make up $6.9 billion, roughly 90% of what has been securitized since 2025, and much data center financing happens in private credit instead.
Why It Matters
A segment that depends on one sponsor is fragile. That lines up with the investor pushback on data center debt we covered in October, when a Bloomberg exclusive found at least 18 high-yield and leveraged loan deals carrying double-digit yields.
Single-borrower deals also carry 89% of industrial CMBS volume this year, versus 74% for other property types, so a few big portfolios swing the totals.
What to Watch
Trepp is watching whether data center issuance broadens beyond one sponsor and whether warehouse issuance keeps tilting toward refinancings.
It also flags Amazon’s 2027 and 2028 lease expirations, since renewals will influence how warehouse loans perform.