


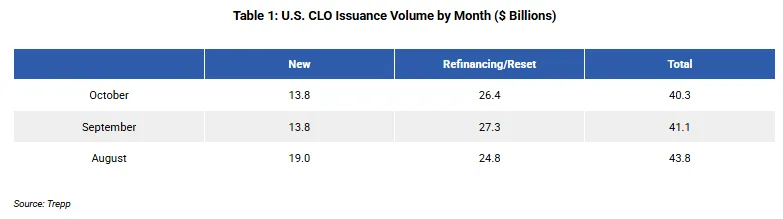
- U.S. CLO issuance fell to $40.3B across 92 deals in October from $41.1B in September, while Europe rose to €15.7B across 34 deals, its biggest month since February.
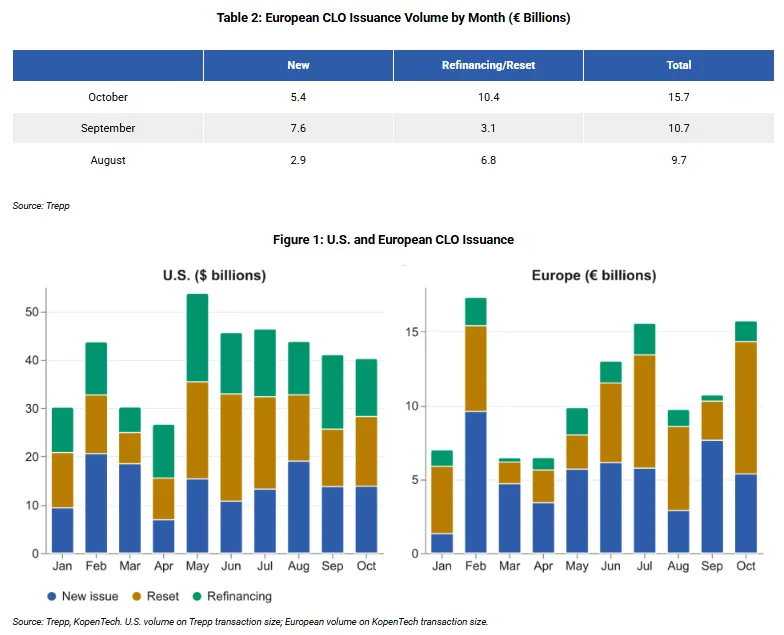
- Refinancings and resets made up about 66% of volume in both markets, and new-issue AAA spreads tightened to 121 basis points in the U.S. and 122 in Europe.
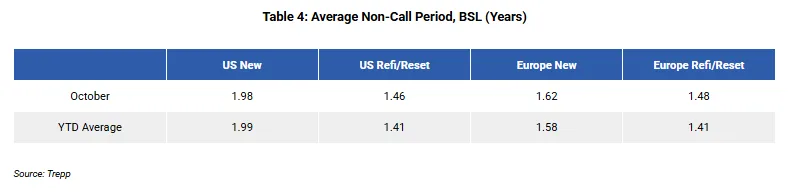
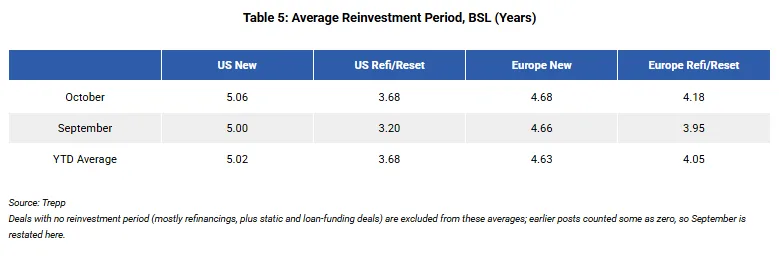
- The return of resets lengthened non-call and reinvestment periods, giving managers more time but showing activity still leans on existing deals rather than new ones.
U.S. CLO issuance eased to $40.3B in October, spread over 92 deals and the lowest monthly total since April, according to Trepp.
Europe went the other way, rising to €15.7B across 34 deals, the most since February.
Get Smarter about what matters in CRE
Stay ahead of trends in commercial real estate with CRE Daily – the free newsletter delivering everything you need to start your day in just 5-minutes
Resets Take the Lead
A refinancing lowers what a deal pays on its notes. A reset swaps out every note and lengthens the vehicle’s life.
In the U.S., refinancings and resets totaled $26.4B, about 66% of volume, with resets at $14.4B across 30 deals. European resets hit €9.0B, Europe’s highest monthly reset total this year, per Trepp and KopenTech data.
New-Issue Pricing
New-issue AAA spreads on broadly syndicated loan deals tightened again, with U.S. deals averaging 121 basis points and European deals 122. Trepp notes that eight deals priced under 100 basis points, which pulled the averages down.
Without those, U.S. deals averaged 122. Cheaper senior funding gives managers a reason to redo older deals.
Longer Terms
U.S. refinancings and resets averaged a 1.46-year non-call period, up from 1.28 years in September. Their reinvestment periods stretched to 3.68 years from 3.20.
Year to date, U.S. volume totals $401.4B across 914 deals, and Europe stands at €110.6B across 263.
Zoom Out
This is the corporate loan market, not commercial real estate. We covered the separate CRE CLO issuance story on Nov. 13, where apartment bridge loans pushed volume to $40.2B through October, up 66% from last year.
Why It Matters
CLO pricing is a read on how cheaply managers can fund loan portfolios. Cheaper funding keeps refinancing activity alive even when new deals slow.
Trepp says most of October’s activity came from existing deals, not new ones.
What’s Next
Watch whether AAA spreads keep tightening and whether resets stay ahead of refinancings in November. Trepp’s data also shows U.S. middle-market issuance at its lowest monthly total this year, at $2.5B.