
- Bank of America took 16,000 square feet at 19 Union Square West and Citibank took 14,000 square feet at 170 West 72nd Street, two of Manhattan’s largest third-quarter retail leases.
- Most bank activity is renewals and strategic relocations by existing tenants, and banks are returning to corner locations in a market where space is hard to replace.
- Prime corridor availability fell to a record-low 157 spaces, and one JLL broker has five or six more bank deals in progress, a sign of broader retail strength.
Banks are fighting for Manhattan storefronts while branches close elsewhere, with bank branch leases among the biggest retail deals of the third quarter, Bisnow reported.
Back in mid-October, JLL’s Matt Ogle told Bisnow his team was working on five or six more bank deals, a pace he called “abnormally high.”
Get Smarter About What Matters in New York
Subscribe to our free newsletter covering the biggest commercial real estate stories across the five boroughs — delivered in just 5 minutes.
Not the Branch Era Anyone Predicted
Ogle told that three years ago, many people questioned whether branches had a future in New York at all. Now, he said, the turnaround is “very encouraging.”
The shift runs against the national picture. As many as 6,000 branches closed across the US from 2019 through 2025, with about 1,354 of those in 2024, according to The Wall Street Journal.
The Deals
Bank of America took 16,000 SF at 19 Union Square West and Citibank took 14,000 SF at 170 West 72nd Street. OceanFirst Bank’s 4,000 SF at 36 Union Square East ranked among the largest in Union Square-Flatiron.
Wells Fargo’s new Upper West Side branch sits at 109th and Broadway, at the residential northern end of the neighborhood. It includes an expanded consultation space, per the bank’s own social media post.
Ethan Wingfield, who oversees Wells Fargo’s branch channel, told Bisnow customers still visit branches for advice even as mobile use grows.
Renewals Over Expansion
Most of the activity is renewals and relocations by banks already in Manhattan. Banks with leases coming up are renewing early because availability is so thin.
That tracks with JLL’s data. Our earlier look at the report found record-low availability of 11.4% in prime corridors, the lowest since 2017, with asking rents up 5.7% to $605 per square foot.
Bisnow put the count at 157 available spaces across the nine prime corridors JLL tracks.
Back to the Corner
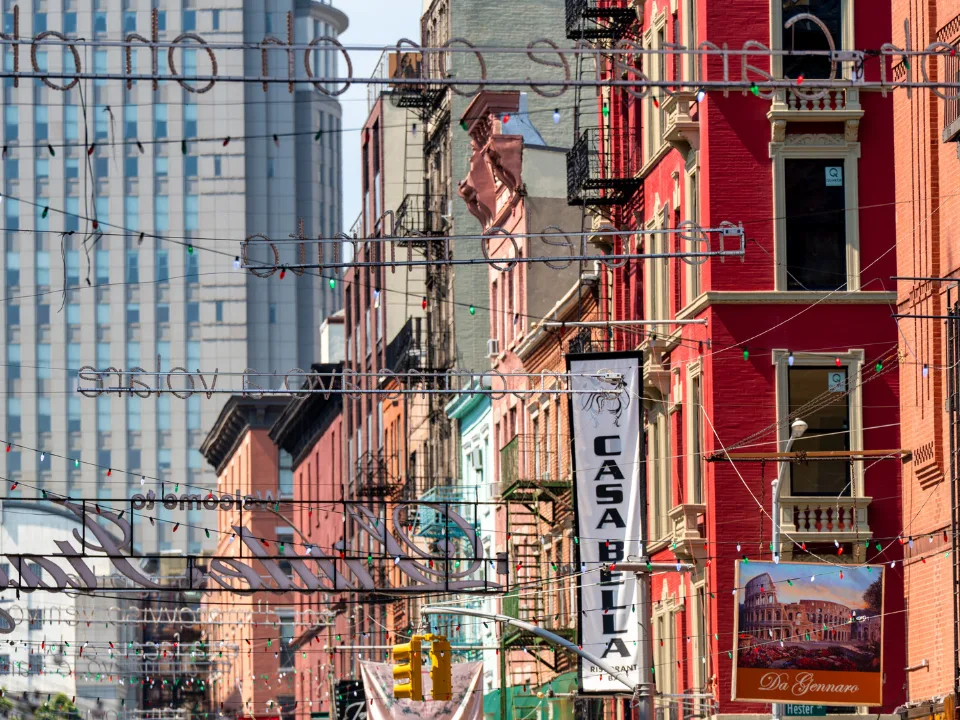
Brokers told that banks are moving back to corner locations after a couple of years of trying other spots. Ogle said some of his clients regretted leaving corners.
Location also signals the target customer. Banks chasing wealthier clients look to Midtown for office workers, while others pick residential blocks or sites beside grocery stores.
Why It Matters
Capricorn Retail Advisors’ Jason Richter said a branch doubles as marketing, especially for a business that asks people to hand over their money.
Ogle sees bank demand as a read on the whole retail sector. Shoppers returned to stores after the pandemic, and he argues people still want a human touch for financial services.
What’s Next
With bank deals still in the pipeline, JLL’s fourth-quarter numbers should show whether banks keep taking a meaningful share of prime Manhattan leasing.