




- Houston office vacancy held at 25.6% in Q3 2026, up 30 basis points from a year earlier, as the market recorded 31,374 SF of negative absorption for the quarter.
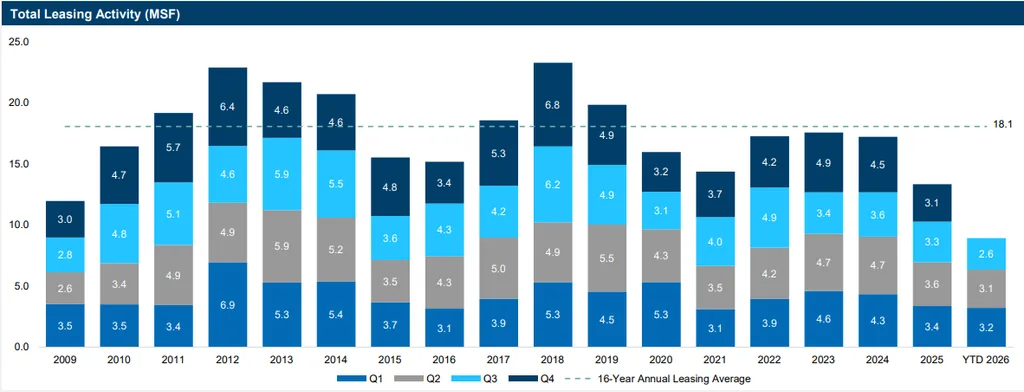
- Leasing totaled 2.6 million SF, down 17.9% from Q2 and 22.4% from a year earlier, and the 8.9 million SF year-to-date total is the lowest nine-month figure since 2009.
- Tenants are consolidating into Class A space, which took 65.5% of leasing, and the construction pipeline sits at a record low, which should keep vacancy elevated but stable.
Houston’s office market closed Q3 2026 with vacancy at 25.6%, flat from Q2 and 30 basis points higher than a year earlier, according to Newmark’s 3Q26 Houston office report.
Leasing slowed to 2.6 million SF, but the tenants that did sign leaned toward Class A buildings, Newmark found.
Get Smarter About What Matters in Texas
Subscribe to our free newsletter covering the biggest commercial real estate stories across Texas — delivered in just 5 minutes.
Leasing Falls to a Multiyear Low
Q3 leasing dropped 17.9% from Q2 and 22.4% from a year earlier. That marks a second straight quarterly and annual decline, and volume sits 42.4% under the 16-year Q3 average.
Through September, leasing reached 8.9 million SF, the weakest nine-month total since 2009, per Newmark.
Net absorption was negative 31,374 SF in the quarter, though the year so far is still ahead by 55,335 SF. Newmark said that extends a positive 2025 that followed a 2024 in which tenants shrank their footprints on balance.
Class A Pulls Ahead
Class A deals totaled 1.7 million SF, or 65.5% of leasing activity, which read the split as occupiers choosing or keeping space in high-quality assets.
The Class A inventory stands at 129.8 million SF after adding 652,044 SF in the past year. Class A vacancy rose 10 basis points from Q2 to 27.0% and is flat year over year, having moved only between 26.9% and 28.0% since early 2024.
Rents Plateau Near a Record
Average full-service asking rent reached $31.02 per SF, a 2.3% annual gain that sits about 0.2% under Q2’s record of $31.08. Yearly growth cooled from 6.4% in Q1 and 8.3% in Q2.
Newmark said the pattern implies owners are keeping headline rates level while offering more concessions. Sublease rents climbed 7.7% from a year earlier to a record $26.54, narrowing the gap with direct rents to $4.60 per SF from $4.78.
By class, Class A asking rents slipped 0.5% from Q2 to $36.52 per SF while Class B gained 1.0% to hit a record $23.71, trimming the gap between them to $12.81.
The West and North Lead
Rent growth is uneven. Over five years through Q3 2026, FM 1960/249 posted the strongest increase at 22.0%, followed by The Woodlands at 20.8%, while Greenway Plaza and Westchase fell 2.0% and 5.9%.
The biggest Q3 deals mostly landed away from downtown, while large tenants keep shifting west. The pattern echoes the uneven picture elsewhere in Texas, where CRE Daily reported DFW office vacancy dropping to 24.6% with no new deliveries.
Marquee Deals and a Thin Pipeline
The Harris County Flood Control District landed the biggest lease, 86,743 SF at 4425 Westway Park Blvd., with move-in expected in H1 2027, which represented the tenant. Marathon Petroleum renewed at 500 Dallas St. and expanded to more than twice its prior footprint, now on floors 29 and 30.
Target Hospitality moved its headquarters to 1790 Hughes Landing Blvd. from 9320 Lakeside Blvd. and expanded. Michels sublet floors two and three at 12140 Wickchester Lane, space previously leased to Rimkus.
New supply is limited. Completions total 731,036 SF this year, mostly spoken for before opening, while the pipeline shrank to a record-low 492,662 SF, only 0.2% of inventory and the thinnest share since 2009, per Newmark. Autry Park and 2811 Kirby are the main non-medical projects underway.
Why It Matters
Newmark said vacancy will stay elevated until obsolete buildings are renovated or removed. Direct availability has eased to 24.8%, 180 basis points below its Q3 2023 peak of 26.6%, and sublease availability is a steady 2.0%.
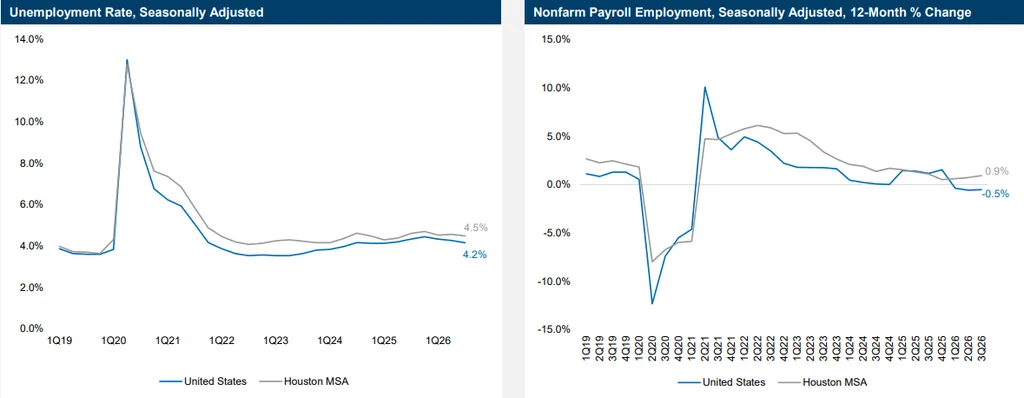
The labor backdrop is supportive. Office-using employment hit a record 786,590 jobs, up 1.3% year over year and 9.4% above pre-pandemic levels, per Newmark’s analysis of Oxford Economics data.
Debt exposure looks manageable. Office loans are just 12.1% of the $49.8B coming due between 2026 and 2030, versus 60.2% for multifamily, Newmark reported. Government-agency and CMBS debt makes up $33.6 billion of that five-year total, and the maturity wall nationally is shrinking even as higher rates raise the stakes, CRE Daily reported.
What’s Next
Newmark expects vacancy to plateau close to today’s elevated level, rent growth to moderate as landlords lean on concessions, and both the quality shift and the westward drift to continue.
Investment should stay measured because of high vacancy, higher borrowing costs and a thin development pipeline. It flagged hybrid work, energy-market swings, and higher insurance and climate costs as risks.