




- A $1.3 billion CMBS loan on a Blackstone apartment portfolio was flagged for special servicing after it matured in October, with $517.7 million of the balance still outstanding.
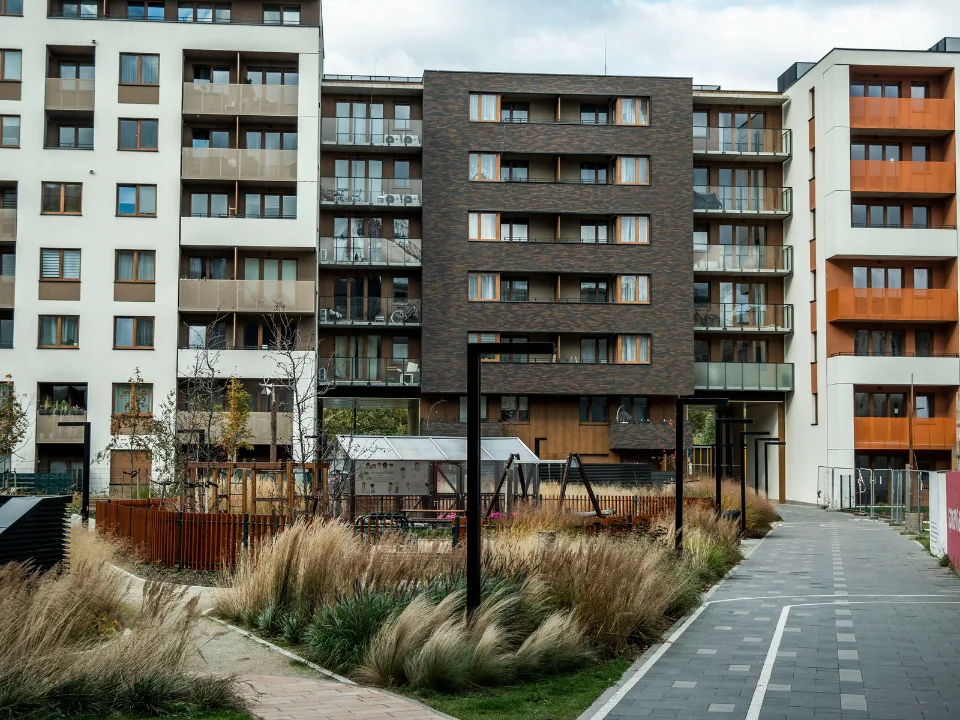
- Blackstone has sold down the 21-asset, 6,671-unit portfolio since at least 2023 and has six properties with 1,842 units left, backed by a three-month forbearance to sell them.
- The loan adds to Sun Belt apartment distress, as Texas loans flagged for foreclosure topped $1 billion for the fourth time this year in October.
A $1.3 billion CMBS loan backed by a Blackstone apartment portfolio has moved to special servicing after hitting its maturity date earlier in October, according to Morningstar Credit, as cited by The Real Deal.
Blackstone took out the loan in 2021 and has been selling off the portfolio, which now has about $517.7 million of debt left, The Real Deal reported.
Get Smarter about what matters in CRE
Stay ahead of trends in commercial real estate with CRE Daily – the free newsletter delivering everything you need to start your day in just 5-minutes
How the Loan Got Here
Inspections uncovered deferred maintenance, prompting lenders to place the loan on a watchlist that December. According to The Real Deal, it remained there as maturity approached.
The collateral originally covered 21 properties with 6,671 units. However, Blackstone has been selling assets since at least 2023. As a result, only six properties with 1,842 units remain, per The Real Deal.
A Three-Month Window
Blackstone negotiated a three-month forbearance to complete the sales, The Real Deal reported. The remaining assets include two properties in Seattle and one in San Antonio. They also include a complex in Jonesboro, Georgia, and a property in Bradenton, Florida.
A Mixed Summer for Blackstone
Blackstone’s multifamily results were mixed this summer, The Real Deal reported. For example, the firm gave up 75 West Apartments, a 490-unit Dallas community. This followed a default on a $90 million Ares Management loan from 2022, equal to roughly $184,000 per unit.
However, Blackstone also secured a $1 billion CMBS refinancing. The deal covers a 6,041-unit portfolio concentrated in Florida, Texas and Georgia. An August KBRA report cited by The Real Deal detailed the transaction.
Distress Beyond Syndicators
In Texas, loans flagged for foreclosure topped $1 billion in October. According to The Real Deal, this marks the fourth time that threshold has been crossed this year.
The largest new apartment loan on the list backs Olive Tree Holdings’ Meyerland on Braeswood, per Roddy’s Foreclosure Listing Service.
FS Credit originated the $93.9 million loan in 2025. The debt is backed by a 1,326-unit complex on Braeswood Boulevard. That equals about $70,814 in debt per unit, according to The Real Deal.
Why It Matters
The Real Deal presented the loan as evidence that Sun Belt apartment distress extends beyond small syndicators. The pressure follows rate hikes that ended the buying frenzy of the early 2020s.
Meanwhile, CRE Daily has tracked similar signs of strain. These include a CMBS special servicing rate at its highest level since 2013. Rising multifamily delinquency in private-label CMBS adds to the concern.
What’s Next
The forbearance gives Blackstone three months to act. Watch for sales of the six remaining properties. Also, track how much of the $517.7 million outstanding balance those transactions repay.