
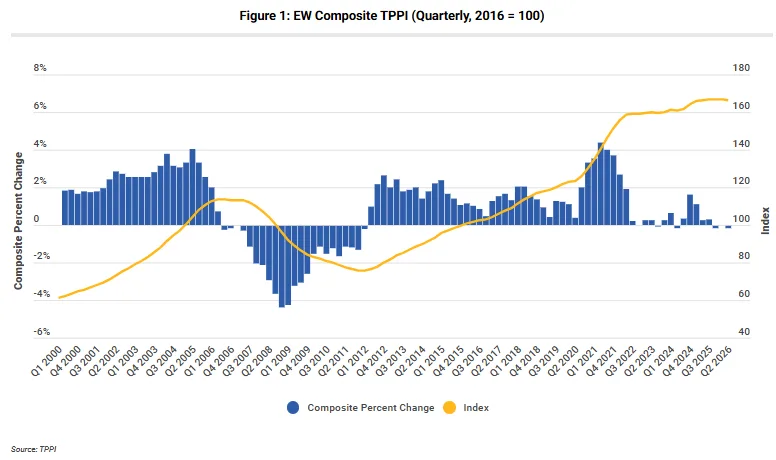
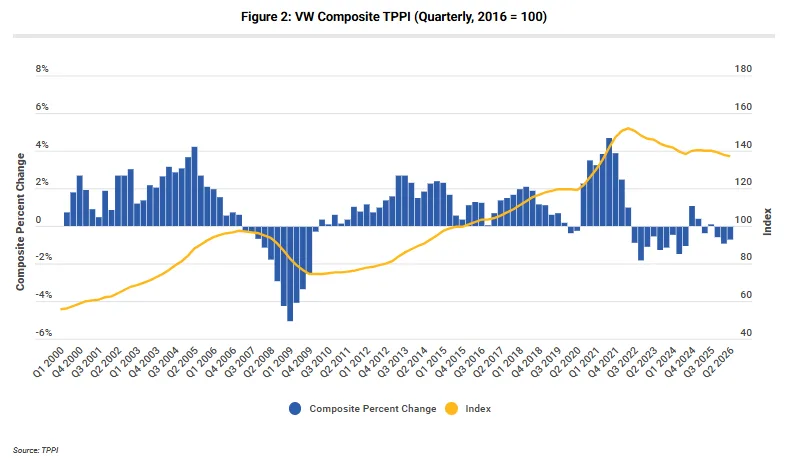
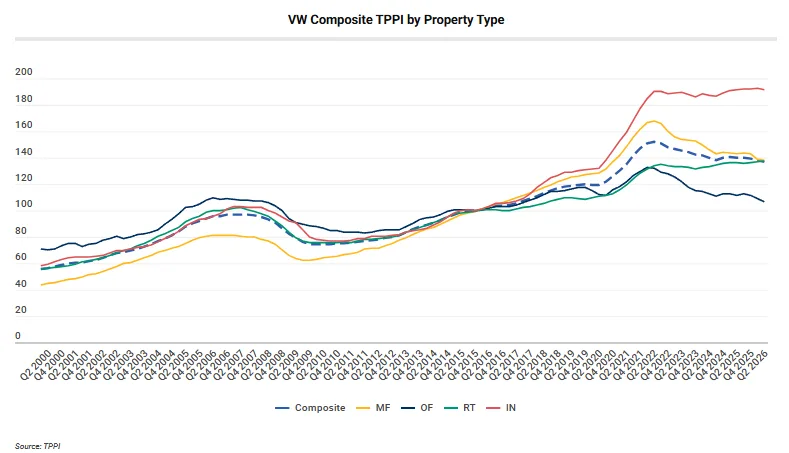
- Trepp’s equal-weighted composite slipped 0.12% in Q2 2026 and stays 4.96% above June 2022, while the value-weighted composite fell 0.70% and remains 9.89% below that mark.
- Office fell on both indices, with the value-weighted index down 2.41% on the quarter and 19.53% since June 2022, while retail alone gained on both.
- Trepp says rate increases since June add to the pressure on prices and volume, so Q2’s stabilization faces a test.
Commercial real estate prices were nearly flat in Q2 2026, according to Trepp’s Property Price Index, but the gap between large and small assets persists.
Trepp’s equal-weighted composite slipped 0.12% in the quarter and remains 4.96% higher than in June 2022. Its value-weighted composite fell 0.70% and sits 9.89% below that level.
Get Smarter about what matters in CRE
Stay ahead of trends in commercial real estate with CRE Daily – the free newsletter delivering everything you need to start your day in just 5-minutes
Small Deals Hold, Large Deals Slip
The index uses repeat sales of the same properties, and Trepp added 9,508 new sale pairs in the quarter. The equal-weighted version treats every property type and price tier alike, while the value-weighted version leans toward large transactions.
Over the past year, the equal-weighted composite is up 0.06% and the value-weighted one is down 2.03%. Trepp reads the split as evidence that bigger, institutional-quality properties are likelier to lose value, while smaller and mid-sized properties have found firmer footing.
Retail and Industrial Hold Up
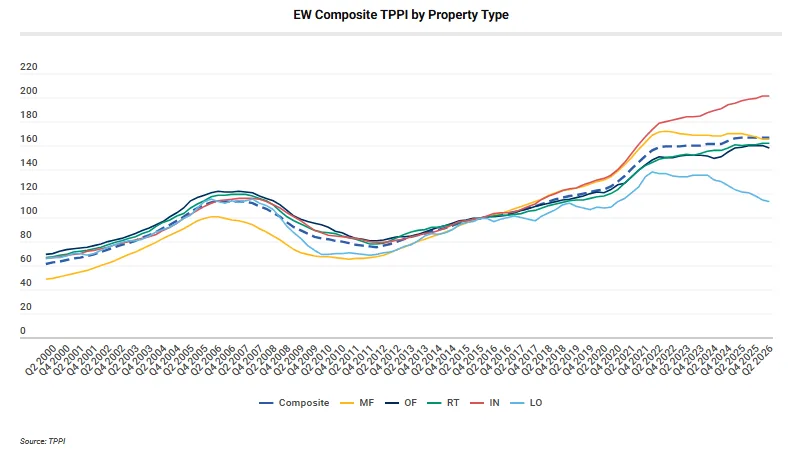
Retail alone gained on both indices. Equal-weighted prices rose 0.31% on the quarter and 1.34% on the year and sit 8.98% above June 2022. The value-weighted index gained 0.57%, is up 1.29% year over year and is 2.84% above June 2022.
Trepp points to limited new supply and steady demand for everyday-needs and service-focused space, though consumer spending and tenant performance are getting more uneven.
Industrial rose 0.15% equal-weighted, gained 2.07% over twelve months and sits 12.55% above June 2022. Value-weighted industrial slid 0.47% and is flat on the year, so bigger deals have stalled. Trepp says trade policy, oil prices and geopolitics will shape demand next.
Office, Multifamily and Lodging Struggle
Office reversed its first-quarter gain on the equal-weighted index, falling 1.50% on the quarter and 0.65% on the year, though it is still 4.80% above June 2022. The value-weighted office index dropped 2.41%, the steepest fall of any property type, and is down 4.63% over the year and 19.53% from June 2022.
Trepp says small buildings trade at slight discounts while large ones clear at much lower prices, a divide that reflects pricing and financing more than space demand.
Multifamily was flat equal-weighted, off 0.01% in the quarter, and is down 2.56% on the year and 3.49% from June 2022. Value-weighted multifamily fell 0.54% on the quarter and 3.41% on the year and is 17.80% below its June 2022 peak. Declines are slowing as supply pressure eases and expenses moderate, but fundamentals have not improved enough to offset the higher cost of capital.
Lodging remains the weakest. Equal-weighted prices fell 1.27% on the quarter and 6.53% on the year and are 16.98% below June 2022, with labor, insurance and capital costs weighing most on older or less competitive assets.
Why It Matters
Trepp says pricing stabilized through higher rates, geopolitical risk and the AI buildout, yet long-dated rates rose again in the third quarter. That leaves the recovery uneven by sector and deal size, with large institutional trades held back by financing and slower price discovery.
CRE Daily has tracked how property prices diverge as large investors return, and how buyers are pushing retrades as yields climb.
What’s Next
Trepp says higher rates will test the resilience it saw in Q2, since rates now bear down harder on deal activity and values. It also plans to add more transactions and broader geographic coverage in future TPPI updates.