- Chicago ranked as the most competitive large US rental market with a 91.8 score and about 17 prospective renters per vacancy.
- National rental competition eased slightly, but newly built apartments fell to just 0.5% of rental stock, limiting relief in tight markets.
- California markets posted some of the strongest year-over-year gains as tech-driven demand met scarce apartment supply.
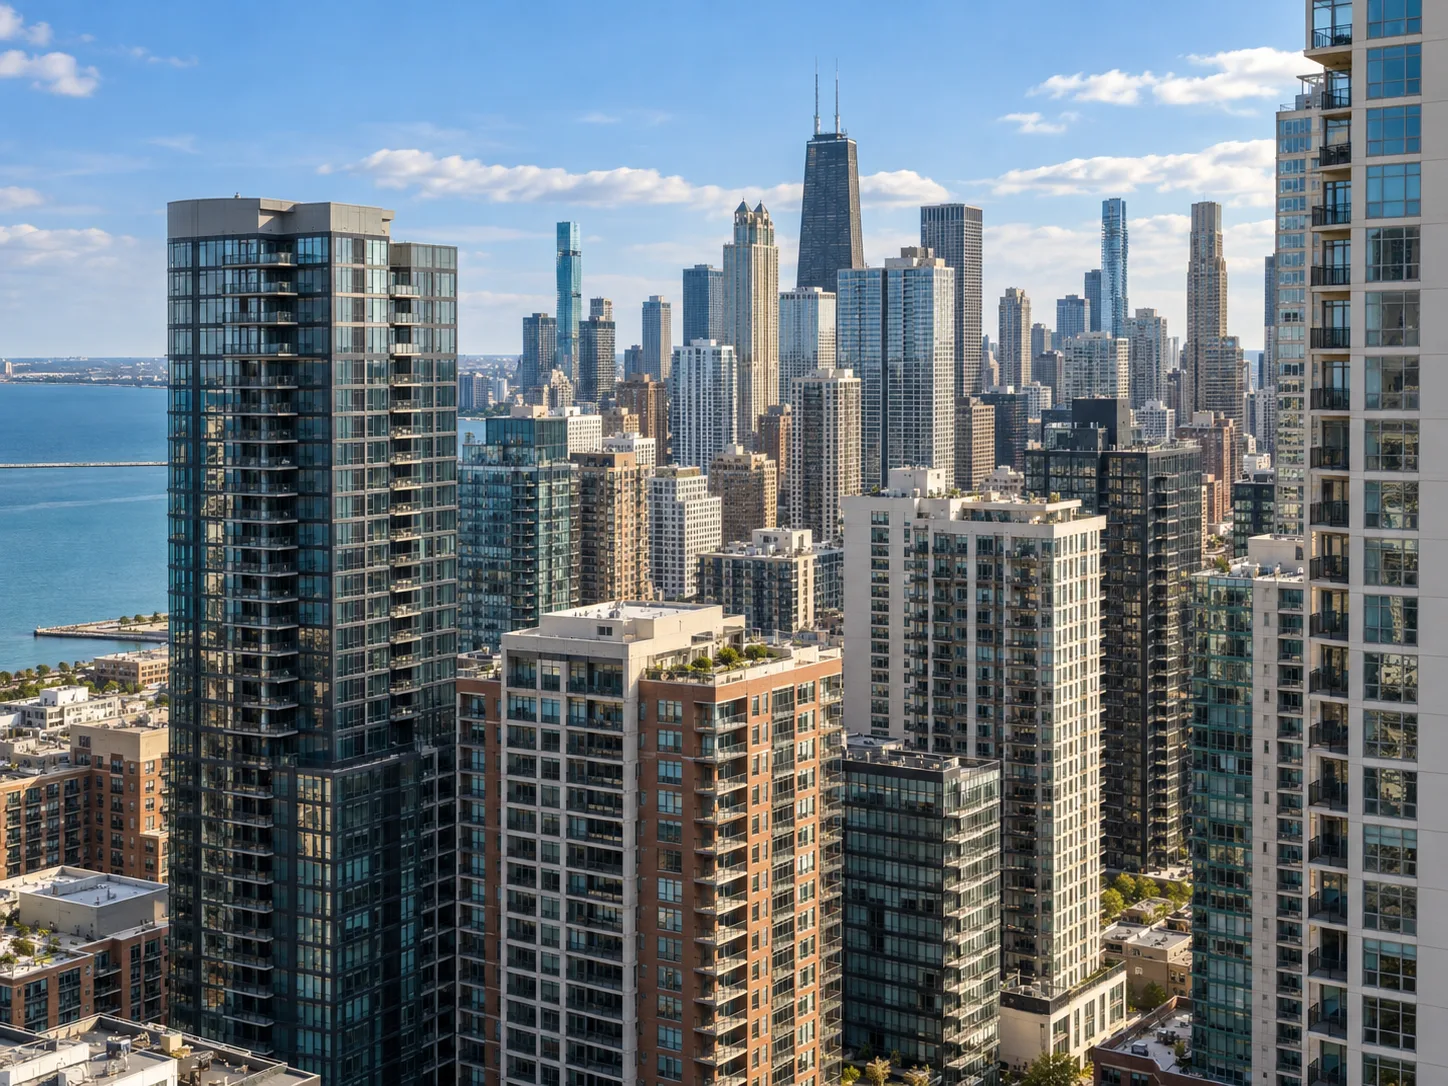
RentCafe reports in its peak-season rental competitiveness analysis that the Chicago rental market has overtaken Miami as the toughest large US market. The study used Yardi data across 139 markets. It measured prospective renters per vacancy, renewals, fill time, occupancy, and new supply. Chicago posted a Rental Competitiveness Index score of 91.8, the highest in the analysis.
Get Smarter about what matters in CRE
Stay ahead of trends in commercial real estate with CRE Daily – the free newsletter delivering everything you need to start your day in just 5-minutes
Chicago Rental Market Details
About 17 prospective renters competed for each available Chicago apartment, according to RentCafe’s analysis of Yardi data. Occupancy reached 95.4%, and vacant units filled in 27 days. Newly built apartments represented only 0.27% of local stock. RentCafe expects regional apartment deliveries to fall below 4,000 units in 2026. That would be the lowest level since 2012. The report also said the metro is short roughly 165,000 homes. Suburban Chicago ranked near the top as well, supported by a 70.8% renewal rate.
National Competition Eases Only Slightly
The US Rental Competitiveness Index slipped to 73.9 from 74.6 a year earlier.
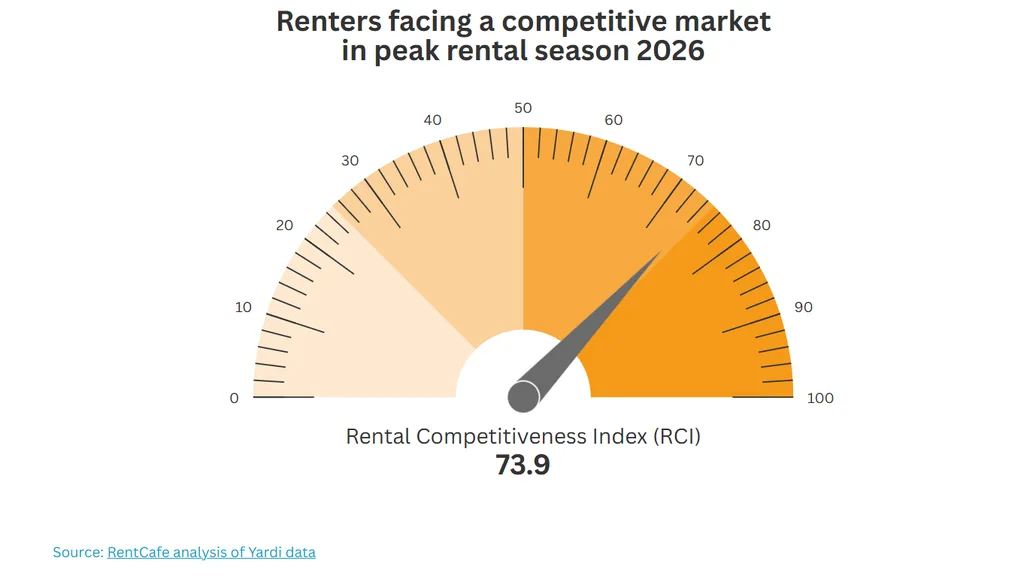
Nine renters still competed for each vacant apartment, matching last summer. Average fill time rose to 42 days from 40. Occupancy eased to 92.9% from 93.4%, while renewals were nearly unchanged at 62.8%. The biggest supply change was new construction. Newly built units made up 0.5% of rental stock, down from 0.8% a year earlier. RentCafe said the recent development wave is winding down.
Tight Supply Reshapes the Rankings
Miami ranked second with an 89.8 score. About 16 renters competed for each opening, nearly 96% of apartments were occupied, and 70% of renters renewed. Six of the 10 toughest large markets were in the Midwest. Grand Rapids, Milwaukee, and the Suburban Twin Cities all made the group. Chicago and Miami have been central to recent rental competition shifts. This year’s results show that limited supply can quickly reorder the rankings. Austin also tightened as its earlier supply wave receded.
California Markets Tighten Fast
The strongest year-over-year score gains among large markets were concentrated in California. East Bay rose 7.7 points and climbed 36 positions to 20th. Central Valley gained 5.9 points, Silicon Valley added 5.3, and the San Francisco Peninsula-North Bay gained 4.9. RentCafe tied the trend to the Bay Area technology rebound. CBRE data cited in the report showed AI companies have leased 21M SF across San Francisco and Silicon Valley since 2019. New apartment supply remains limited in several of those markets.
Small Markets Tighten Too
Smaller markets showed the same supply sensitivity. Youngstown, Ohio, ranked first in RentCafe’s detailed small-market table with an 87.6 score. Its renewal rate reached 77.1%, about 17 renters competed for each opening, and no new apartments were delivered.
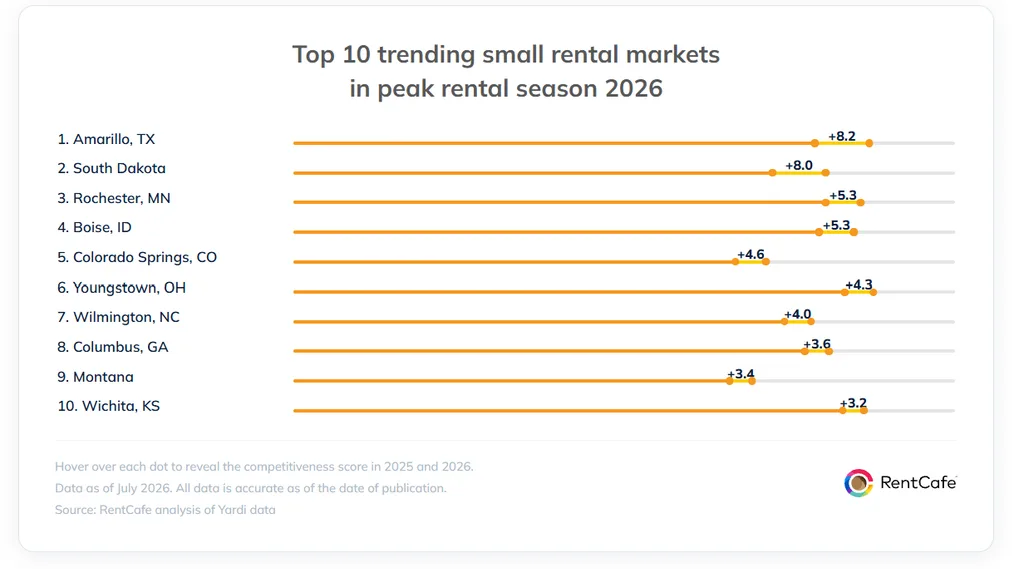
Amarillo ranked second at 87.0. Vacant units there filled in 22 days, the fastest pace in the analysis. RentCafe said limited supply and steady local demand helped both markets tighten.
Why It Matters
The report shows a national market that is somewhat easier for renters but increasingly local in its pressure points. Thin pipelines can keep competition high even when national occupancy and fill times soften. Chicago is the clearest example because very little new supply is reaching renters. Other markets are moving in the opposite direction. Orlando, Brooklyn, and Nashville have cooled after heavier deliveries created more choice. Lafayette, Indiana, and Fayetteville, Arkansas, also eased sharply among smaller markets after supply conditions changed. For owners, local delivery patterns can matter as much as broad national demand.
What’s Next
RentCafe expects Chicago deliveries to remain unusually low in 2026. Elsewhere, prior construction waves are still working through local markets. Orlando is expected to receive another high number of apartments, though at a more moderate pace. Nashville has added nearly 35,900 units since 2023, and concessions remain common in heavily supplied areas. The next phase of rental competition will therefore depend heavily on where pipelines have already thinned and where deliveries are still providing renters with leverage.